What to Do with a 401(k) When You Leave Your Employer
For many Americans, their 401(k) is their largest investment account—and the main source of income they’re counting on for retirement. But when you leave your job, what happens to that money? What’s the best move to keep your savings protected and growing?
The wrong decision could cost you thousands in taxes, penalties, or missed investment opportunities. In this guide, we’ll break down everything you need to know about your 401(k) after leaving an employer—including vesting rules, rollover options, and tax implications—so you can make the best choice for your financial future.
Let’s go over your options, the pros and cons of each, and how to roll over your 401(k) the right way—without triggering unnecessary taxes or penalties.
Step 1: Check Your Vested Balance
Before making a move, the first thing you need to do is determine how much of your 401(k) actually belongs to you.
Understanding Vesting
Your 401(k) balance is split into two parts:
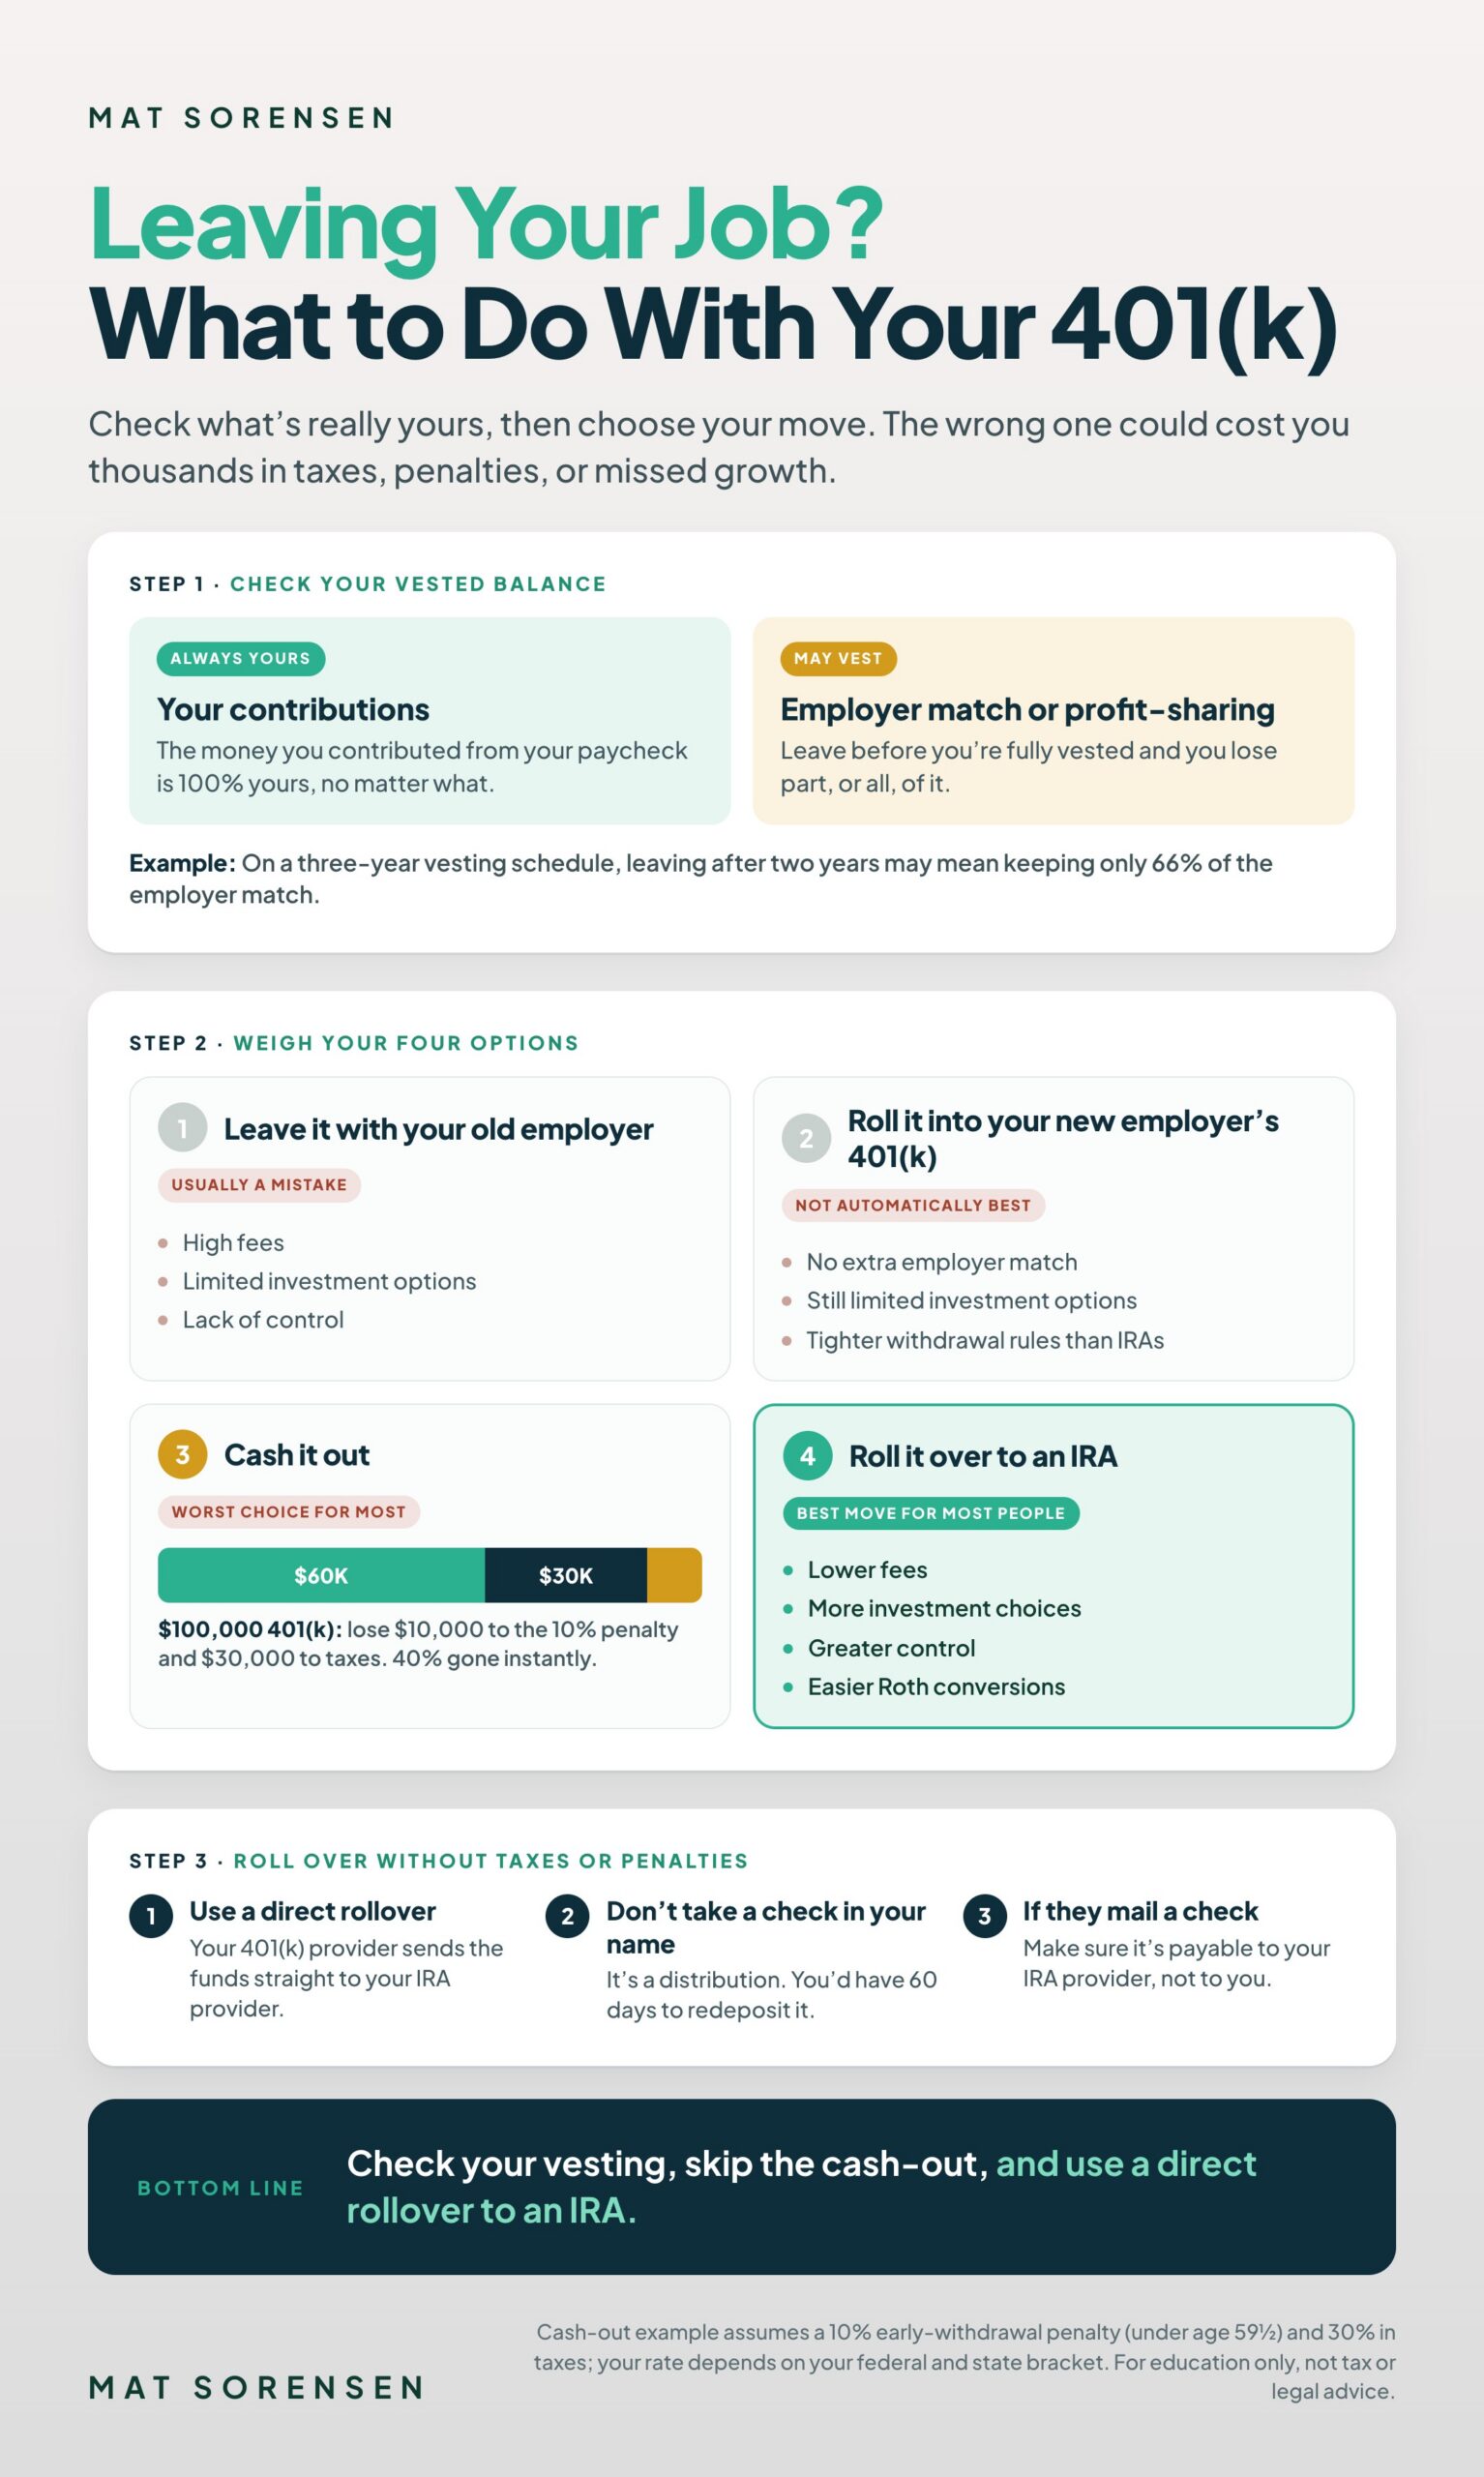
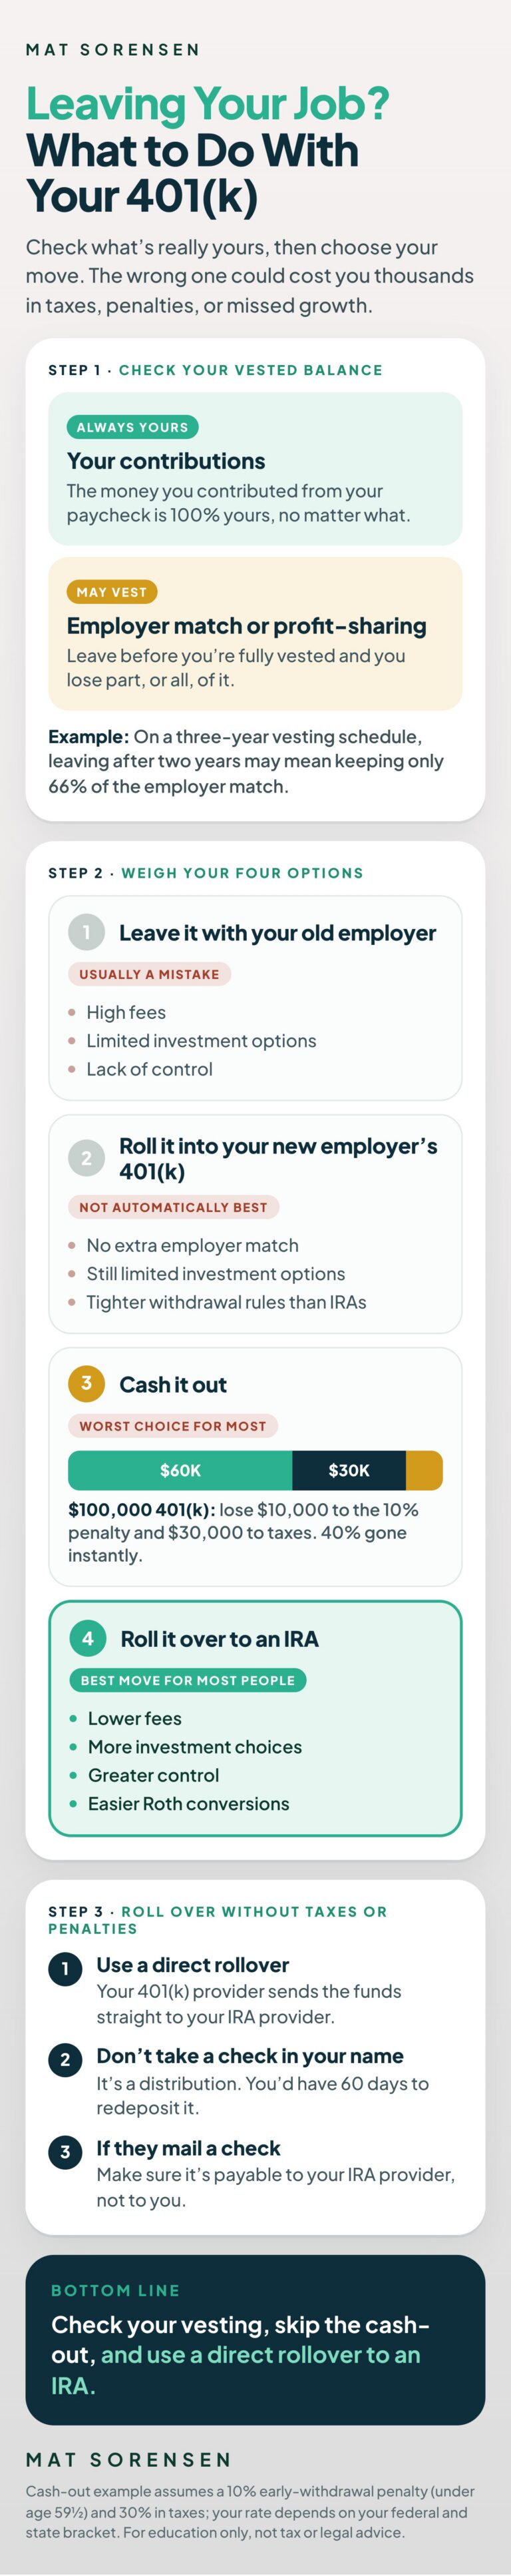
1. Your Contributions
The money you contributed from your paycheck. This is 100% yours, no matter what.
2. Employer Contributions (Match or Profit-Sharing)
This money may be subject to a vesting schedule. If you leave before you’re fully vested, you lose part (or all) of the employer contributions.
How to Check Your Vested Balance:
- 1Get your latest 401(k) statement – It will show vested vs. unvested balance.
- 2Review your company’s vesting schedule – This is outlined in your Summary Plan Description (SPD).
Know what you’re walking away with – Unvested employer contributions do NOT transfer when you leave.
Example: If your employer has a three-year vesting schedule and you leave after two years, you may only keep 66% of the employer match. If you leave too soon, you could be walking away from thousands of dollars in unvested money.
Once you know your true balance, you’re ready to decide where to move your funds.
Step 2: Weigh Your 401(k) Rollover Options
When you leave your employer, you have four main choices for handling your 401(k). Let’s go through each one.
Option 1: Leave Your 401(k) with Your Old Employer
Some people leave their 401(k) behind at their old job because it seems like the easiest choice. But in most cases, this is a mistake.
Cons of Keeping Your 401(k) at Your Old Job:
- ✕High fees – The average small business 401(k) charges 1.5% in fees, which could cost you thousands over time.
- ✕Limited investment options – Most plans restrict you to mutual funds and target-date funds—often with subpar performance.
- ✕Lack of control – You can’t make quick investment decisions, and accessing funds requires employer approval.
Bottom Line: If you no longer work there, why should your money stay there?
Option 2: Roll It Into Your New Employer’s 401(k)
If your new job offers a 401(k) plan, you may have the option to roll over your old 401(k) into the new one.
Cons of Moving to a New 401(k):
- ✕No financial benefit – Rolling over doesn’t give you extra employer matching.
- ✕Still limited investment options – You’re typically stuck with mutual funds or target-date funds.
- ✕More restrictive withdrawal rules – 401(k) plans often have tighter restrictions than IRAs.
Key Insight: Just because your new job has a 401(k) does NOT mean you should roll your old one into it.
Option 3: Cash Out Your 401(k)
You can withdraw your 401(k) as a lump sum when you leave—but this is one of the worst financial mistakes you can make.
Why Cashing Out Is a Disaster:
- ✕10% Early Withdrawal Penalty – If you’re under 59½, you automatically lose 10% to the IRS.
- ✕Massive Taxes – Your withdrawal is treated as ordinary income, which could push you into a higher tax bracket. For traditional 401(k)s the entire distribution is taxable. For Roth 401(k) balances, only the earnings are taxable if distributed early.
Example: If you cash out a $100,000 401(k):
That’s 40% gone instantly.
When Cashing Out Might Make Sense:
- ✓You’re 59½ or older and ready for retirement.
- ✓You have no other financial options in an emergency.
For most people, this is the worst choice.
Option 4: Roll Over to an IRA
Rolling your 401(k) into an IRA gives you more control, lower fees, and better investment choices.
Why an IRA Is the Best Move for Most People:
- ✓Lower fees – No employer plan fees eating into your returns.
- ✓More investment choices – Could be a brokerage IRA for stocks/ETFs (like Schwab or Fidelity), or a Self-Directed IRA for real estate, private companies, and funds (like at Directed IRA).
- ✓Greater control – No employer restrictions.
- ✓Easier Roth conversions – Convert to a Roth IRA for future tax-free growth.
How to Rollover to an IRA Without Taxes or Penalties:
- 1Use a direct rollover – This is critical to avoiding taxes. Your 401(k) provider should send the funds directly to your new IRA provider.
- 2Do NOT take a check in your name – If the check is made out to you, it’s a distribution. You have 60 days to redeposit it into an IRA—or the IRS treats it as taxable income.
- 3Some providers still mail checks – If they do, make sure it’s made out to your IRA provider, not to you personally.
Example: A 401(k) account owner requested a rollover, but the provider sent the check to the account owner. He didn’t redeposit it into an IRA and is now subject to taxes and penalties—and those funds can’t go back into a tax-advantaged account like an IRA.
Best Practice: Always request a direct rollover to the IRA provider to avoid a distribution, penalties, and taxes.
Special Situations to Check Before You Move Your 401(k)
A few situations change the math. Check these before you sign any rollover paperwork.
Leaving at 55 or Older: The Rule of 55
If you leave your job in or after the year you turn 55, withdrawals from that employer’s 401(k) aren’t hit with the 10% early withdrawal penalty. You still owe regular income tax on them. For qualified public safety employees in a government plan, and for private-sector firefighters, the age drops to 50 (or 25 years of service under the plan, if that comes first).
WATCH OUT
This exception only covers money that stays in that employer’s plan. It doesn’t apply to IRAs. If you roll everything into an IRA and later need cash before 59½, the 10% penalty can apply again. If you might need some of this money before 59½, factor that in before you roll it all over.
Leaving With an Unpaid 401(k) Loan
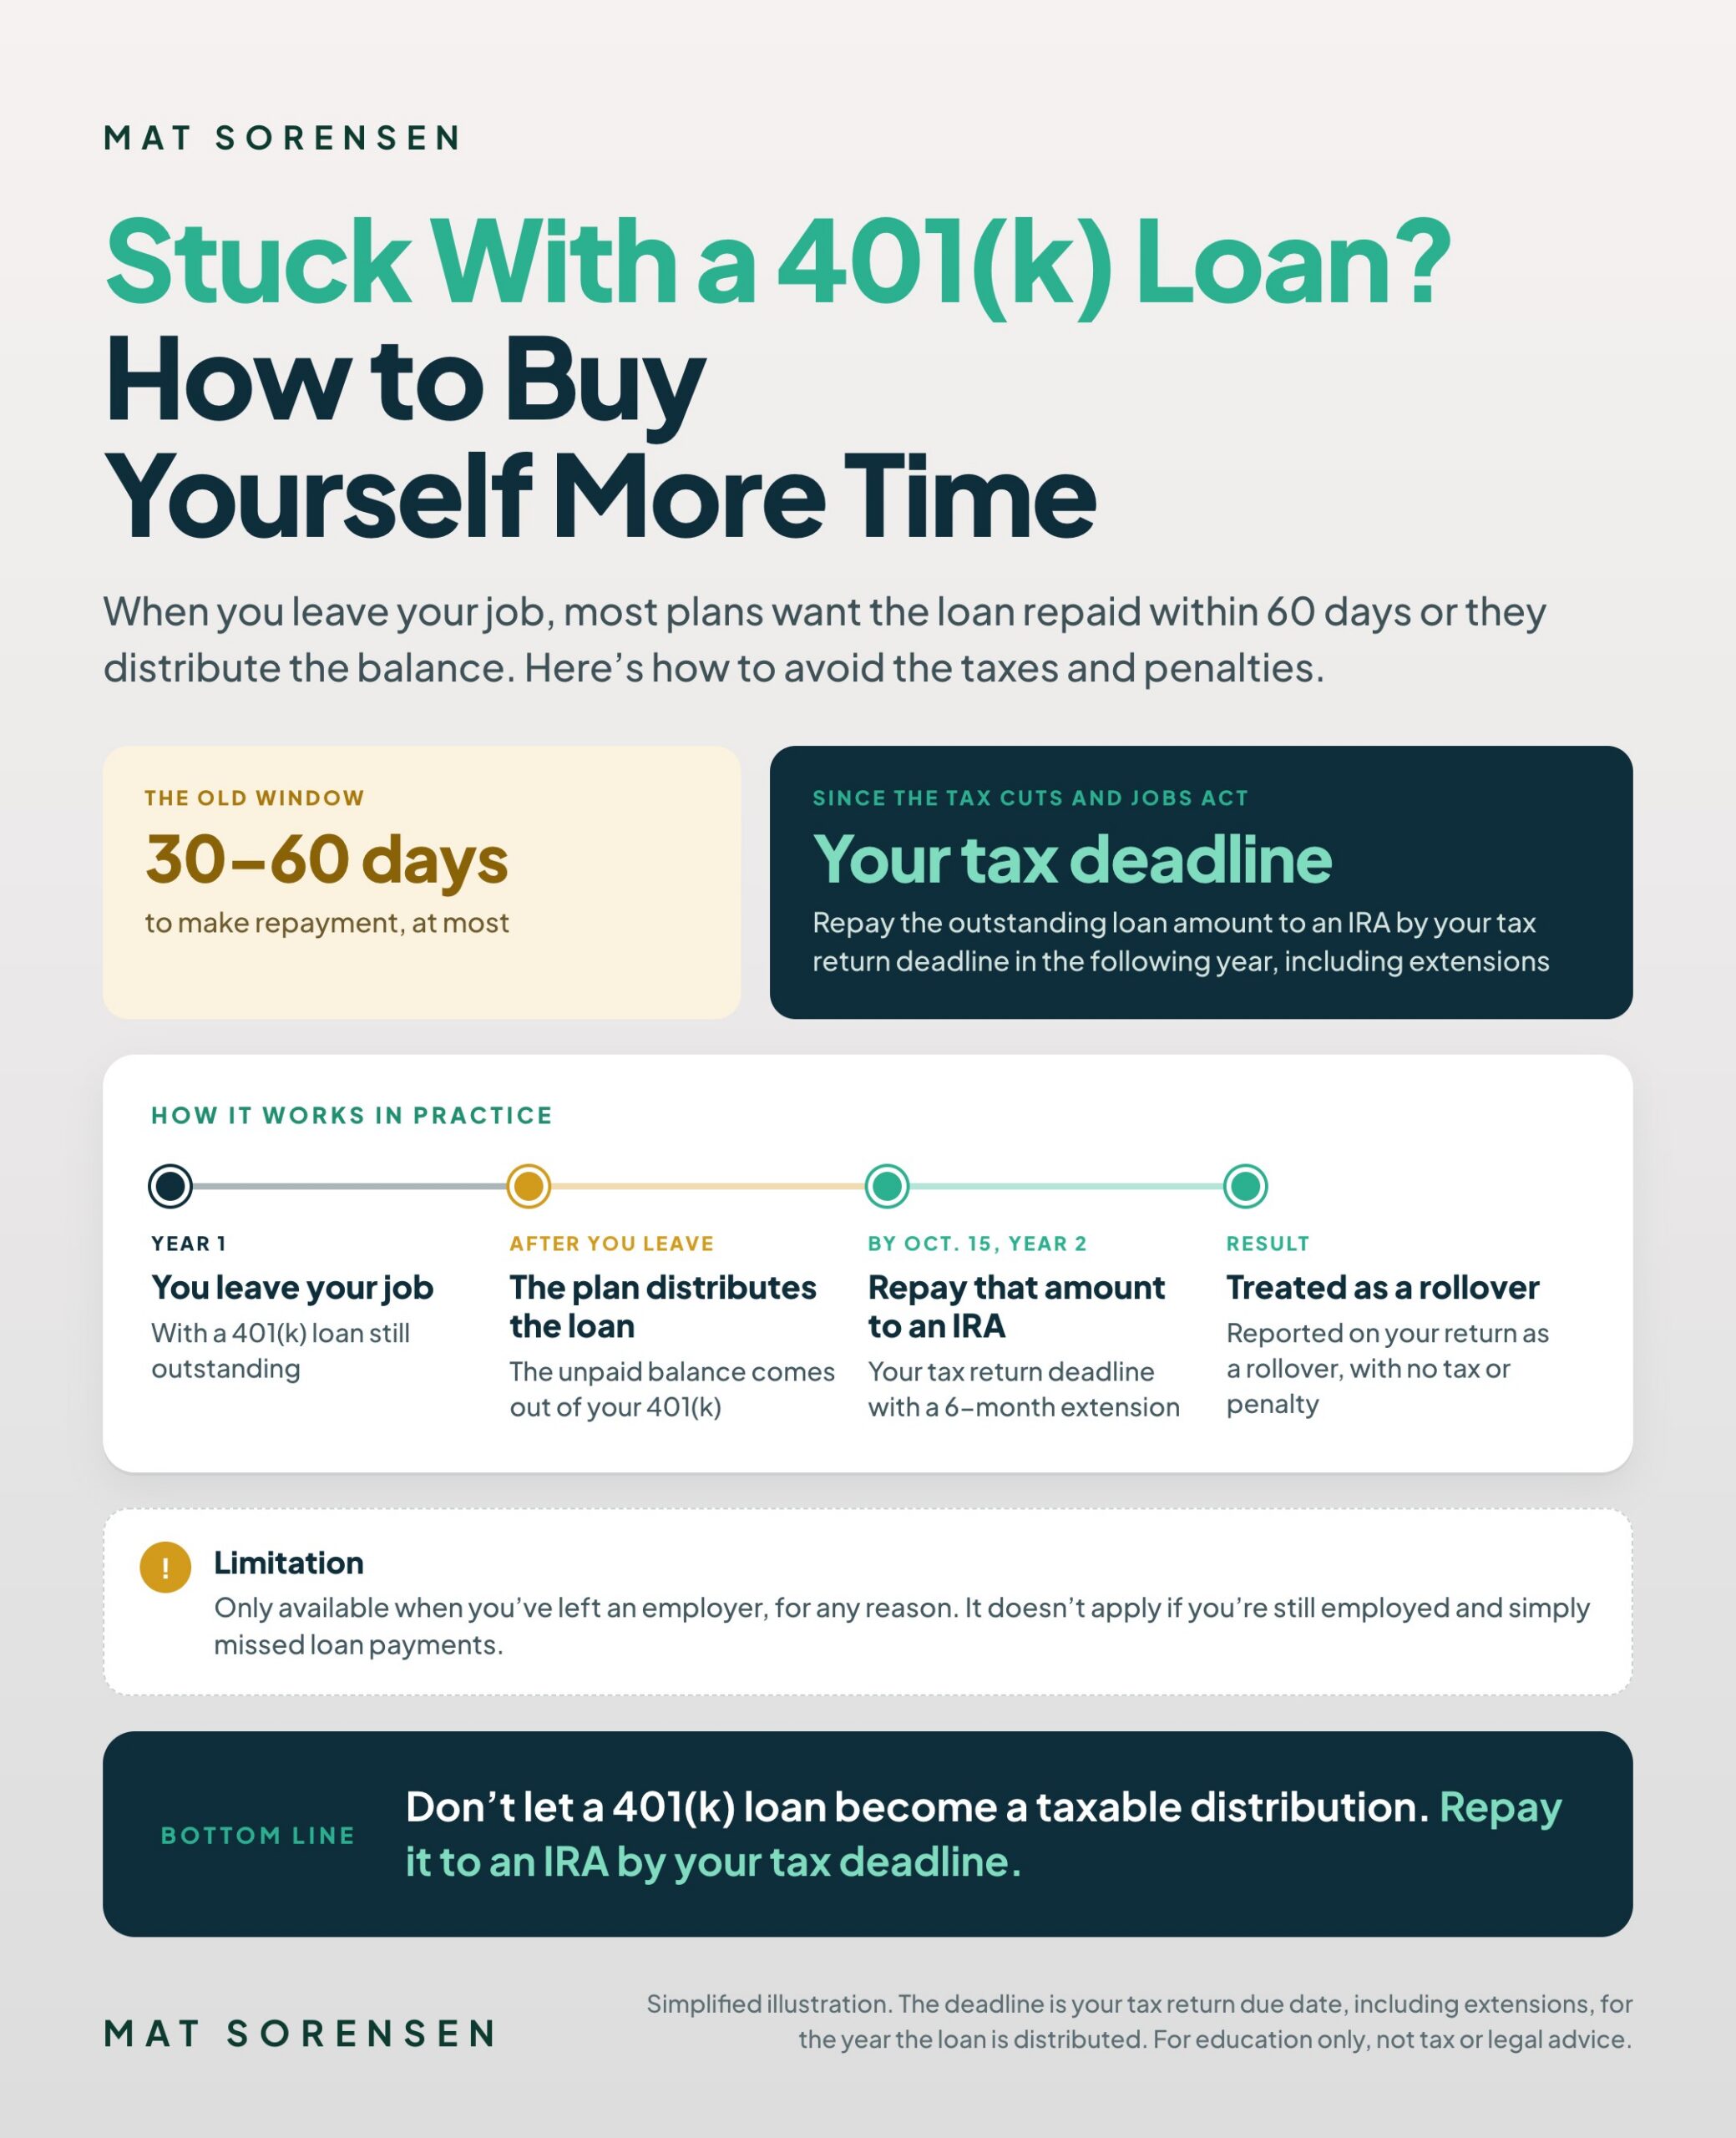
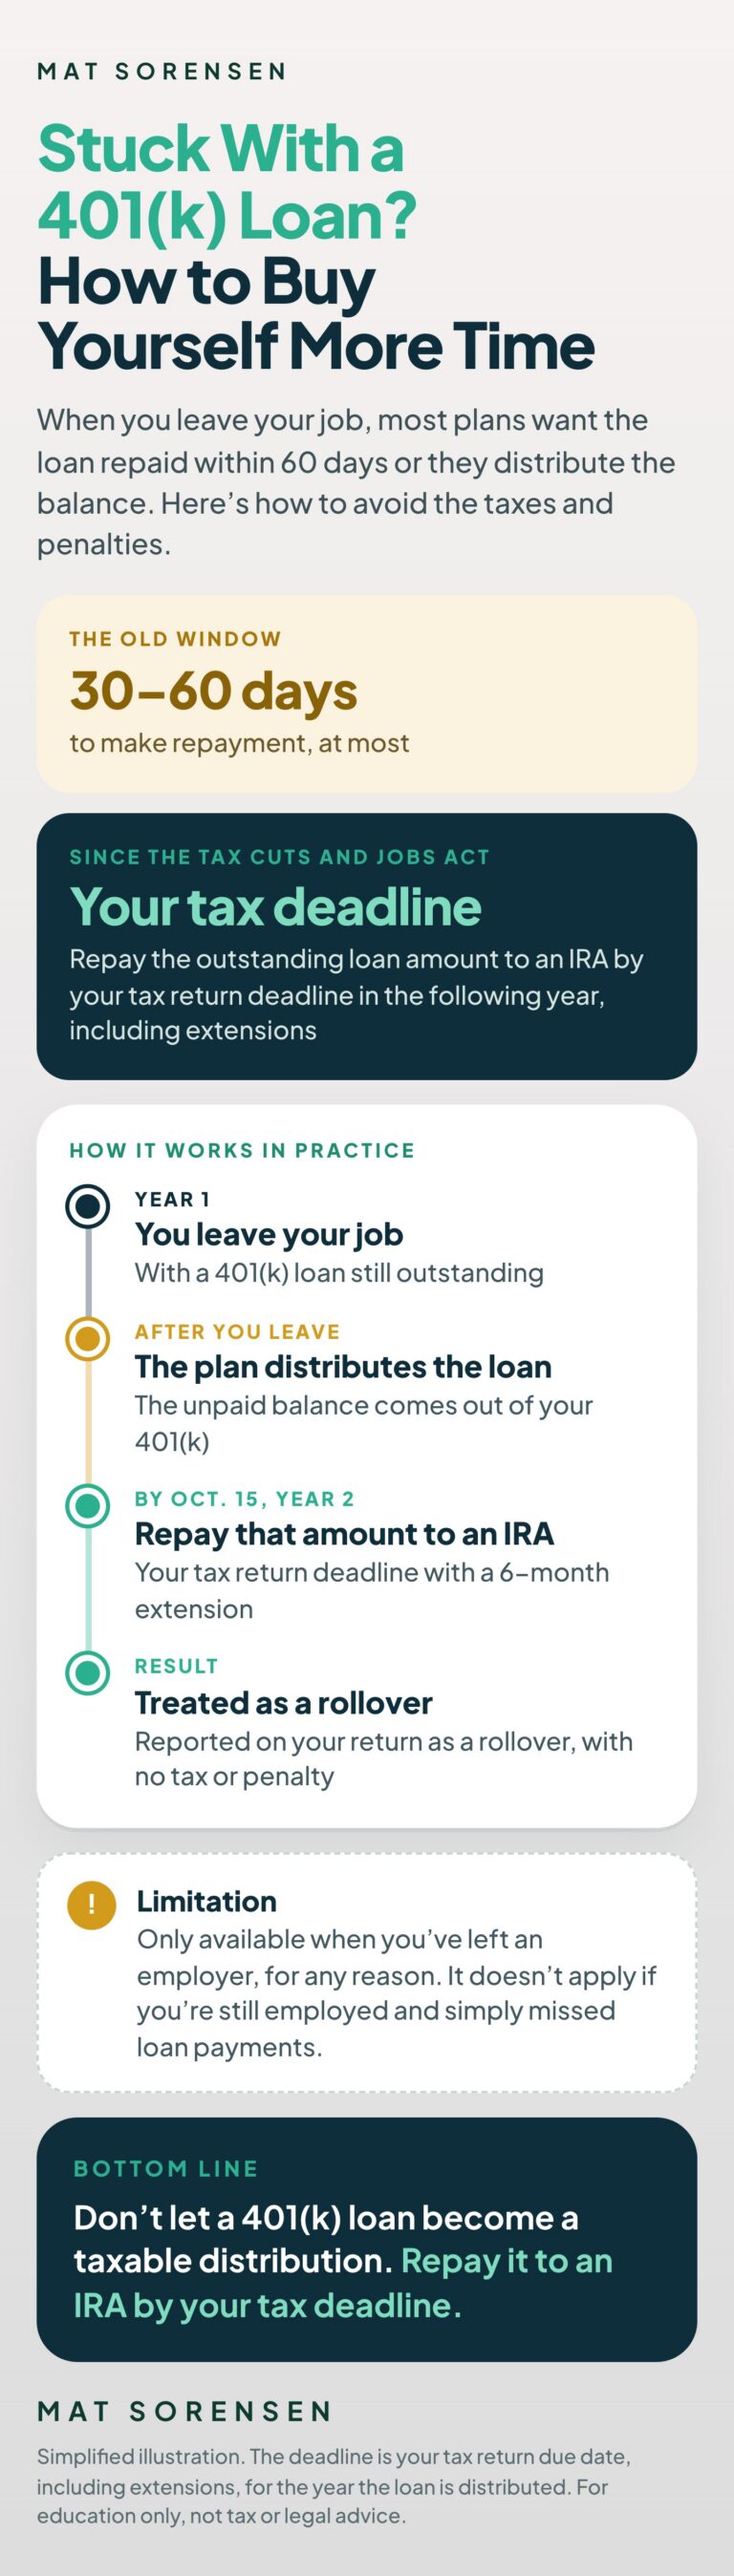
If you still owe on a 401(k) loan when you leave, the unpaid balance is often taken out of your account and treated as a distribution, called a loan offset. That makes it taxable, and the 10% penalty can apply if you’re under 59½.
You can avoid that by depositing the same amount into an IRA by your tax return due date, including extensions, for the year of the offset. For the full rules, see What Happens to a 401(k) Loan When You Leave Your Job?
Rolling Over a Roth 401(k)
Match each type of money to the right account. Pre-tax 401(k) money goes to a Traditional IRA, and Roth 401(k) money goes to a Roth IRA (or your new employer’s Roth 401(k)). If your plan holds both, you may need two rollover requests, one for each.
One timing catch: the years your money spent in the Roth 401(k) don’t count toward the Roth IRA’s five-year clock for tax-free earnings. If you contributed to a Roth IRA in an earlier year, your clock started with that first contribution.
If the Plan Pays You Instead: The 20% Withholding Trap
When your old plan pays the money to you rather than directly to your IRA, it must withhold 20% of the taxable amount for federal income tax, even if you plan to roll it over. To roll over the full amount, you have to make up that 20% from other money within 60 days.
EXAMPLE
You have $100,000 in your 401(k), and the plan sends you a check. It withholds $20,000 for taxes, so you receive $80,000.
To roll over the full $100,000, you deposit the $80,000 plus $20,000 of your own savings into an IRA within 60 days. The $20,000 that was withheld is credited toward your taxes when you file your return.
If you deposit only the $80,000, the missing $20,000 is treated as a taxable distribution. If you’re under 59½, it can also face the 10% penalty.
$100,000
Balance in your 401(k)
$20,000
Withheld for taxes
$80,000
Check you receive
A direct rollover avoids all of this, because nothing is withheld.
Small Balances Can Be Moved Without You
If your balance is small, your old plan may be allowed to cash it out or move it into an IRA in your name without waiting for your instructions. After you leave, watch for plan notices so you get to choose where your money goes.
How a Rollover to a Self-Directed IRA Works
Rolling into a self-directed IRA works the same way as rolling into any other IRA. A self-directed IRA is a Traditional or Roth IRA held with a custodian that allows alternative assets like real estate, private companies and funds. Here’s how it works with Directed IRA:
- 1Sort your money. Check your 401(k) statement for pre-tax and Roth balances.
- 2Open the matching IRA. Open a Traditional IRA for pre-tax money and a Roth IRA for Roth money.
- 3Request a direct rollover. Use your 401(k) provider’s rollover form (sometimes one per type of money) and have the funds sent to Directed Trust Company for your IRA, not to you.
- 4Give Directed IRA a heads-up. Let the team know a rollover is on the way so it lands in the right account.
- 5Invest. Once the funds arrive, you choose the investments and direct the IRA to make them.
Frequently Asked Questions
Do I have to move my 401(k) when I leave my job?
No. You can usually leave it in your old plan. The exception is small balances, which the plan may cash out or move to an IRA for you.
Is rolling a 401(k) into an IRA taxable?
No, not if you use a direct rollover and keep the money in the same tax bucket: pre-tax into a Traditional IRA, Roth into a Roth IRA. Rolling pre-tax money into a Roth IRA is a Roth conversion, so it’s taxable in the year you do it.
Does a 401(k) rollover count toward the once-a-year IRA rollover limit?
No. The one-rollover-per-year limit applies to IRA-to-IRA rollovers, not rollovers from an employer plan to an IRA.
Can I roll my 401(k) into a self-directed IRA?
Yes. A self-directed IRA isn’t a separate type of IRA under the tax code. It’s a Traditional or Roth IRA held with a custodian that allows alternative investments, so an old 401(k) can roll into it like any other IRA.
What if I already got a check made out to me?
You have 60 days from the day you received it to deposit it into an IRA. To roll over the full amount, add back the 20% that was withheld. The IRS can waive the 60-day deadline in some situations outside your control.
Key Takeaways
- ✓Check your vested balance first. Make sure you know how much of your 401(k) you actually own.
- ✓Leaving your 401(k) at your old employer is usually a bad idea – High fees and limited investment options make it less appealing.
- ✓Rolling your 401(k) into your new employer’s plan may not be the best move – You’ll still be stuck with high fees and limited investment options.
- ✓Cashing out your 401(k) is a terrible idea for most people under 59½ – Taxes and penalties could take 40% or more of your money.
- ✓Rolling over to an IRA is the best option for most people – It gives you lower fees, more investment options, and complete control over your retirement funds.
- ✓Use a direct rollover to avoid taxes and penalties – Never take a check in your name unless it’s your only option, and if you do, you must redeposit the same amount into an IRA within 60 days.
FREE ROLLOVER GUIDE
Learn how to move an old 401(k) or IRA into a self-directed IRA, tax-free.
Get the Free Transfers & Rollovers Guide
Prefer to talk it through? Book a call with a Directed IRA specialist