Critical Beneficiary Designation Rules for Your IRA or Other Retirement Accounts
 When you establish an IRA, 401(k), or other retirement account you are required to designate the beneficiary of that account so that the institution/custodian holding the account knows who will receive the account upon your death. You will die one day (sorry for the bad news), and without a properly completed beneficiary designation, your account will be stuck and won’t be able to be moved until a probate court orders otherwise. The form can be completed easily, so make sure you take care of this important step when establishing your retirement accounts and bank accounts.

What’s a beneficiary designation?
A beneficiary designation is simply a written and signed statement placed on record with your account custodian that specifies who receives your account upon your death. Beneficiary designations are used on IRA accounts, 401(k) accounts, HSA accounts, and life insurance policies. Beneficiary designations are used by IRA custodians, 401(k) account custodian/administrators, banks/credit unions, and life insurance companies to pass the deceased person’s account on to the person(s) designated on the form without reference to the deceased person’s will, trust, and without the involvement of the probate courts. As a result, your beneficiary designation form is a powerful instrument.
You can list a primary beneficiary and secondary beneficiaries. A primary beneficiary is the first person whom you list, and this person or persons receive the account upon your passing. A secondary (aka “contingent”) beneficiary is someone you list who receives the account if the primary beneficiary is not living. For example, a common way to list your beneficiary designations is to list your spouse as your primary beneficiary and your children as your secondary beneficiary. If your spouse is not living when you die, then your account passes to your secondary beneficiary.
Requirements for a Valid Designation
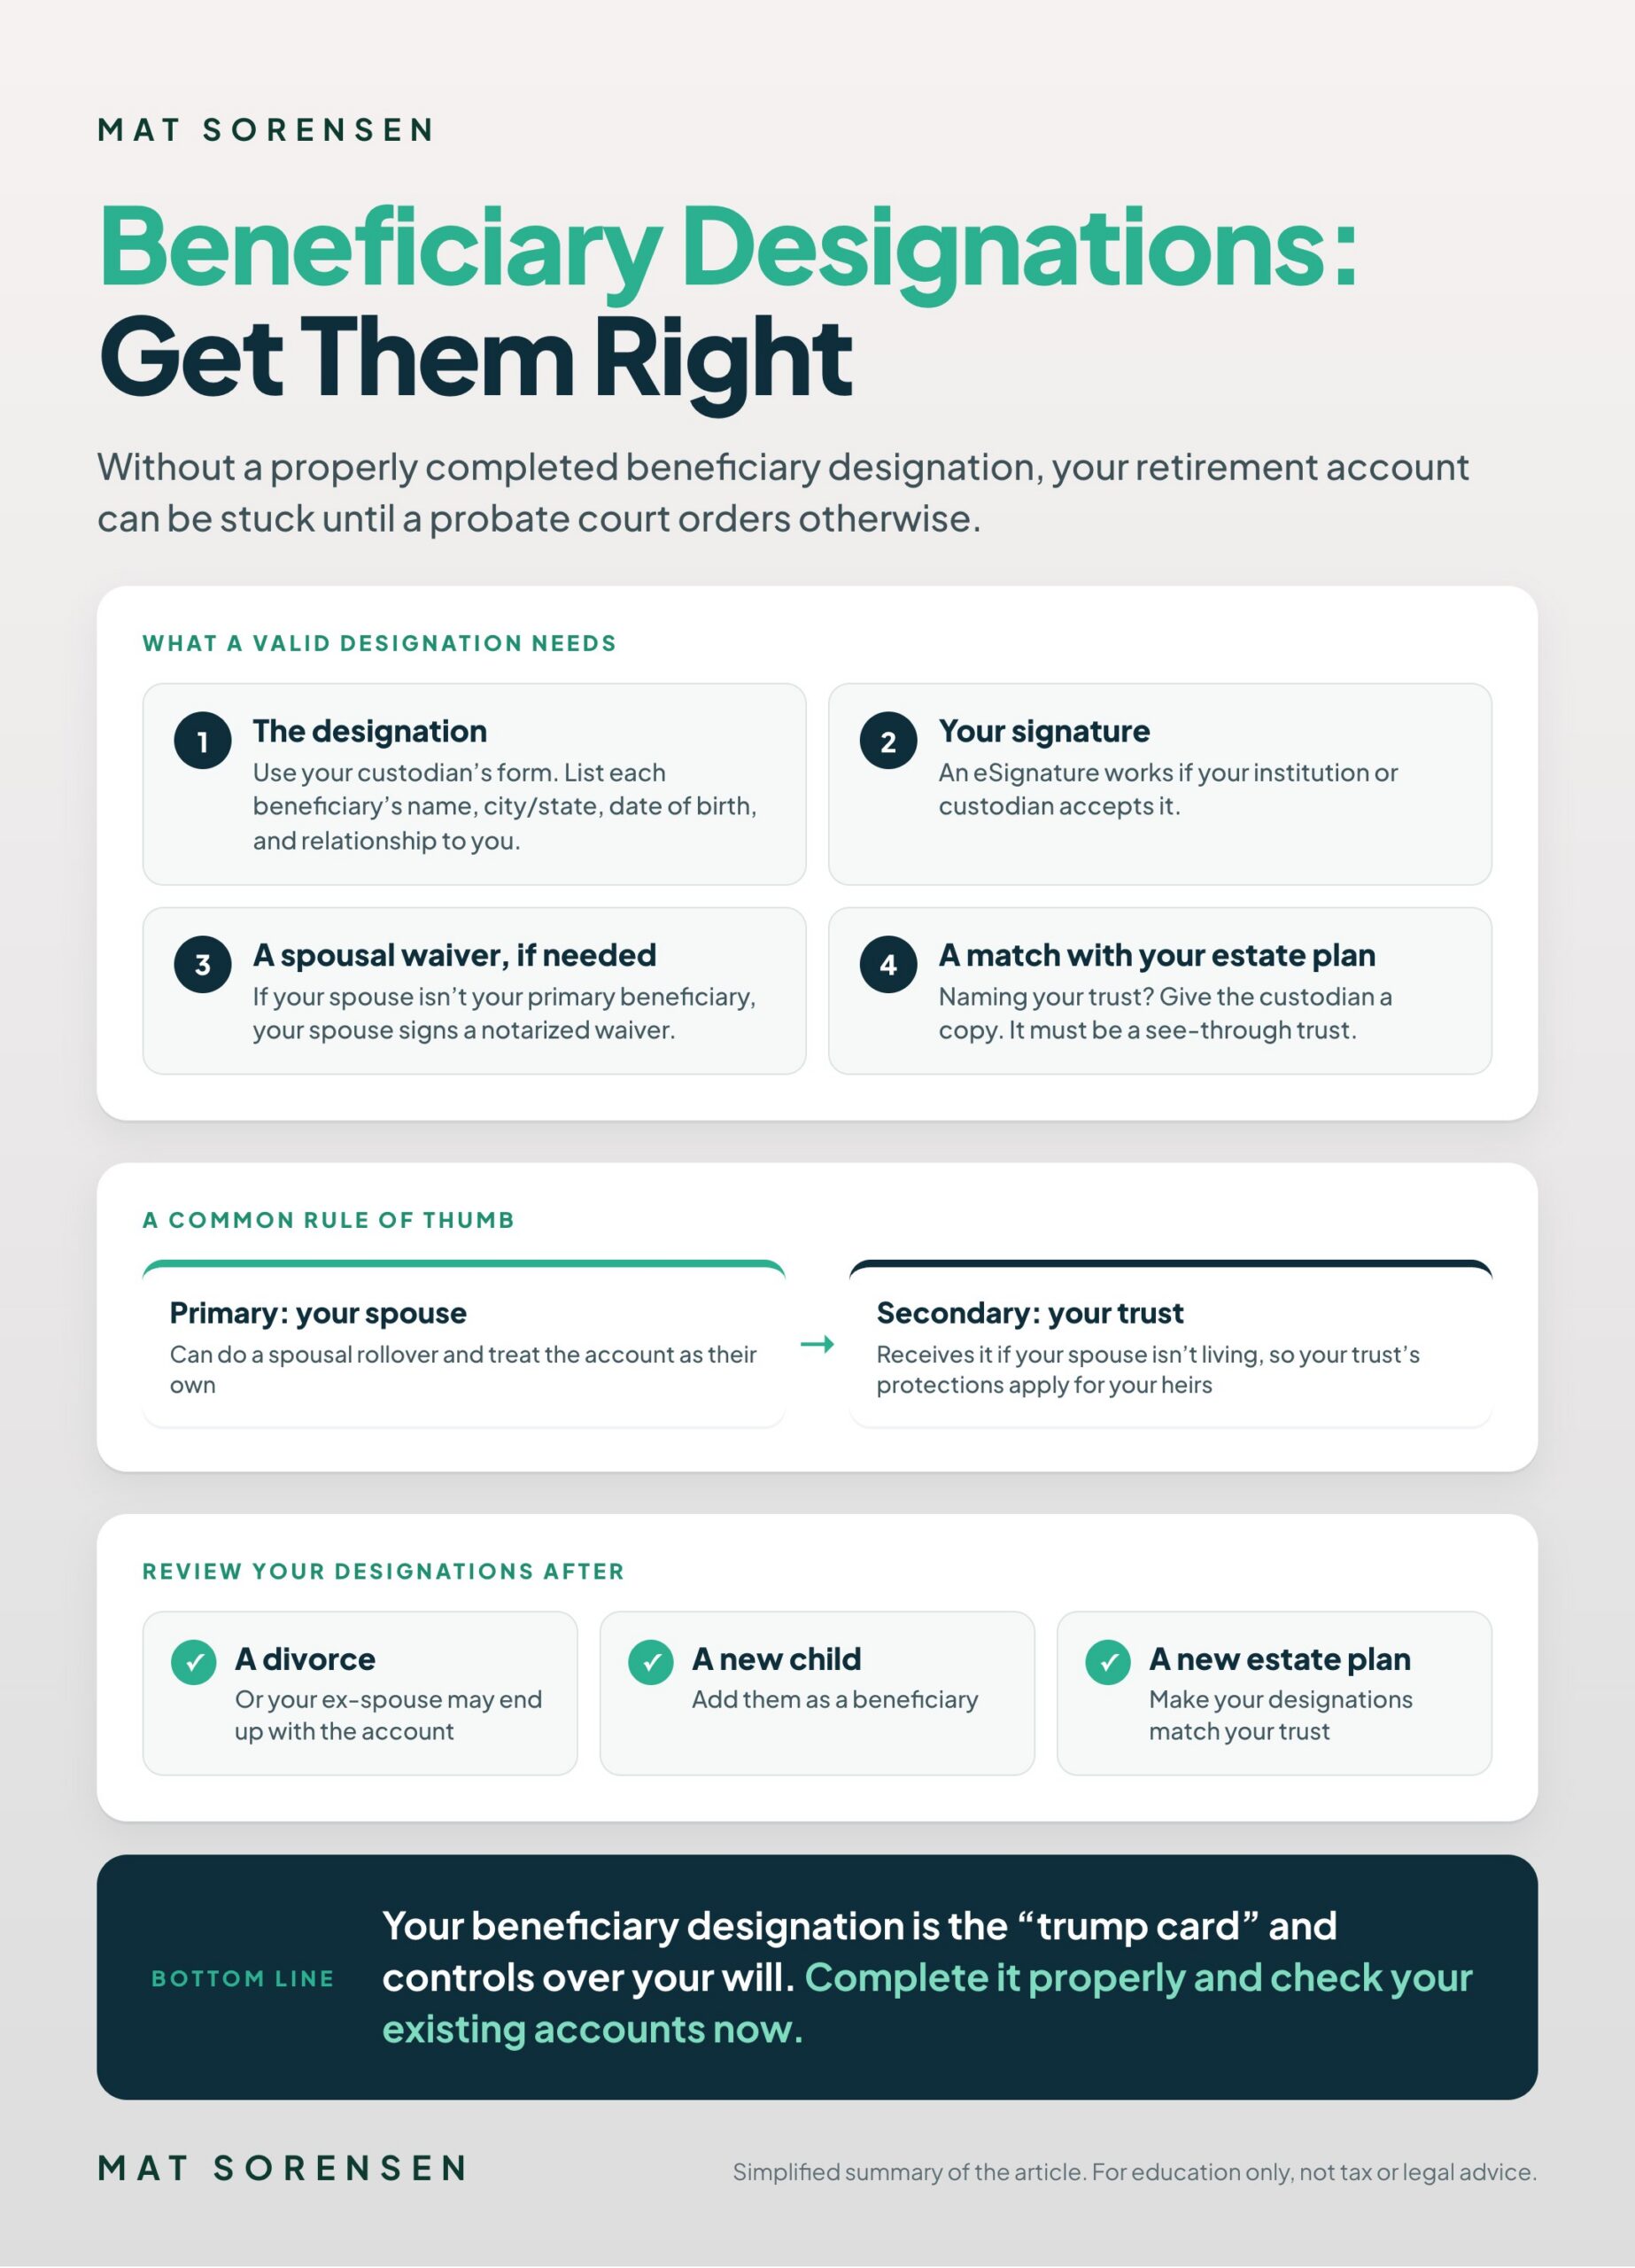
To have a valid beneficiary designation you must ensure the following:
- 1Designation: Use your institution’s/custodian’s form and designate the person(s) you desire as your beneficiary by listing their name, city/state, date of birth, and relationship to you. You can list one beneficiary or multiple beneficiaries in percentages. So, for example, if you had two children you wanted to receive the account, you would list them as 50% each on the designation form.
- 2Sign the designation: This may be eSigned using an eSign method accepted by your institution/custodian.
- 3Spousal waiver where applicable: If you have a spouse and you HAVE NOT listed your spouse as your primary beneficiary, then your spouse must sign a spousal waiver agreeing to someone else being listed as the primary beneficiary and your spouse’s signature on the waiver must be notarized. This is required as a matter of law. Failure to provide the waiver will result (at best) in your surviving spouse receiving at least half of your account upon your passing with the rest passing to your secondary beneficiaries.
- 4Coordinate with your estate plan: If you list your trust for estate planning as the beneficiary of your IRA, 401(k), or other retirement account, you must provide a copy of the trust to your institution/custodian. The trust must have readily identifiable beneficiaries who receive your account upon your passing and must be considered a see-through trust (most revocable living trusts are).
The beneficiary designation is the “trump card”
Your beneficiary designation is the “trump card” when it comes to estate planning documents. For example, your beneficiary designation on your retirement account or bank account will control over a will which states someone different is to receive all your assets. As a result, it is critical that you provide a beneficiary designation for every account you have, and that these designations are updated when certain major life events arise.
Action required in three common situations
If you already provided beneficiary designations on your retirement accounts, bank accounts or life insurance, it is critical that you review them and update them upon the following events:
- 1Divorce: There are plenty of cases when someone who failed to update their beneficiary designation passes away and their ex-spouse ends up receiving the account. This is usually contrary to the account owner’s wishes, but if you fail to update your beneficiary designations, your heirs could be in this predicament. (Talk about not leaving gracefully!) This situation is now going to be ugly for your ex, your new spouse (if you had one), and your children.
- 2New child: If you have a new child who was not previously identified as a beneficiary, you should update your designations to add this new child.
- 3New estate plan: If you establish an estate plan (will, or ideally, revocable living trust), you should ensure that your wishes in your beneficiary designations for your retirement accounts and bank accounts match-up with the terms of your trust.
When to list your trust versus your spouse/children directly
Even if you have a revocable living trust, you may want to list your spouse as your primary beneficiary. As a rule of thumb, most estate planning attorneys recommend that, for IRA or 401(k) accounts, you list your spouse as your primary beneficiary and your trust as your secondary beneficiary. The reason is that your spouse can receive your retirement account upon your passing and can do what is called a spousal rollover. This rule only applies to spouses. For example, under a spousal rollover, the retirement account of the deceased person can be transferred/rolled over into an IRA of the surviving spouse. This is an advantageous way for a spouse to receive a retirement account as the account is treated simply as an account of the surviving spouse, and is not subject to RMD or other quirky rules associated with inherited retirement accounts (aka “inherited IRAs” or “beneficiary IRAs”). Rather, the funds are just treated as a Traditional IRA or Roth IRA of the surviving spouse.
Your Trust can be listed second, and, in the case where your primary beneficiary is not living, certain provisions in your trust designated to protect the funds from creditors or misappropriation from inheriting children or other heirs would apply. Your children, or other heirs under your trust who are listed as secondary beneficiaries on your form would receive the funds from your retirement account in an inherited IRA (aka “beneficiary IRA”) and would have RMD requirements to remove funds from their account over their life expectancy. This is sometimes called a “stretch IRA” and is a great tax strategy as it allows them to extend the tax-free (Roth) or tax-deferred (Traditional) benefits of the account over their own lifetime.
UPDATE (NOV 2026)
For owners who died after 2019, the SECURE Act limits the lifetime “stretch” to eligible designated beneficiaries: a surviving spouse, the owner’s minor child (until 21), a disabled or chronically ill beneficiary, or someone not more than 10 years younger than the owner. Most other beneficiaries must empty the account within 10 years, and if the owner had already started RMDs, they also take yearly RMDs during those years (required from 2025). (Source: IRS final regulations, 2024)
Remember, the beneficiary designation is critical and must be completed properly. Take the extra time to get it done right, and check up on the designations on any of your existing accounts that you may be unsure of. It’s better to get these things squared away and in order now than to presume that you completed them right when you set-up the account long ago.
INHERITED IRA
Inherited an IRA? Talk with a Directed IRA specialist about your options for self-directing it.