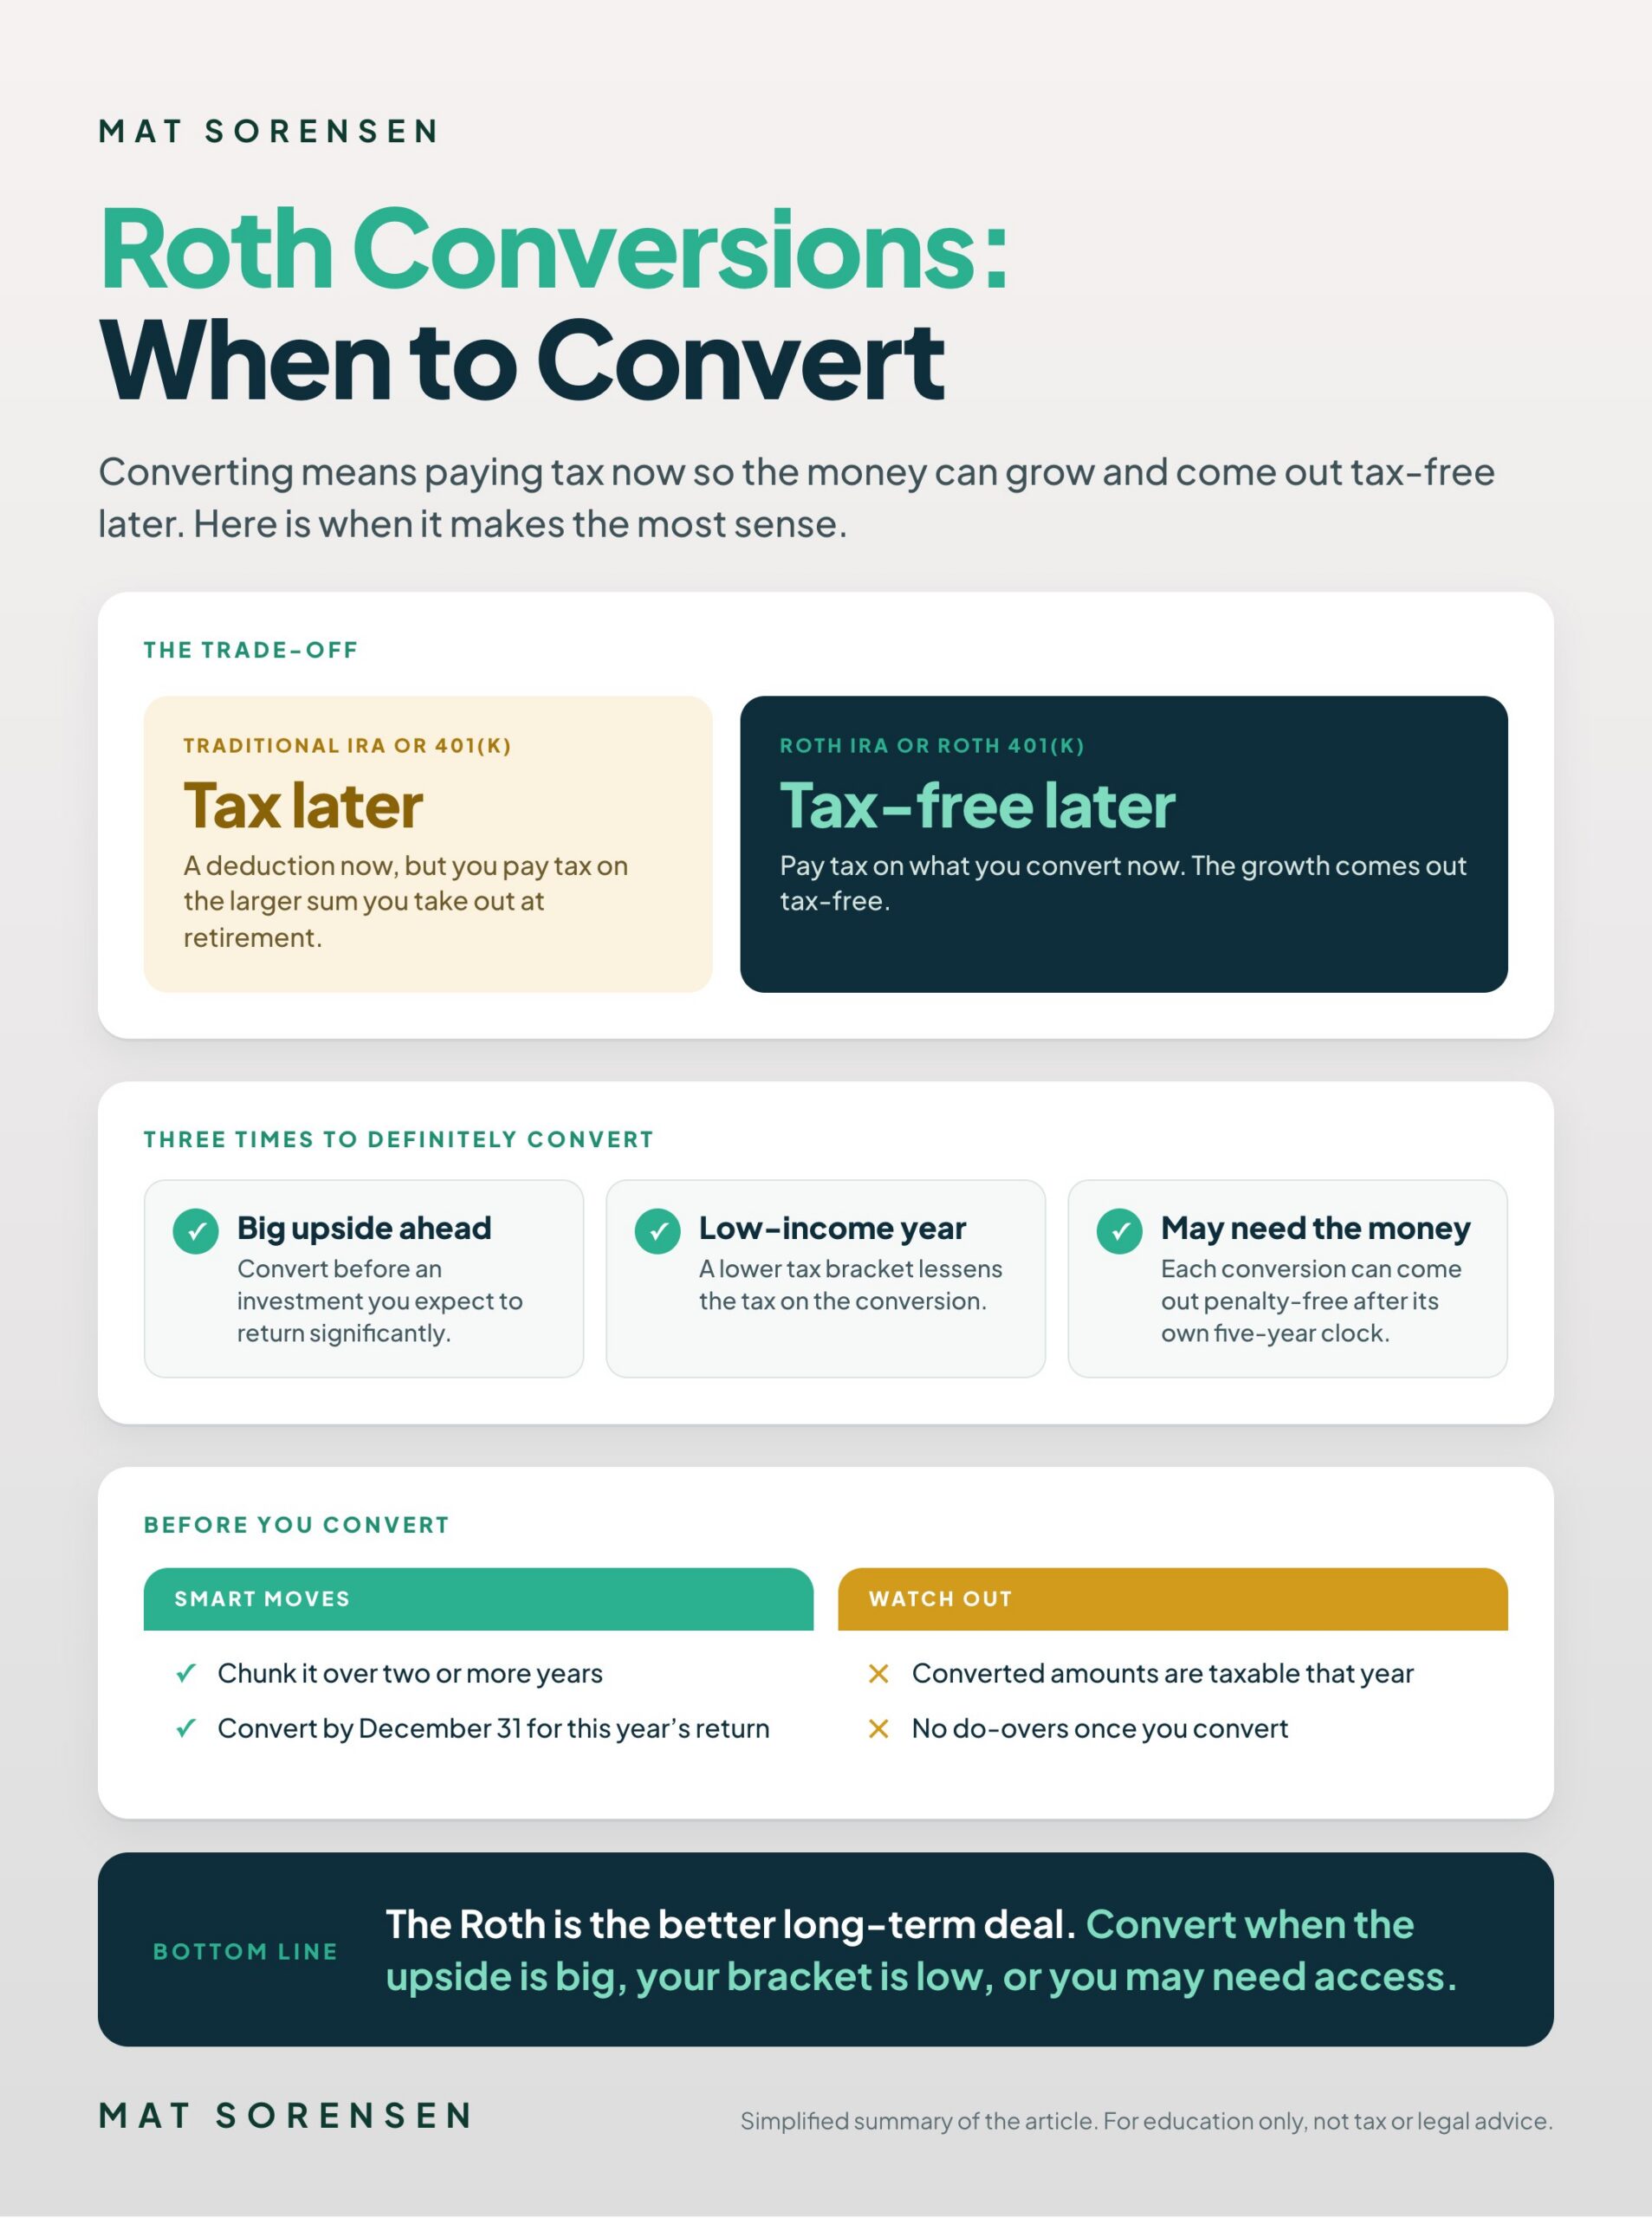
Many Americans convert traditional dollars to Roth when account values are down or when they’re in a lower tax bracket than usual. If you have a traditional IRA or 401(k), then that money grows tax-deferred, BUT you pay tax on the money as it is drawn out at retirement. And that’s a big BUT. On the other hand, you get zero tax deduction on Roth IRA and Roth 401(k) contributions but they grow and come out tax-free at retirement. What’s better? Well, in the end the Roth account is a much better deal as you’re pulling out what you put in AND the growth of the account after years of investing and saving. That’s likely a larger amount than what you put in so you’d typically be better paying tax on what you put in (or convert) rather than paying tax on the larger sum that you will take out later. The trade-off of course, is you’re playing the long game. You’re skipping a tax deduction or paying tax now to convert in return for tax-free growth and tax-free distributions at retirement. The Roth seems to be the better deal. Yet, most Americans have been sucked into traditional IRAs and 401(k)s because we get a tax deduction when we put the money in a traditional account, saving us money on taxes now.
For more on the differences between Roth IRA and Roth 401(k), take a look at the video from my Partner Mark J. Kohler:
How a Roth Conversion Is Taxed
The good news is that you can convert your traditional IRA to a Roth IRA, or your traditional 401(k) to a Roth 401(k). The price to make that conversion is including the amount you convert to Roth as taxable income for the year in which you make the conversion. So, if I convert $100K from my traditional IRA to a Roth IRA in 2026, I will take that $100K as income on my 2026 tax return, then pay any federal and state taxes on that income depending on my 2026 tax bracket. Many retirement account owners want to move their traditional funds to Roth, but don’t like the idea of paying additional taxes to do so. It can be a big tax hit when you do your taxes. I get it. Nobody likes paying more taxes now, even if it clearly saves you more as your account grows and the entire growth comes out tax-free.
Chunking Conversions
One way to soften the tax blow of the Roth conversion is to chunk the amount you want to convert over two or more years. For example, if it’s November 2026 and you want to convert $100K to Roth, you could convert $50K by December 31, 2026, and the remaining $50K in January 2027. That spreads the tax over two years. You could also convert about $33K a year over three years.
When You Should Definitely Convert
The following are three cut-and-dry situations of when you should definitely convert your traditional IRA or 401(k) funds to Roth:
1. Up-Side Investment Opportunity – I’ve had numerous clients over the years convert their traditional funds to Roth before investing their account into a certain investment. They’ve done this because they’ve had a tremendous investment opportunity arise where they expect significant returns. They’d rather pay the tax on the smaller investment amounts now, so that the returns will go back into their Roth IRA or 401(k), where it can grow to an unlimited amount and come out tax-free. These clients have invested in real estate deals, start-ups, pre-IPOs, and other potentially lucrative investments. So, if you have an investment that you really believe in and will likely result in significant returns, then you’re far better off paying a little tax on the amount being invested before the account grows and returns a large profit. That way, the profit goes back into the Roth and the money becomes tax-free.
2. Low-Income Year – Another situation where you should convert traditional funds to Roth is when you have a low-income tax-year. Since the pain of the conversion is that you have to pay tax on the amount that you convert, you should convert when you are in a lower tax bracket to lessen the blow. For example, if you’re married with $40,000 of taxable income and you convert $50,000 to Roth, the entire conversion falls in the 12% federal bracket, for about $6,000 in federal tax. If you instead convert in a year when you have $250,000 of taxable income, the same $50,000 conversion is taxed at 24%, or about $12,000. That’s twice the tax. Keep in mind that you also pay state tax on the amount that you convert (if your state has state income tax), and most states have stepped brackets where you pay tax at a lower rate when you have lower income. Now, you may not have taxable income fluctuations. But, for those who are self-employed, change jobs and have a loss of income, or have investment losses where taxable income is lower than normal for a year, you should think about converting your retirement funds to Roth. You may not have a more affordable time to make the Roth conversion.
3. Potential Need for a Distribution After Five Years – One of the perks of Roth accounts is access. Your Roth contributions can come out anytime, tax- and penalty-free. Converted amounts aren’t taxed again when you take them out. But if you’re under 59 1/2, each conversion has its own five-year clock for the 10% early withdrawal penalty, starting January 1 of the year you convert. So if you convert in November 2026, you can take out the converted amount penalty-free starting January 1, 2031. (For more, see The Roth IRA 5-Year Rule Everyone Gets Wrong.) If you try to access funds in your traditional IRA or 401(k) before you are 59 1/2, then you will pay tax and a 10% early withdrawal penalty even if the amounts you distribute are only the contributions you put in, not the investment gains. Clearly, the Roth account is much more accessible in the event you need personal funds. Keep in mind, you don’t get this perk immediately: You have to wait 5 years from the tax year in which you converted before you can take out the converted amount penalty-free.
WATCH OUT
One final thought to consider when converting to a Roth is that there are no do-overs. You used to be able to do what was called a Roth re-characterization where you could undo a Roth conversion but the ability to undo a Roth conversion was eliminated in 2018 forward. As a result, make sure you’re committed before you convert as there are no mulligans, do-overs, or re-characterizations anymore. Also, if you want the conversion to fall onto your current year tax return, then make sure you convert those sums by December 31. For the most common ways conversions go wrong, see Roth Conversion Mistakes That Could Wreck Your Retirement Plan.
FREE SELF-DIRECTED IRA GUIDE
Learn how a self-directed Roth IRA can invest in real estate, private companies, notes, and more, and keep the growth tax-free.
Get the Free Self-Directed IRA Guide
Prefer to talk it through? Book a call with a Directed IRA specialist

Mat has been at the forefront of the self-directed IRA industry since 2006. He is the CEO of Directed IRA & Directed Trust Company where they handle all types of self-directed accounts (IRAs, Roth IRAs, HSAs, Coverdell ESA, Solo Ks, and Custodial Accounts) which are typically invested into real estate, private company/private equity, IRA/LLCs, notes, precious metals, and cryptocurrency. Mat is also a partner at KKOS Lawyers and serves clients nationwide from its Phoenix, AZ office.
He is published regularly on retirement, tax, and business topics, and is a VIP Contributor at Entrepreneur.com. Mat is the best-selling author of the most widely used book in the self-directed IRA industry, The Self-Directed IRA Handbook: An Authoritative Guide for Self-Directed Retirement Plan Investors and Their Advisors.