Roth Conversion Mistakes That Could Wreck Your Retirement Plan

Roth conversions are one of the most frequently recommended strategies in retirement planning, and for good reason. I appreciate their benefits for a variety of reasons, but they’re not suitable for everyone.

In this article, I’ll cover eight common scenarios where a Roth conversion may actually not make sense. These are not obscure or unusual situations; they’re real-world examples I see regularly in practice.

The challenge is that Roth conversions have been oversimplified into the idea that you should always convert. In reality, this approach ignores important factors such as current and future tax rates, timing, retirement income planning, and even your age. Getting a conversion right can create tens or even hundreds of thousands of dollars in long-term savings. Doing it wrong can have the opposite effect.
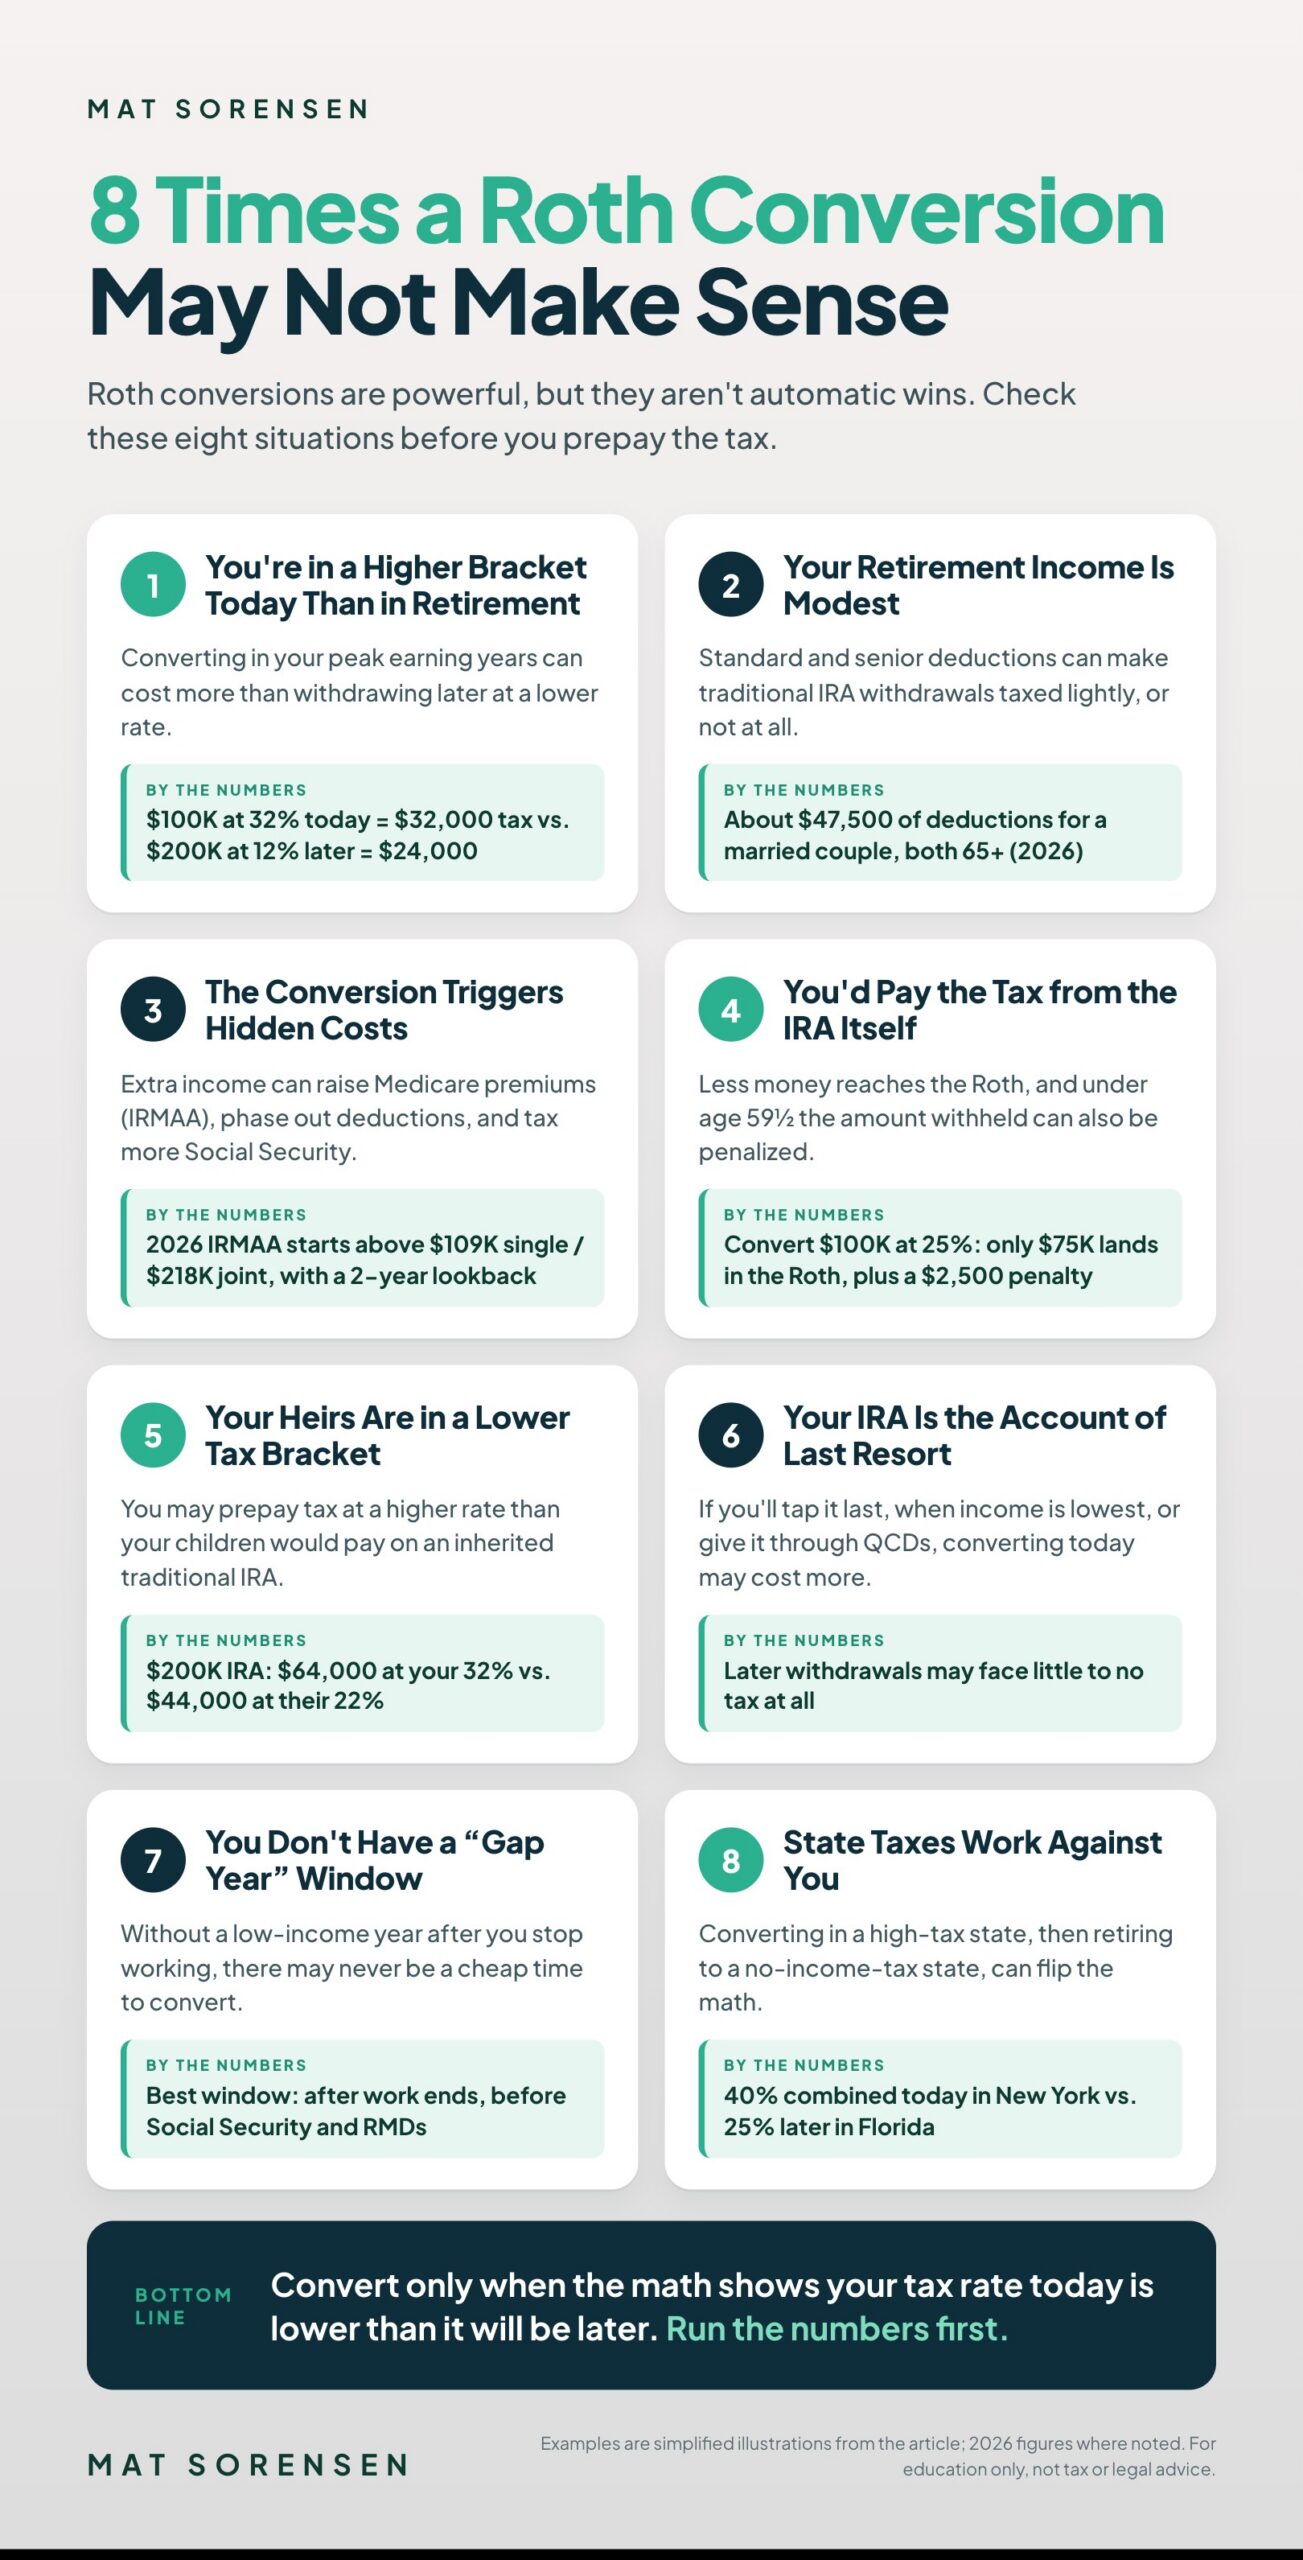
Infographic: 8 times a Roth conversion may not make sense

The Core Principle: It’s a Tax Rate Arbitrage Decision

Before diving into specific scenarios, it’s important to understand the core principle behind a Roth conversion. When you convert traditional IRA funds to a Roth, you pay taxes today so that future withdrawals are tax-free.

At first glance, it may seem straightforward: convert now if your current tax rate is lower than what you expect to pay later. For example, imagine you’re 50 years old with a $100,000 traditional IRA and currently fall into the 10% tax bracket. Converting that balance today would trigger a $10,000 tax bill.

Now picture that same IRA ten years later—worth $200,000 when you’re 60 years old and in a 20% tax bracket. If you withdraw in retirement instead of converting earlier, you’d owe $40,000 in taxes. In this example, converting at the lower rate would clearly have been the smarter move.

When Converting Wins: Lower Rate Today
Convert at 50 Withdraw at 60
IRA value $100,000 $200,000
Tax bracket 10% 20%
Tax owed $10,000 $40,000
Simplified illustration. Converting early saves $30,000 in this example.

However, the reality for many investors is the opposite. Most people are in a higher tax bracket during their working years than they will be in retirement. Because of this, Roth conversions can easily become more expensive than beneficial. That’s why it’s essential to evaluate your current versus future tax brackets before deciding if a conversion truly makes sense.

Scenario #1: You’re in a Higher Tax Bracket Today Than You Will Be Later

Let’s look at a common scenario where a Roth conversion can actually backfire. This happens when you’re in a higher tax bracket today than you’ll be later in retirement.

Imagine you’re 55 years old, earning $250,000 per year, and in the 32% tax bracket. If you convert a $100,000 traditional IRA to a Roth right now, you’ll owe $32,000 in taxes immediately.

Now suppose you don’t convert. You let the account grow for 10 years, and by age 65, it has doubled to $200,000. At that point, your retirement income is around $100,000, placing you in a 12% tax bracket. When you begin taking withdrawals, you’ll pay $24,000 in taxes (12% of $200,000), which is far less than the $32,000 you would have paid in your high-earning years.

Convert at 55 vs. Withdraw at 65
Convert now (age 55) Wait and withdraw (age 65)
IRA value $100,000 $200,000
Tax bracket 32% 12%
Tax owed $32,000 $24,000
Waiting saves $8,000 in tax here, even though the account is twice as large.

This is a very typical scenario for people in their peak earning years who consider converting while their tax bracket is highest. Ten years later, when they’re retired and earning less, their tax rate is lower, making the earlier conversion costlier than necessary.

Key takeaway: A Roth conversion typically isn’t advisable when your expected retirement tax rate will be lower than what you pay today. There are exceptions, such as when you expect only a modest drop, for example 32% to 22%. If the difference is substantial, like 32% down to 12%, converting could be a mistake. Always run the numbers and compare what your tax burden would be today versus in retirement before making the decision.

Scenario #2: You Don’t Have Enough Income or Assets for It to Matter

This scenario doesn’t get discussed nearly enough, but for many middle-income households, a Roth conversion often doesn’t move the needle at all.

Consider this example: you retire with a $150,000 traditional IRA and have about $40,000–$60,000 in annual retirement income. In this situation, you may owe little to no income tax when taking IRA distributions. In effect, your traditional IRA can behave much like a Roth, thanks to the deductions available to seniors.

For instance, once you’re 65 or older, you can claim the standard deduction of $32,200, the additional senior deduction of $3,300, and potentially the new senior deduction from the One Big Beautiful Bill of $12,000 (for married couples filing jointly). That’s roughly $47,500 in total deductions. This means your first $47,500 of retirement income is tax-free, and income above that is taxed at only about 10–12%.

2026 Deductions: Married Couple, Both 65+, Filing Jointly
Deduction Amount
Standard deduction $32,200
Additional standard deduction for age 65+ ($1,650 × 2) $3,300
New senior deduction (One Big Beautiful Bill, 2025–2028)* $12,000
Total deductions $47,500
*The $6,000-per-person senior deduction phases out once modified adjusted gross income exceeds $150,000 for joint filers.

For someone with $150,000 in income, after deductions you’d be taxed on roughly $102,500, resulting in no more than about $12,000 in federal tax. With taxes this low in retirement, converting to a Roth doesn’t provide much benefit because your traditional IRA withdrawals are already taxed lightly.

When your projected retirement income keeps you in a relatively low tax bracket and when generous standard and senior deductions apply, the traditional IRA can already deliver near tax-free outcomes. In these situations, pre-paying taxes through a Roth conversion offers little advantage. Doing nothing, leaving funds in your traditional IRA and taking distributions strategically, often proves the more tax-efficient and financially prudent approach.

Scenario #3: The Conversion Triggers Hidden Costs (IRMAA, Phaseouts)

Another situation where a Roth conversion can work against you is when you are in your 60s and the conversion triggers hidden costs that you might not be considering. Roth conversions do not only affect your tax bill, although that is often the main focus. They can also influence several other parts of your financial picture.

When you convert to a Roth IRA, the amount converted is treated as taxable income. For individuals in their 60s, that income increase can have several ripple effects. One of the biggest concerns is the Medicare Income-Related Monthly Adjustment Amount, or IRMAA. IRMAA is an additional charge added to your Medicare Part B and Part D premiums if your income exceeds certain thresholds. For 2026, this applies when income is above roughly $109,000 for single filers or $218,000 for married couples filing jointly.

Crossing those limits can raise your Medicare premiums by roughly $96 to $578 per month per person, depending on how far over the line you go—that’s anywhere from about $1,100 to nearly $7,000 per year for each spouse on Medicare. A higher reported income can also cause you to lose certain deductions or credits that phase out at higher income levels, and it can increase the taxable portion of your Social Security benefits.

2026 Medicare IRMAA Surcharges (Based on 2024 Income)
Single filer income Joint filer income Added cost per person / month
$109,000 or less $218,000 or less $0
$109,001 – $137,000 $218,001 – $274,000 $95.70
$137,001 – $171,000 $274,001 – $342,000 $240.40
$171,001 – $205,000 $342,001 – $410,000 $385.00
$205,001 – $499,999 $410,001 – $749,999 $529.60
$500,000 or more $750,000 or more $578.00
Combined Part B and Part D surcharge on top of standard premiums; income is modified adjusted gross income. Source: SSA/CMS 2026 figures.

This issue is especially important for people around age 63 and older. Medicare uses a two-year lookback when determining IRMAA surcharges. That means conversions done at age 63 could affect your Medicare costs when you turn 65.

Key takeaway: If you are approaching Medicare eligibility, consider the potential IRMAA surcharges and their long-term impact as part of your Roth conversion analysis.

Scenario #4: You’re Paying the Taxes from the IRA Itself

The next scenario where a Roth conversion does not make sense is when you plan to pay the taxes for the conversion using money from the IRA itself. This is a major mistake and, in my view, a dealbreaker in every situation.

When doing a Roth conversion, you should always pay the taxes with money from outside the IRA. That way, the full amount of the conversion ends up in the Roth as after-tax dollars that can grow and eventually come out tax-free.

If you do not have outside cash to cover the tax bill, some people make the costly mistake of taking a distribution from their traditional IRA to pay the taxes. This approach creates two problems. First, you will owe income tax on the withdrawal. Second, if you are under age 59½, you will also face a 10% early withdrawal penalty. Both of these reduce the amount that stays invested and growing in the Roth IRA.

For example, say you convert $100,000 while in the 25% tax bracket. You take out $25,000 from the IRA to pay the tax. You will owe another 10% penalty on that $25,000, bringing your total cost to $27,500 in taxes and penalties. That leaves only $75,000 invested in the Roth—and you still have to cover the $2,500 penalty on top of that—which greatly reduces the long-term benefit of the conversion.

Paying the Conversion Tax: Outside Cash vs. the IRA
$100,000 conversion, 25% rate, under 59½ Pay with outside cash Pay from the IRA
Amount that reaches the Roth $100,000 $75,000
Income tax $25,000 $25,000
10% early withdrawal penalty $0 $2,500
Total tax and penalty $25,000 $27,500

If you are in a situation where paying the taxes requires taking money from the IRA itself, it is usually best to pause and reconsider. In nearly every case, a conversion under these circumstances will hurt more than it helps.

Scenario #5: You Plan to Leave the Account to Lower-Tax-Bracket Heirs

A Roth conversion may not make sense when you plan to leave the account to heirs who are in a lower tax bracket. This is where estate planning starts to overlap with your tax and retirement strategy.

If you are in a 24%, 32%, or higher tax bracket, but your children or heirs are only in a 12% or 22% bracket, you may be prepaying taxes at a higher rate than they would pay later. For example, if you convert a $200,000 traditional IRA to a Roth IRA and you are in the 32% bracket, that conversion would cost $64,000 in taxes. If your child later inherits a traditional IRA and withdraws the money while in the 22% bracket, they would pay $44,000 in taxes instead. That is a $20,000 difference, which means the conversion may not be the most efficient move.

Who Pays the Tax on a $200,000 IRA?
You convert now Your heir withdraws later
Tax bracket 32% 22%
Tax owed $64,000 $44,000
Leaving the account as a traditional IRA saves $20,000 in this example.

In some cases, it can actually be better to leave the account as a traditional IRA.

The analysis changes, though, if you are in lower income years in retirement and plan to leave the account to children who are still in their peak earning years. If you are paying 10% to 20% today while your heirs are paying 30% or more, converting to a Roth IRA may make more sense. In that case, you are paying the tax upfront at a lower rate so your heirs can inherit a tax-free asset that can continue to grow.

The facts matter here. Whether it makes sense to convert now or leave the account as-is depends on your tax rate, your heirs’ tax rate, and how the IRA fits into your broader estate plan.

Scenario #6: Your Traditional IRA Is Your Account of Last Resort

The next scenario where a Roth conversion does not make sense is when your traditional IRA is really your account of last resort. In other words, you do not expect to rely on it for retirement income in your 60s or 70s, and you may eventually use it for qualified charitable distributions to causes you care about.

For many people, the traditional IRA is simply the last bucket of money they expect to spend. If that is your situation, and you have other assets or income sources to live on first, converting to Roth may not provide much benefit. By the time you reach your later retirement years, your taxable income may be low enough that withdrawals from the traditional IRA result in little to no tax anyway.

That is why this scenario often comes down to timing and intent. If your plan is to leave the IRA untouched for years and then use it later when your income is lowest, the tax cost of converting today may be higher than the tax cost of leaving it alone. In many cases, the traditional IRA can remain the more efficient choice.

Scenario #7: You Don’t Have a “Gap Year” Window

Another reason a Roth conversion may not make sense is if you do not have a gap year window. One of the best times to convert is during a year when your income is temporarily lower, such as after you stop working but before Social Security or RMDs begin. Those years can create a valuable opportunity to convert at a lower tax rate, sometimes with little or no tax at all.

However, not everyone has that window. You may keep working into your 70s and stay in a high tax bracket, or you may simply never have a year where your income drops enough to make a conversion attractive. In those cases, the clear-cut opportunity to convert at a low tax cost may never appear.

That is why timing matters so much. If you do not have a gap year or another low-income year to work with, a Roth conversion may not deliver the same benefit it would for someone who does.

Scenario #8: State Taxes Work Against You

Finally, the last scenario where a Roth conversion may not make sense is when state taxes work against you. For example, if you live in New York when you do the conversion but plan to retire in Florida and take withdrawals there, state taxes can change the entire equation.

If you are in a high-tax state today, say 8% to 10%, a Roth conversion may look much more expensive than it will later in retirement. For instance, if you are paying 30% in federal taxes and 10% in state taxes today, your total tax cost is 40%. But if you retire in Florida and your future withdrawals are taxed at only 25% federally with no state income tax, then leaving the money in a traditional IRA could actually be the better move.

Convert in New York vs. Withdraw in Florida
Convert today (New York) Withdraw later (Florida)
Federal tax rate 30% 25%
State tax rate 10% 0%
Total tax rate 40% 25%

In that case, you would be paying 40% today to convert to Roth instead of paying 25% later on traditional withdrawals. That is a much bigger tax bill upfront, so the conversion does not make sense. Always factor in where you live now versus where you expect to live in retirement, because state taxes can significantly change the outcome.

The Big Picture: Why It Always Depends

Now that we have covered the 8 scenarios where a Roth conversion may not make sense, it is worth stepping back to look at the bigger picture. Whether a Roth conversion is the right move is always situational.

It depends on your current income, your expected future income, the amount you want to convert, your tax bracket today versus later in retirement, the state you live in now versus the state you may live in later, and your long-term legacy goals. Are you planning to spend down this account in retirement, or are you trying to preserve it for children or other heirs?

One of the biggest mistakes people make is converting without running the numbers first. Roth accounts are powerful, but they are not always the right tool. A traditional IRA to Roth IRA conversion only makes sense when the math supports it. Do not leave your decision to guesswork; crunch the numbers specific to your situation first.

If you would like help determining whether a Roth conversion makes sense in your situation or building a more tax-efficient retirement strategy, my team at KKOS Lawyers works with investors and business owners across the country. You can book a free call using the link below, and we will help you map out the smartest approach based on your numbers.

FREE STRATEGY CALL

Find out whether a Roth conversion actually makes sense for your numbers.
Contact Us – KKOS Lawyers

Solo 401(k) vs SEP IRA — Same Income, Twice the Contribution

Same business, same $100,000 income, wildly different retirement outcomes: one owner saves $25,000 in a SEP IRA, the other $49,500 in a Solo 401(k)—nearly double, with nothing changed but the account type. The difference isn’t performance; it’s plan design. The Solo 401(k) is engineered for today’s self-employed, while the SEP IRA remains a 1978-era solution with modern limitations. For self-employed professionals running their business through an S corporation—as most profitable ones should—the contribution gap between a Solo 401(k) and a SEP IRA widens even further.

The real question isn’t “Which account is better?” but “Which account is better for me, given my income, age, entity type, and contribution rules?” The answer is arithmetic, not which form is simpler. In this article, we’ll break down three reasons the Solo 401(k) wins for most business owners, plus the one common scenario where a SEP IRA still makes sense. We’ll also show what $50,000 a year can grow into in each account—and why, despite sharing a $72,000 annual cap, the Solo 401(k) reaches it with nearly $100,000 less in W-2 compensation.

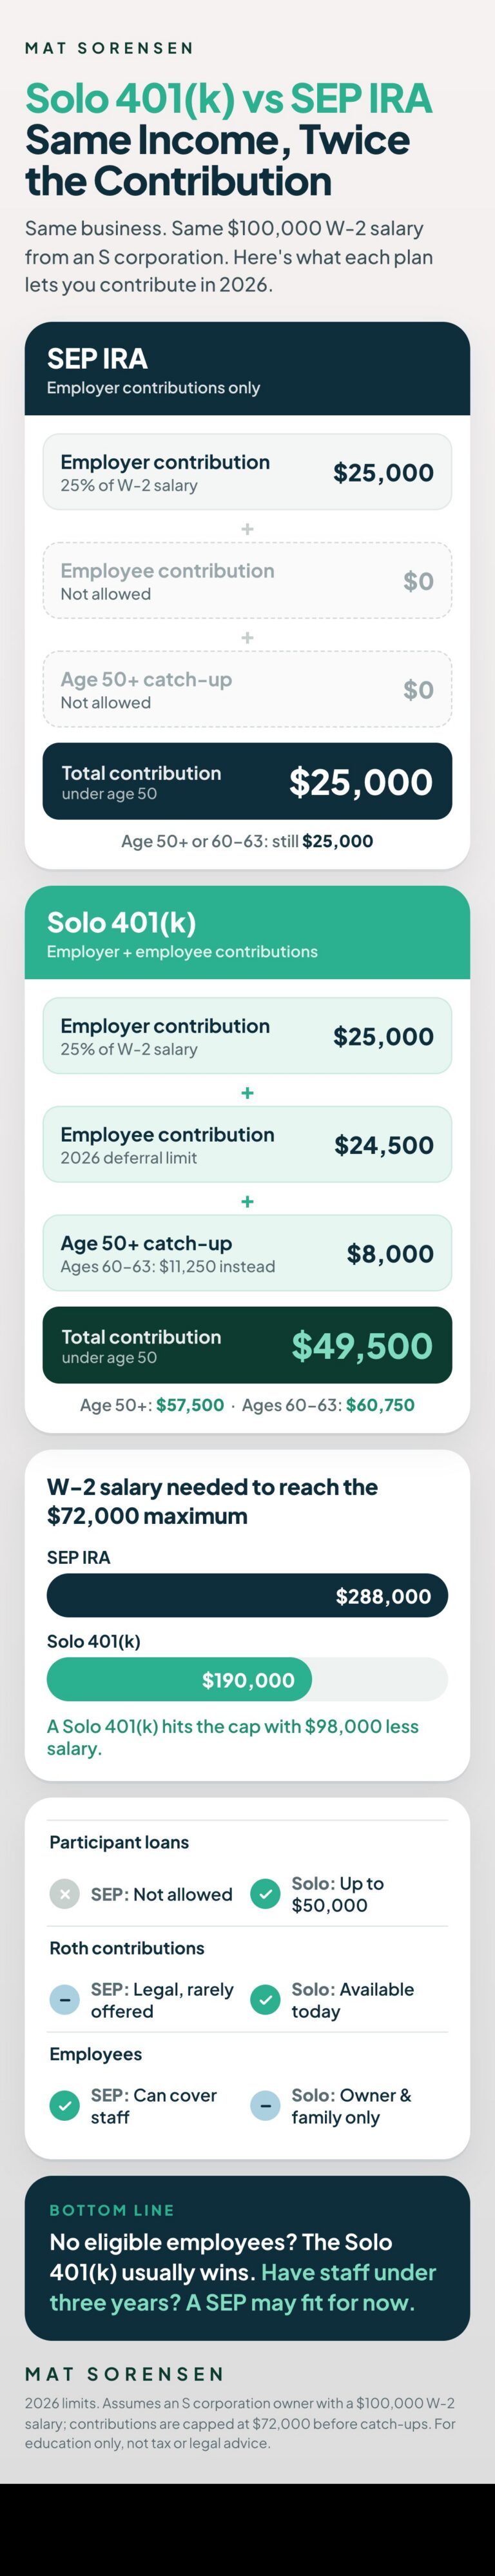
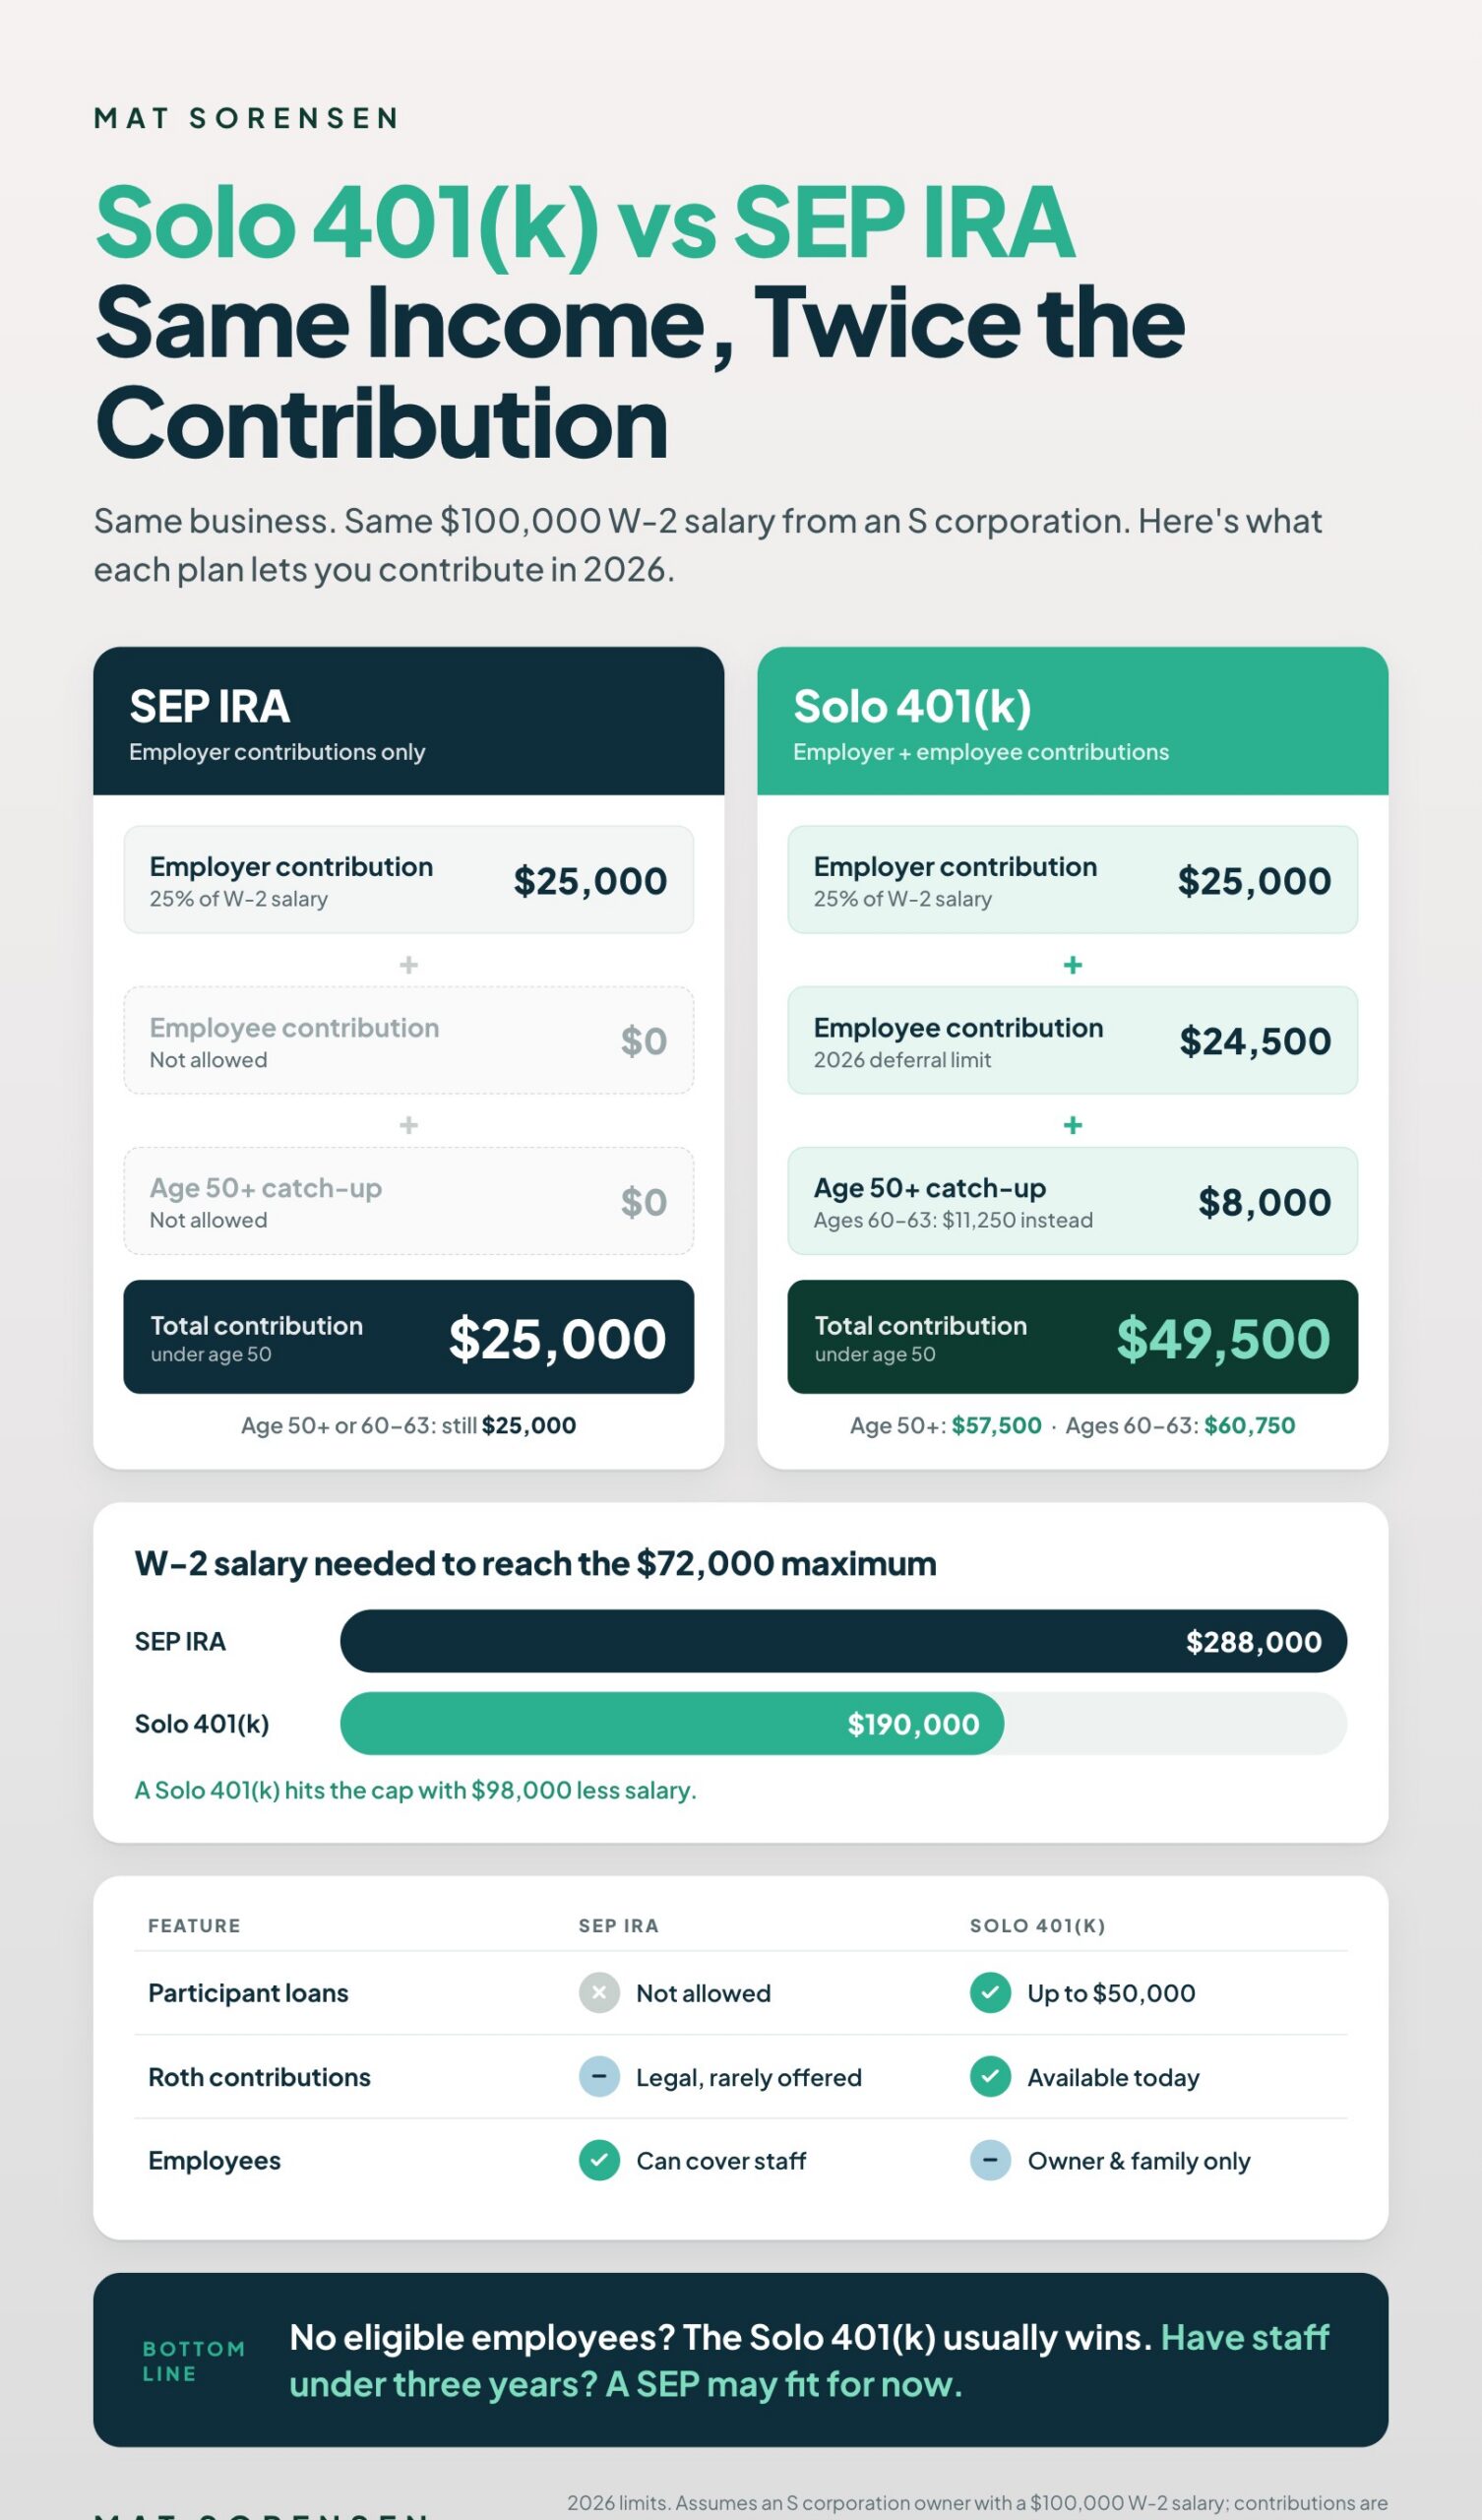
Infographic: Solo 401(k) vs SEP IRA on the same $100,000 W-2 salary

Why the Solo 401(k) Wins: You Can Contribute More on Less Income

The Solo 401(k) lets you contribute significantly more than a SEP IRA at the same income level—thanks to its dual-contribution structure.

Both plans share a $72,000 annual limit (2026), but the paths to that cap differ sharply:

  • SEP IRA: Only employer contributions are allowed—capped at 25% of W-2 wages for an S corporation owner, or roughly 20% of net self-employment earnings for a sole proprietor.
  • Solo 401(k): An employer contribution (25% of W-2) plus an employee contribution of up to $24,500 in 2026, with catch-up contributions on top for owners 50 and older.
2026 Contributions on the Same W-2 Salary
SEP IRA Solo 401(k)
$100,000 W-2 $25,000 $49,500
$100,000 W-2, age 50+ $25,000 $57,500
$100,000 W-2, ages 60–63 $25,000 $60,750
$200,000 W-2 $50,000 $72,000 (max)
Solo 401(k) = 25% employer contribution + $24,500 employee deferral, capped at $72,000. Catch-ups ($8,000 at 50+, or $11,250 at ages 60–63) are added on top of the cap.

S corporation owners benefit most. Since contributions are based solely on W-2 wages (not K-1 distributions), minimizing W-2 to save on payroll taxes severely limits SEP IRA contributions—but barely dents Solo 401(k) capacity.

Example: $200K Total Income ($80K W-2 + $120K K-1)
SEP IRA Solo 401(k)
Employer contribution (25% × $80,000) $20,000 $20,000
Employee contribution Not allowed $24,500
Total contribution $20,000 $44,500
The Solo 401(k) allows more than double the contribution on the same salary.
W-2 Salary Needed to Reach the $72,000 Maximum
SEP IRA Solo 401(k)
How the math works $72,000 ÷ 25% ($72,000 − $24,500) ÷ 25%
W-2 salary required ~$288,000 ~$190,000

Both the SEP IRA and Solo 401(k) top out at $72,000—but you reach that limit far sooner, and with significantly less income, using a Solo 401(k).

The $50,000 Escape Hatch (Participant Loan)

The Solo 401(k) has a major advantage over the SEP IRA: it can allow participant loans. In practical terms, you may borrow from your own account—up to $50,000—without triggering income tax or an early-withdrawal penalty. SEP IRAs do not offer this flexibility. Borrowing from a SEP IRA is prohibited and can create serious tax consequences.

A Solo 401(k) loan can provide liquidity when you need it most. You can use the proceeds to pay off high-interest debt, cover medical expenses, help fund a child’s education, make a home down payment, start a business, or meet another personal need. No hardship exception or special purpose is required.

The maximum loan is the lesser of $50,000 or 50% of your vested Solo 401(k) balance. For example, if your account balance is $60,000, the maximum available loan is $30,000—not $50,000. The loan must generally be repaid within five years, with payments made at a reasonable interest rate—often prime plus 2%. If prime is 5.25%, for example, the loan rate would be 7.25%. That interest is paid back into your own retirement account.

Solo 401(k) Loan at a Glance
Example
Maximum loan Lesser of $50,000 or 50% of your vested balance
$60,000 account balance Up to $30,000
$100,000+ account balance Up to $50,000
Repayment term Generally within 5 years
Interest rate Often prime + 2%, paid back into your own account

This structure gives business owners an important safety valve: you can maximize retirement contributions while retaining access to capital if an unexpected need arises. With a SEP IRA, accessing funds before age 59½ generally means a taxable distribution and potentially a 10% early-withdrawal penalty. A properly administered Solo 401(k) loan avoids both.

Additionally, a Solo 401(k) can also be self-directed, giving you the ability to invest beyond the standard menu of mutual funds and index funds. Depending on plan documents and applicable rules, it may hold assets such as rental real estate, private funds, private companies, and cryptocurrency—investments you understand and believe in.

FREE BEGINNER’S GUIDE

Get a step-by-step overview of Solo 401(k) contribution rules, setup, deadlines, loans, and self-directed investing.

Get the Free Solo 401(k) Beginner’s Guide

The Roth Option

The third major advantage of a Solo 401(k) is Roth capability. If your plan document permits it, you can make Roth Solo 401(k) contributions today, pay tax on the money now, and potentially withdraw the contributions and decades of investment growth tax-free in retirement.

A SEP IRA is a different story. In legislation known as SECURE 2.0, Congress made Roth SEP contributions legal, and the IRS now recognizes that SEP contributions may be made to Roth SEP IRAs. But availability remains limited in practice because the IRS has yet to release updated model form documents for Roth SEP IRAs. Many custodians, including Directed IRA, are waiting for those model documents before establishing customers’ Roth SEP IRAs.

Roth contributions do not produce an upfront tax deduction. You pay tax on the income before contributing it to the Roth Solo 401(k). In exchange, qualified distributions in retirement, generally after age 59½, can be entirely tax-free.

That trade-off can be compelling for investors who expect their tax rate to be higher later, value certainty around future taxes, or are focused on long-term compounding. Rather than taking a deduction today and paying taxes when funds come out, you pay tax once on the contribution and allow the account to grow without another tax bill at retirement.

Key takeaway: For Roth-focused savers, this feature alone can make the Solo 401(k) the more practical choice. A Roth SEP may be authorized by law, but a Roth Solo 401(k) is generally the account you can actually establish and use today.

Two More Advantages for Self-Directed Investors

You can be your own trustee. Every IRA, including a SEP IRA, must have a third-party custodian such as a bank, credit union, or trust company. With a Solo 401(k), you can serve as the trustee yourself and control the plan’s bank and brokerage accounts directly. That checkbook control is valuable when you invest in real estate, notes, or private companies, because you can sign off on investments without waiting on a third party to process your own funds.

No UDFI tax on leveraged real estate. When a SEP IRA buys real estate with a loan, it owes a tax on unrelated debt-financed income (UDFI). For example, if your SEP IRA buys a $100,000 rental with $40,000 of its own cash and a $60,000 loan, the IRS taxes roughly 60% of the property’s net income, and the IRA has to file a separate Form 990-T. Congress created an exemption for Solo 401(k)s, so this tax on leveraged real estate doesn’t apply to them. If you plan to use debt in your deals, the Solo 401(k) is the better fit.

The trade-offs. A Solo 401(k) requires an IRS-compliant plan document, so it costs more to set up than a SEP IRA. And once the plan holds more than $250,000 in assets, you’ll need to file Form 5500-EZ with the IRS each year. The return isn’t overly complex, but it’s an annual filing you’ll need to handle or hire out.

The One Exception: When the SEP Actually Wins

There is one common situation where a SEP IRA may be more practical than a Solo 401(k): you have employees.

A Solo 401(k)—also known as a one-participant 401(k)—is designed for a business owner with no eligible non-owner employees. It can generally cover the owner, the owner’s spouse, and children who work in the business; each may participate under the plan’s eligibility rules and have their own Solo 401(k) account within the same plan. However, once you have an eligible non-owner full-time employee who has worked for you for more than one year, the business is no longer a straightforward fit for a Solo 401(k).

SECURE 2.0 adds another consideration: certain long-term, part-time employees must be allowed to make elective deferrals after working at least 500 hours in two consecutive 12-month periods, subject to the applicable age and plan rules. That means part-time help can create 401(k) eligibility issues sooner than many owners expect.

The Solo 401(k) is meant for the business owner, their spouse, and their family. It is not intended for a company that has other full-time or part-time employees.

A SEP IRA offers more runway. Under the maximum permitted eligibility requirements, employees generally must be included only after they have:

  • 1Reached age 21
  • 2Worked for the business in at least three of the prior five years
  • 3Earned at least the applicable minimum compensation for the year

Importantly, a “year of service” can count even if the employee worked only briefly. A seasonal employee who works one summer can still accumulate one of the three required years.

EXAMPLE: THE SEP WINDOW

Suppose you are a real estate agent who hires a full-time assistant. After two years, a Solo 401(k) is no longer the straightforward solution because you have a non-owner employee. But that employee may not yet be eligible for a SEP IRA under the three-out-of-five-years rule.

That creates a useful planning window: you can establish a SEP IRA, make your annual employer contribution, and delay the point at which you must also fund contributions for the employee. Once the employee satisfies the SEP’s eligibility requirements, however, the business must generally make the same percentage contribution for that employee as it makes for the owner.

The practical takeaway: If you have no eligible employees—only independent contractors paid on Form 1099—a Solo 401(k) is usually the stronger choice. If you have employees and are in the gap between one and three years of service, a SEP IRA can be the better short-term retirement-plan option.

What That $50,000 a Year Actually Becomes

The contribution gap between a SEP IRA and a Solo 401(k) may look like a $24,500 annual difference. Over time, it can become a multimillion-dollar decision.

Assume you contribute $50,000 per year to a Solo 401(k) and earn a hypothetical 10% annual return. That is roughly in line with the S&P 500’s long-term historical average, though actual returns vary and are never guaranteed.

$50,000 a Year at a Hypothetical 10% Return
After 10 years~$800,000
After 20 years~$2.9 million
After 30 years~$8.2 million
Illustration only. Assumes $50,000 contributed at the end of each year, a constant 10% annual return, and no fees, taxes, or changes in contribution limits. Investment returns are not guaranteed, and the S&P 500’s historical performance does not predict future results.

If those contributions go into a Roth Solo 401(k), qualified distributions in retirement can be entirely tax-free. That means the value shown after 10, 20, or 30 years is not merely an account balance—it can be tax-free retirement income.

This is why the account decision matters. A Solo 401(k) does not simply give you more room to contribute this year; it gives more capital time to compound. For an owner able to put away $50,000 annually—even on a $100,000 W-2—the difference between a SEP IRA and a Solo 401(k) can grow from thousands of dollars today to millions of dollars by retirement.

What This All Comes Down To

The SEP IRA was built for an earlier era of self-employment. For most business owners with no eligible employees, the Solo 401(k) is the more powerful modern tool: it lets you contribute more on less income, access liquidity through a participant loan when needed, and use a practical Roth option to build tax-free retirement wealth.

The advantage is not subtle. A Solo 401(k) combines higher contribution capacity, greater flexibility, and Roth planning in one account. Yet many business owners never compare the numbers—they simply open whichever account their bank or broker makes easiest to access. That can mean leaving substantial retirement savings and tax-planning opportunities on the table.

Ready to explore a Solo 401(k) or self-directed IRA? My team at Directed IRA administers thousands of self-directed retirement accounts and can help you evaluate your options. Book a complimentary 15-minute call to get started and discuss which options may be best for you.

FREE 15-MINUTE CALL

Find out whether a Solo 401(k) or SEP IRA fits your income, entity, and employees.

Book a Call with Directed IRA

The Roth IRA 5-Year Rule Everyone Gets Wrong (It’s Actually Two Clocks)

Your Roth IRA is only tax-free if you satisfy two separate five-year rules—each running on its own clock. Get either one wrong, and what you thought was a tax-free withdrawal can land on your 1040 as ordinary income, plus potential penalties.

These rules affect more investors than you might expect: anyone with multiple Roth IRAs, anyone who has changed custodians, backdoor Roth contributors, savers executing gap-year conversion strategies before retirement, and those who opened their first Roth IRA later in life and assumed age 59½ made everything automatically tax-free.

The key question is simple but critical: which clock applies to which dollars? Every Roth IRA can hold three types of money: contributions, conversions, and earnings. The two five-year rules treat each type differently. Some funds are immediately accessible, some unlock on a schedule, and some remain conditional until a specific date.

The short version:

RULE 1

The Account Clock

You must have a Roth IRA open for five years before earnings can be withdrawn tax-free. This clock starts on January 1 of the tax year of your first Roth contribution (or conversion, if earlier) and applies collectively to all your Roth IRAs. It never resets when you switch custodians or open additional Roth accounts.

RULE 2

The Conversion Clock

Each Roth conversion has its own five-year clock. This rule does not affect whether the conversion itself is taxed—you already paid that—but it can shield you from the 10% early-withdrawal penalty if you take converted funds out before age 59½.

The costly mistake: Most costly mistakes come from applying the right rule to the wrong dollars. Misstep on $50,000 of earnings, and you could hand the IRS $12,000 in taxes on growth that should have been yours, tax-free, forever.

Clock #1 — The Account Clock (This One Applies to Everyone)

For your Roth IRA earnings to come out completely tax-free, you must satisfy two conditions:

  • 1Be at least age 59½ (or meet another qualifying exception), and
  • 2Have satisfied the Roth IRA five-year rule

The five-year clock starts on January 1 of the tax year in which you made your first Roth IRA contribution—whether that contribution was to a traditional Roth IRA or a Roth conversion IRA. Once that clock starts, it applies to all your Roth IRAs and never resets.

If you make a Roth contribution in April 2027 but designate it for the 2026 tax year, the five-year clock is treated as starting on January 1, 2026. In that case, you reach the five-year mark in under four calendar years.

A common misconception is that each Roth IRA has its own five-year timer. It doesn’t. You get one lifetime clock tied to your first Roth contribution. Switching custodians, rolling assets, or opening additional Roth IRAs does not restart the five-year period; the clock follows you.

EXAMPLE: SWITCHING CUSTODIANS

You opened a Roth IRA at Fidelity, held it for three years, then transferred everything to Directed IRA and bought real estate inside the Roth IRA. Your clock kept running. You now have six years on the same clock.

EXAMPLE: OPENING YOUR FIRST ROTH IRA LATE IN LIFE

You open your first Roth IRA at 58 and want to withdraw at 60. At 60, you’re past the 59½ threshold, so the 10% early-withdrawal penalty no longer applies—but earnings remain taxable until the five-year rule is satisfied. In this scenario, contributions can be withdrawn tax- and penalty-free at 60, but any earnings taken before age 63 are taxable. Once the five-year clock is met at 63, qualified distributions—including earnings—become entirely tax-free.

Age 58

First Roth IRA opened. The account clock starts.

Age 59½

The 10% penalty no longer applies, but earnings are still taxable.

Age 63

Five-year clock met. Earnings come out tax-free.

Age 59½ eliminates the penalty, not the tax on earnings. Tax-free treatment on earnings requires both (1) being at least 59½ (or meeting another qualifying condition) and (2) satisfying the five-year account clock. Once any Roth IRA has been open for five years—counting transfers and custodian changes—earnings can be withdrawn tax-free as soon as the age or other qualifying condition is met.

FREE SELF-DIRECTED IRA GUIDE

Learn how a self-directed Roth IRA can invest in real estate, private funds, and other alternative assets you actually understand.

Get the Free Self-Directed IRA Guide

Clock #2 — The Conversion Clock (Situational, and the One People Mess Up)

Every Roth conversion carries its own five-year clock, starting January 1 of the conversion year. This rule exists to prevent investors from using conversions as a loophole to sidestep the 10% early-withdrawal penalty. You pay income tax on the conversion in the year it occurs, but that does not automatically make the converted funds penalty-free if withdrawn immediately.

The rule is narrow but important: if you withdraw converted Roth dollars within five years and you’re under 59½, the IRS imposes a 10% early-withdrawal penalty on the amount taken. Wait out the full five years, and those converted dollars behave like regular Roth contributions which are withdrawable at any age, tax- and penalty-free. Earnings, however, remain subject to Rule 1 (the account clock) and the age 59½ requirement.

EXAMPLE: EARLY ACCESS AFTER CONVERSION

At 45, you have $100,000 in a Roth IRA and $100,000 in a traditional IRA. You convert the entire traditional IRA to Roth, pay the tax in 2026, and let the account grow. By age 51, the five-year conversion clock has run its course, and the converted funds have grown to $150,000. You can withdraw the $100,000 of converted principal tax- and penalty-free at 51. The $50,000 of earnings, however, remains off-limits without tax and penalty until you satisfy Rule 1 and reach 59½. Withdrawing earnings early could trigger both income tax and a 10% penalty—potentially costing $17,000 on a $50,000 distribution.

$100,000

Converted principal: tax- and penalty-free at 51

$50,000

Earnings: taking them early could cost about $17,000 in tax and penalty

EXAMPLE: BACKDOOR ROTH AND MULTIPLE CLOCKS

For backdoor Roth IRA users, each annual conversion starts its own five-year timer. If you’re 50 and contribute $7,500 annually to a non-deductible traditional IRA, then convert to Roth each year, every conversion has a separate timeline. The 2026 conversion unlocks in 2031, the 2027 conversion in 2032, and so on. After six years of this strategy, you don’t have a single locked Roth balance; you have a rolling conveyor belt of penalty-free principal, with a new tranche becoming available each January 1.

Backdoor Roth: Each Conversion Unlocks on Its Own Date
Year converted Amount Penalty-free from
2026 $7,500 Jan. 1, 2031
2027 $7,500 Jan. 1, 2032
2028 $7,500 Jan. 1, 2033
2029 $7,500 Jan. 1, 2034
2030 $7,500 Jan. 1, 2035
2031 $7,500 Jan. 1, 2036
Assumes $7,500 converted each year. The conversion clock only matters before age 59½; earnings still follow the account clock.

EXAMPLE: THE “SHUTOFF SWITCH” AT 59½

The conversion five-year rule only guards against the 10% early-withdrawal penalty, which disappears at 59½. After that age, the rule no longer matters. A 62-year-old executing a gap-year conversion strategy can convert traditional IRA funds to Roth at 62 and withdraw those converted dollars at 63 without penalty.

However, Rule 1—the account five-year clock—still applies. If this investor opened their first Roth IRA at 60 and has never held one before, earnings cannot be withdrawn tax-free until age 65, when the five-year account requirement is satisfied. Converted principal remains accessible without penalty, but growth and earnings must wait.

For anyone new to Roth IRAs after 59½, the key is to track both clocks: the conversion timers for penalty avoidance before 59½, and the single lifetime account clock for tax-free treatment of earnings.

The Two Roth Clocks at a Glance

CLOCK #1

The Account Clock

HOW MANY

One lifetime clock

STARTS

Jan. 1 of the tax year of your first Roth IRA contribution or conversion

APPLIES TO

All your Roth IRAs

DETERMINES

When earnings can become tax-free

RESETS?

Never, even when you change custodians or open another Roth IRA

THINK

Tax-free earnings

CLOCK #2

The Conversion Clock

HOW MANY

A new clock for each conversion

STARTS

Jan. 1 of the year of each conversion

APPLIES TO

Each conversion separately

DETERMINES

Whether converted dollars can be withdrawn without the 10% early-withdrawal penalty before age 59½

RESETS?

Each conversion starts another clock

THINK

Penalty-free converted principal

The Machinery That Makes This Navigable — Ordering Rules

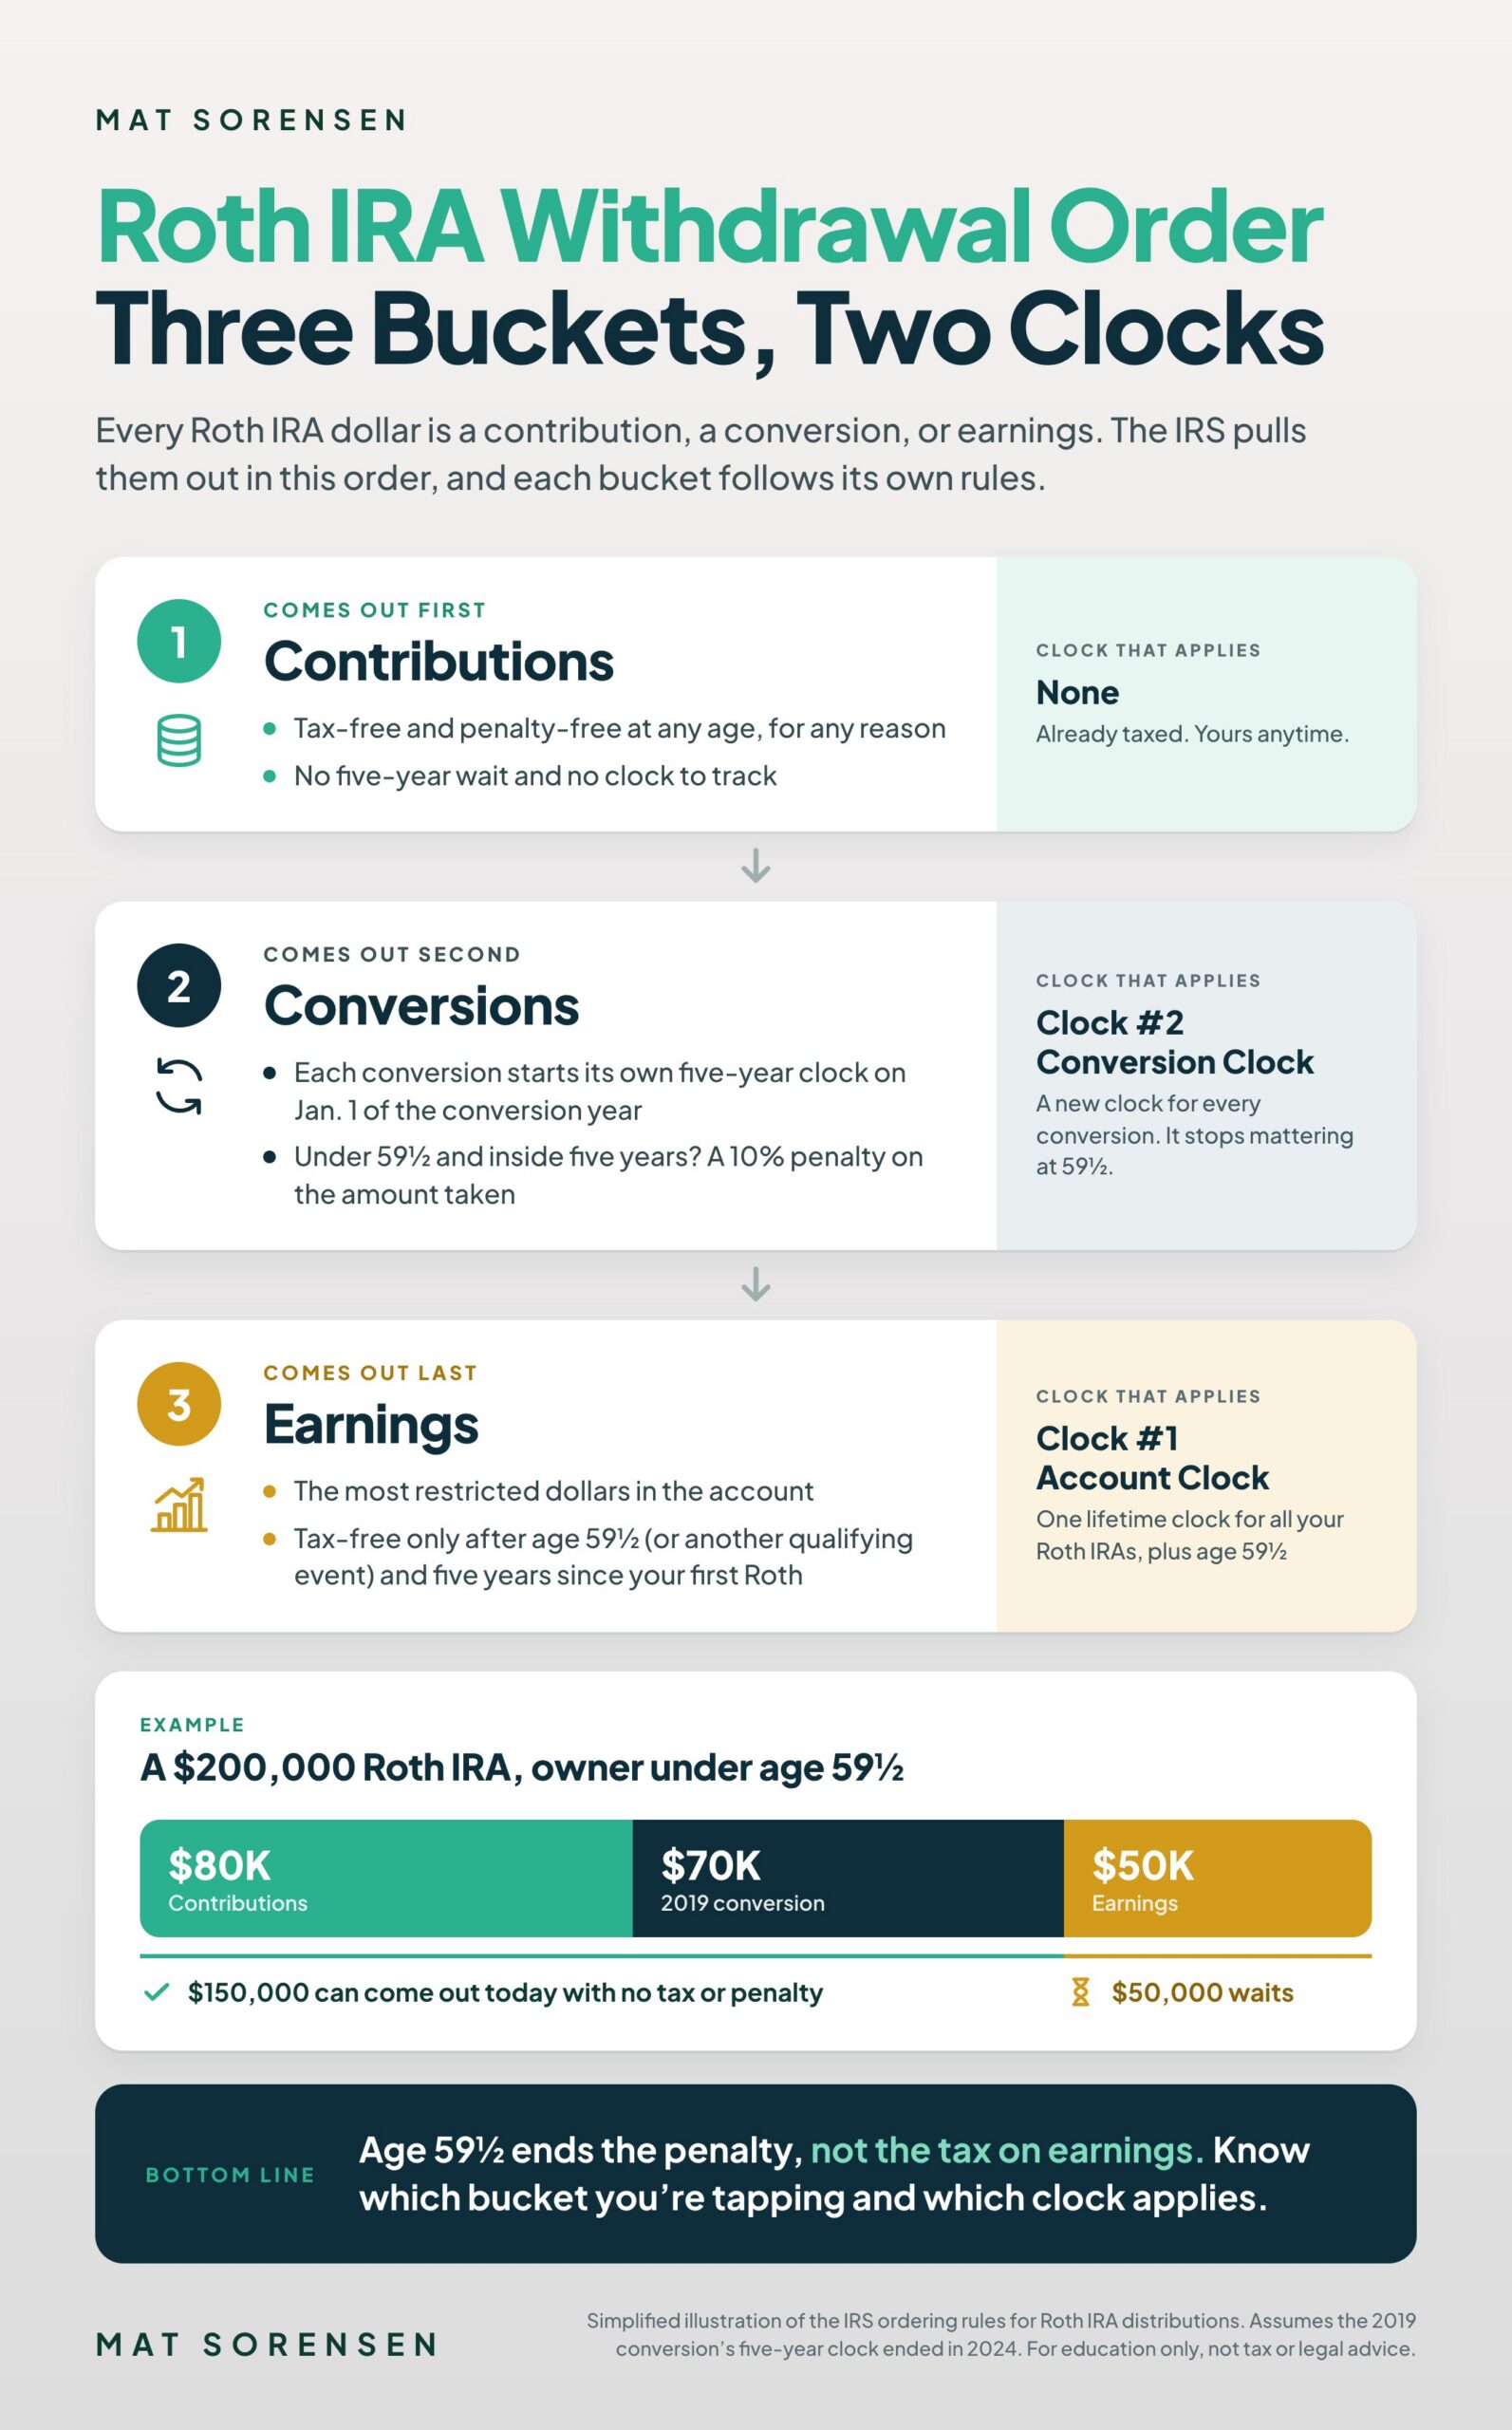
When Congress created Roth IRAs, it built in a powerful safeguard: a strict ordering rule for withdrawals. Every distribution comes out in a specific sequence—contributions first, then conversions, then earnings. This order matters because each bucket carries different tax and penalty treatment. The rules ensure you access the safest dollars first and only reach the most restricted funds last.

The Three Buckets, in Order

1

ALWAYS COME OUT FIRST

Regular Roth Contributions

These are tax- and penalty-free at any age, with no five-year waiting period. If you withdraw at 50, you’re pulling contributions first—no clocks to track, no forms to justify.

2

COME OUT SECOND

Converted Amounts

Each conversion has its own five-year clock (Clock #2). Once that period has passed, the converted principal can be withdrawn tax- and penalty-free, even before age 59½. If the clock hasn’t run, a 10% penalty may apply if you’re under 59½.

3

ALWAYS COME OUT LAST

Earnings and Growth

This is the most restricted bucket. To withdraw earnings tax- and penalty-free, you must satisfy both five-year rules and be at least 59½ (or meet another qualifying condition). The IRS won’t let you touch earnings until contributions and conversions are exhausted.

This ordering is automatic—you don’t choose which dollars come out. The IRS mandates the sequence that minimizes your tax burden. You cannot accidentally withdraw taxable earnings while untaxed contributions or seasoned conversions remain in the account.

EXAMPLE: KNOW WHICH DOLLARS YOU CAN TOUCH

Suppose your Roth IRA holds $200,000:

  • $80,000 in regular contributions
  • $70,000 from a 2019 Roth conversion
  • $50,000 in earnings and growth

You can withdraw $150,000 today with zero tax or penalty, even if you’re under 59½:

  • The $80,000 in contributions is always accessible
  • The $70,000 conversion is seasoned—its five-year clock ended in 2024
  • Only the $50,000 in earnings remains conditional. The IRS requires you to exhaust the $150,000 first before any earnings can be distributed

Your custodian’s statements show your account balance, but not the breakdown by bucket. To track contributions, conversions, and distributions, you’ll use IRS Form 8606, which reports Roth IRA activity—including conversions and distributions—on your federal tax return. This form ensures the IRS knows which dollars you’ve withdrawn and whether any portion is taxable or subject to penalty.

Understanding these three buckets—and the ordering rule that governs them—gives you clarity on what you can access today, what requires waiting, and how to avoid unnecessary taxes and penalties.

Infographic: Roth IRA withdrawal order. Contributions come out first, conversions second, earnings last, and which five-year clock applies to each

When Neither Rule Matters (So You Don’t Overthink It)

Most Roth IRA owners never need to stress over the two five-year clocks. In many common situations, the rules are already satisfied—or simply don’t apply.

You can ignore the clocks if:

  • ✓You’re withdrawing regular Roth contributions (not conversions). These come out first, tax- and penalty-free, at any age, for any reason
  • ✓You’re 59½ or older and have held a Roth IRA for at least five years. Both clocks are effectively dead: the conversion clock only guards the 10% early-withdrawal penalty (which no longer exists after 59½), and the account clock is already met, so earnings are tax-free

If you’re 45 and don’t plan to touch your Roth until 60, these rules are largely trivial. Contribute, invest, and let compounding work. By retirement, both five-year requirements will be long satisfied, and your Roth will function as the tax-free ATM it was designed to be.

Where mistakes happen:

  • !Early withdrawal of converted funds: You convert to Roth, then pull those dollars out before five years have passed while under 59½—triggering a 10% penalty on the amount taken
  • !Late starters: You open your first Roth IRA at 58, assume everything is tax-free at 59½, and withdraw earnings early. In reality, earnings remain taxable until the account itself has existed for five years—meaning tax-free treatment doesn’t begin until age 63 in this scenario

If neither situation describes you, relax. Your Roth IRA’s tax-free growth is intact. Wait until after 59½ and once the five-year account clock is met, and you’ll enjoy the full benefit: tax-free income in retirement, exactly as Congress intended.

What This All Really Comes Down To

Here’s what the 5-year Roth rule really comes down to: it isn’t one rule, and it isn’t simply about waiting five years.

The key is knowing which Roth dollars you’re dealing with. The tax code effectively treats your Roth IRA as three separate buckets: contributions, conversions, and earnings. Those buckets don’t all follow the same rules. Add in two different five-year clocks, and it’s easy to see where the confusion starts.

In fact, the people most likely to make a costly mistake aren’t necessarily those who have never heard of the five-year rule. They’re the people who know about it—but apply the wrong five-year rule to the wrong bucket of money.

That distinction becomes especially important if you have multiple Roth IRAs, have switched custodians, regularly make backdoor Roth contributions, have completed Roth conversions, or opened your first Roth later in life. Before taking money out, make sure you know which bucket the distribution is coming from and which clock—if any—actually applies.

And remember, a Roth IRA doesn’t have to be limited to publicly traded stocks and mutual funds. A self-directed Roth IRA can hold assets such as real estate, private funds, private businesses, cryptocurrency, and more. At Directed IRA, we help investors establish and administer self-directed retirement accounts. If you want to explore whether a self-directed Roth IRA fits your strategy, book a free 15-minute call with our team here.

FREE 15-MINUTE CALL

See whether a self-directed Roth IRA fits your strategy, from real estate to private funds.

Book a Call with Directed IRA

Crypto Tax Strategies in 2026: Pay Less, Keep More

Crypto is back. With Bitcoin and major altcoins up 20–30% in 2026, gains mean taxes—and the IRS is watching. You must report crypto activity on your federal return (Form 1040), answering the digital asset question before you even list your income. The good news: legal, proven strategies can significantly reduce your tax bill. Below are five high-impact strategies you may want to consider.

Infographic: how crypto gains are taxed and five strategies to reduce crypto taxes in 2026

How Crypto Gains and Losses Are Taxed

Every crypto-to-crypto trade (e.g., BTC → XRP), sale, or spend is a taxable event.

  • ✓Held ≤12 months: Short-term capital gain/loss, taxed at ordinary income rates (up to 37%)
  • ✓Held >12 months: Long-term capital gain/loss, taxed at 0%, 15%, or 20% depending on total taxable income

Most investors should seek to avoid short-term capital gains, as they are generally taxed at significantly higher rates than long-term capital gains. The primary exception is when those gains can be offset with short-term capital losses—a strategy we will discuss later.

It is also important to note that most investors will never reach the 20% long-term capital gains bracket. In 2026, the 20% rate generally applies only when taxable income exceeds $613,700 for married couples filing jointly, $545,500 for single filers, or $579,600 for heads of household. See the table below for reference.

Many investors instead fall within the 0% or 15% long-term capital gains brackets, creating valuable opportunities for proactive tax planning.

2026 long-term capital gains tax brackets

The 0% Capital Gains Bracket (2026 Thresholds)

Long-term capital gains tax depends on total taxable income (after deductions). For 2026, the 0% bracket typically extends up to:

  • ✓Married Filing Jointly: $98,900
  • ✓Single: $49,450
  • ✓Head of Household: $66,200

EXAMPLE

Example: A married couple with $120,000 gross income and a $32,200 standard deduction has $87,800 taxable income. They can realize up to ~$11,100 in long-term crypto gains and still pay 0% federal tax on those gains.

Tactical tip: If you’re near a bracket threshold, stage sales across years to stay in the 0% or 15% zone—avoiding a jump to 20%.

Strategy 1: Crypto Tax-Gain Harvesting

Don’t wait for losses to act. Proactively realize gains up to the top of your current bracket (0% or 15%). This reduces future taxable gains when you eventually sell—all while staying in a lower tax tier today.

EXAMPLE

Example: If you’re close to a tax-bracket threshold, consider selling just enough crypto to realize gains while remaining in the lower bracket. This allows you to lock in gains at a lower tax rate today rather than potentially paying a higher rate in the future. If your objective is a long hold, you may repurchase the asset shortly after the sale. 

Best for: Investors in the 0% or 15% long-term brackets who expect higher income (or rates) later.

Strategy 2: Tax-Loss Harvesting (No Wash-Sale Rule for Crypto)

When crypto dips, sell to lock in losses—then immediately rebuy the same asset. Unlike stocks, the wash-sale rule does not apply to crypto under current IRS guidance, so you can maintain market exposure while harvesting losses to offset other gains.

EXAMPLE

Example: Buy BTC at $90K, it drops to $60K. Sell to realize a $30K loss, rebuy at $60K. Use that loss to offset $30K in gains elsewhere, deferring or eliminating tax.

$90K

buy price

$60K

sale and rebuy price

$30K

realized loss

Note: Legislation has been proposed to extend wash-sale rules to crypto, but as of 2026, it remains inapplicable.

Strategy 3: Hold & Trade Crypto in a Roth IRA (or Other Tax-Advantaged Accounts)

A crypto Roth IRA lets you buy, trade, and grow digital assets tax-free—no capital gains, no short-term rates, and qualified withdrawals in retirement are 100% tax-free.

  • ✓Works with BTC, ETH, SOL, XRP, and more (via self-directed IRA custodians, such as Directed IRA)
  • ✓Ideal for long-term believers who won’t need the funds before age 59½ 
  • ✓Additional tax advantage accounts include kids Roth IRA (with earned income), Coverdell ESAs (education), and HSAs (healthcare)—all holding crypto as the underlying asset

Each account offers powerful tools to strengthen your tax-planning strategy. For guidance on tax-advantaged accounts—and help choosing and opening the right one—contact my team at Directed IRA to discuss an option tailored to your goals. 

Note: Contributions require earned income and stay within annual IRA limits ($7,500 in 2026, or $8,600 if 50+)

Strategy 4: Borrow Against Crypto—Don’t Sell

Need liquidity? Take a loan secured by your crypto holdings instead of selling. Debt isn’t taxable income, and you can defer capital gains indefinitely while accessing cash flow.

  • ✓Interest rates have improved as more lenders enter the crypto-collateral space, however, interest rates can still be volatile 
  • ✓The asset’s appreciation should outpace the interest accruing on the loan
  • ✓Risk-aware investors monitor loan-to-value (LTV) ratios to avoid forced liquidations in downturns

Use case: Fund living expenses, real estate, or new investments—without triggering a tax event.

Strategy 5: Charitable Remainder Trust (CRT) for $1M+ Gains

For ultra-high-net-worth investors, a Charitable Remainder Trust offers triple benefits:

  • ✓Immediate charitable deduction on your taxes (e.g., donate $1M in appreciated BTC)
  • ✓Tax-free sale of crypto inside the trust (no capital gains)
  • ✓Lifetime income stream (up to 20 years or life expectancy) paid to you

At your death, any assets remaining in the trust pass to charity rather than directly to your heirs. However, the trust may be structured to purchase a life insurance policy on your life, with the policy proceeds potentially passing to your children on a tax-advantaged basis.

This strategy is highly complex, and this article provides only a simplified overview. For guidance on whether it is appropriate for your situation—and how to structure and implement it to support your estate-planning goals—schedule a consultation with my law firm, KKOS Lawyers.

Best for: Ultra-high-net-worth investors seeking to combine estate planning, lifetime income, charitable giving, and tax-efficient planning for substantial crypto gains.

Quick Recap: 5 Ways to Slash Crypto Taxes in 2026

  1. 1Harvest gains strategically to maximize 0%/15% brackets
  2. 2Harvest losses freely by selling to lock in losses then immediately rebuying the asset
  3. 3Go tax-free with Roth IRAs, HSAs, or Coverdells holding crypto
  4. 4Borrow, don’t sell to access value without triggering gains
  5. 5Use a CRT for seven-figure gains: deduction + tax-free growth + income + legacy planning

Taxes are unavoidable—but overpaying isn’t. 

Download the FREE CRYPTO BEGINNER’S GUIDE and learn how a Roth IRA, traditional IRA, or HSA can buy and sell cryptocurrency tax-free! Buying Crypto in an IRA (Beginner’s Guide) 

Book a free call with my law firm KKOS Lawyers to learn how we can analyze 30 other tax strategies like this to help you pay less in taxes. Meet with Client Advisor 

Put your retirement dollars into the assets you actually believe in — BOOK A FREE CALL with DirectedIRA and set up a crypto Roth IRA today! Book a Call | Self-Directed Account Specialists 

FREE CRYPTO IRA GUIDE

Learn how to buy and hold cryptocurrency in a self-directed IRA.

Get the Free Crypto IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

What Happens If You Don’t Have a Will?

You will die someday, and when that happens, everything you own will go to someone else. If you do not have a will, a court—not your family and not your stated wishes—will decide who receives your property based on your state law. This article walks you step by step through creating a simple, legally valid will. It is not a full estate plan, but if you currently have nothing in place, it is the fastest way to document your wishes so they are followed. 

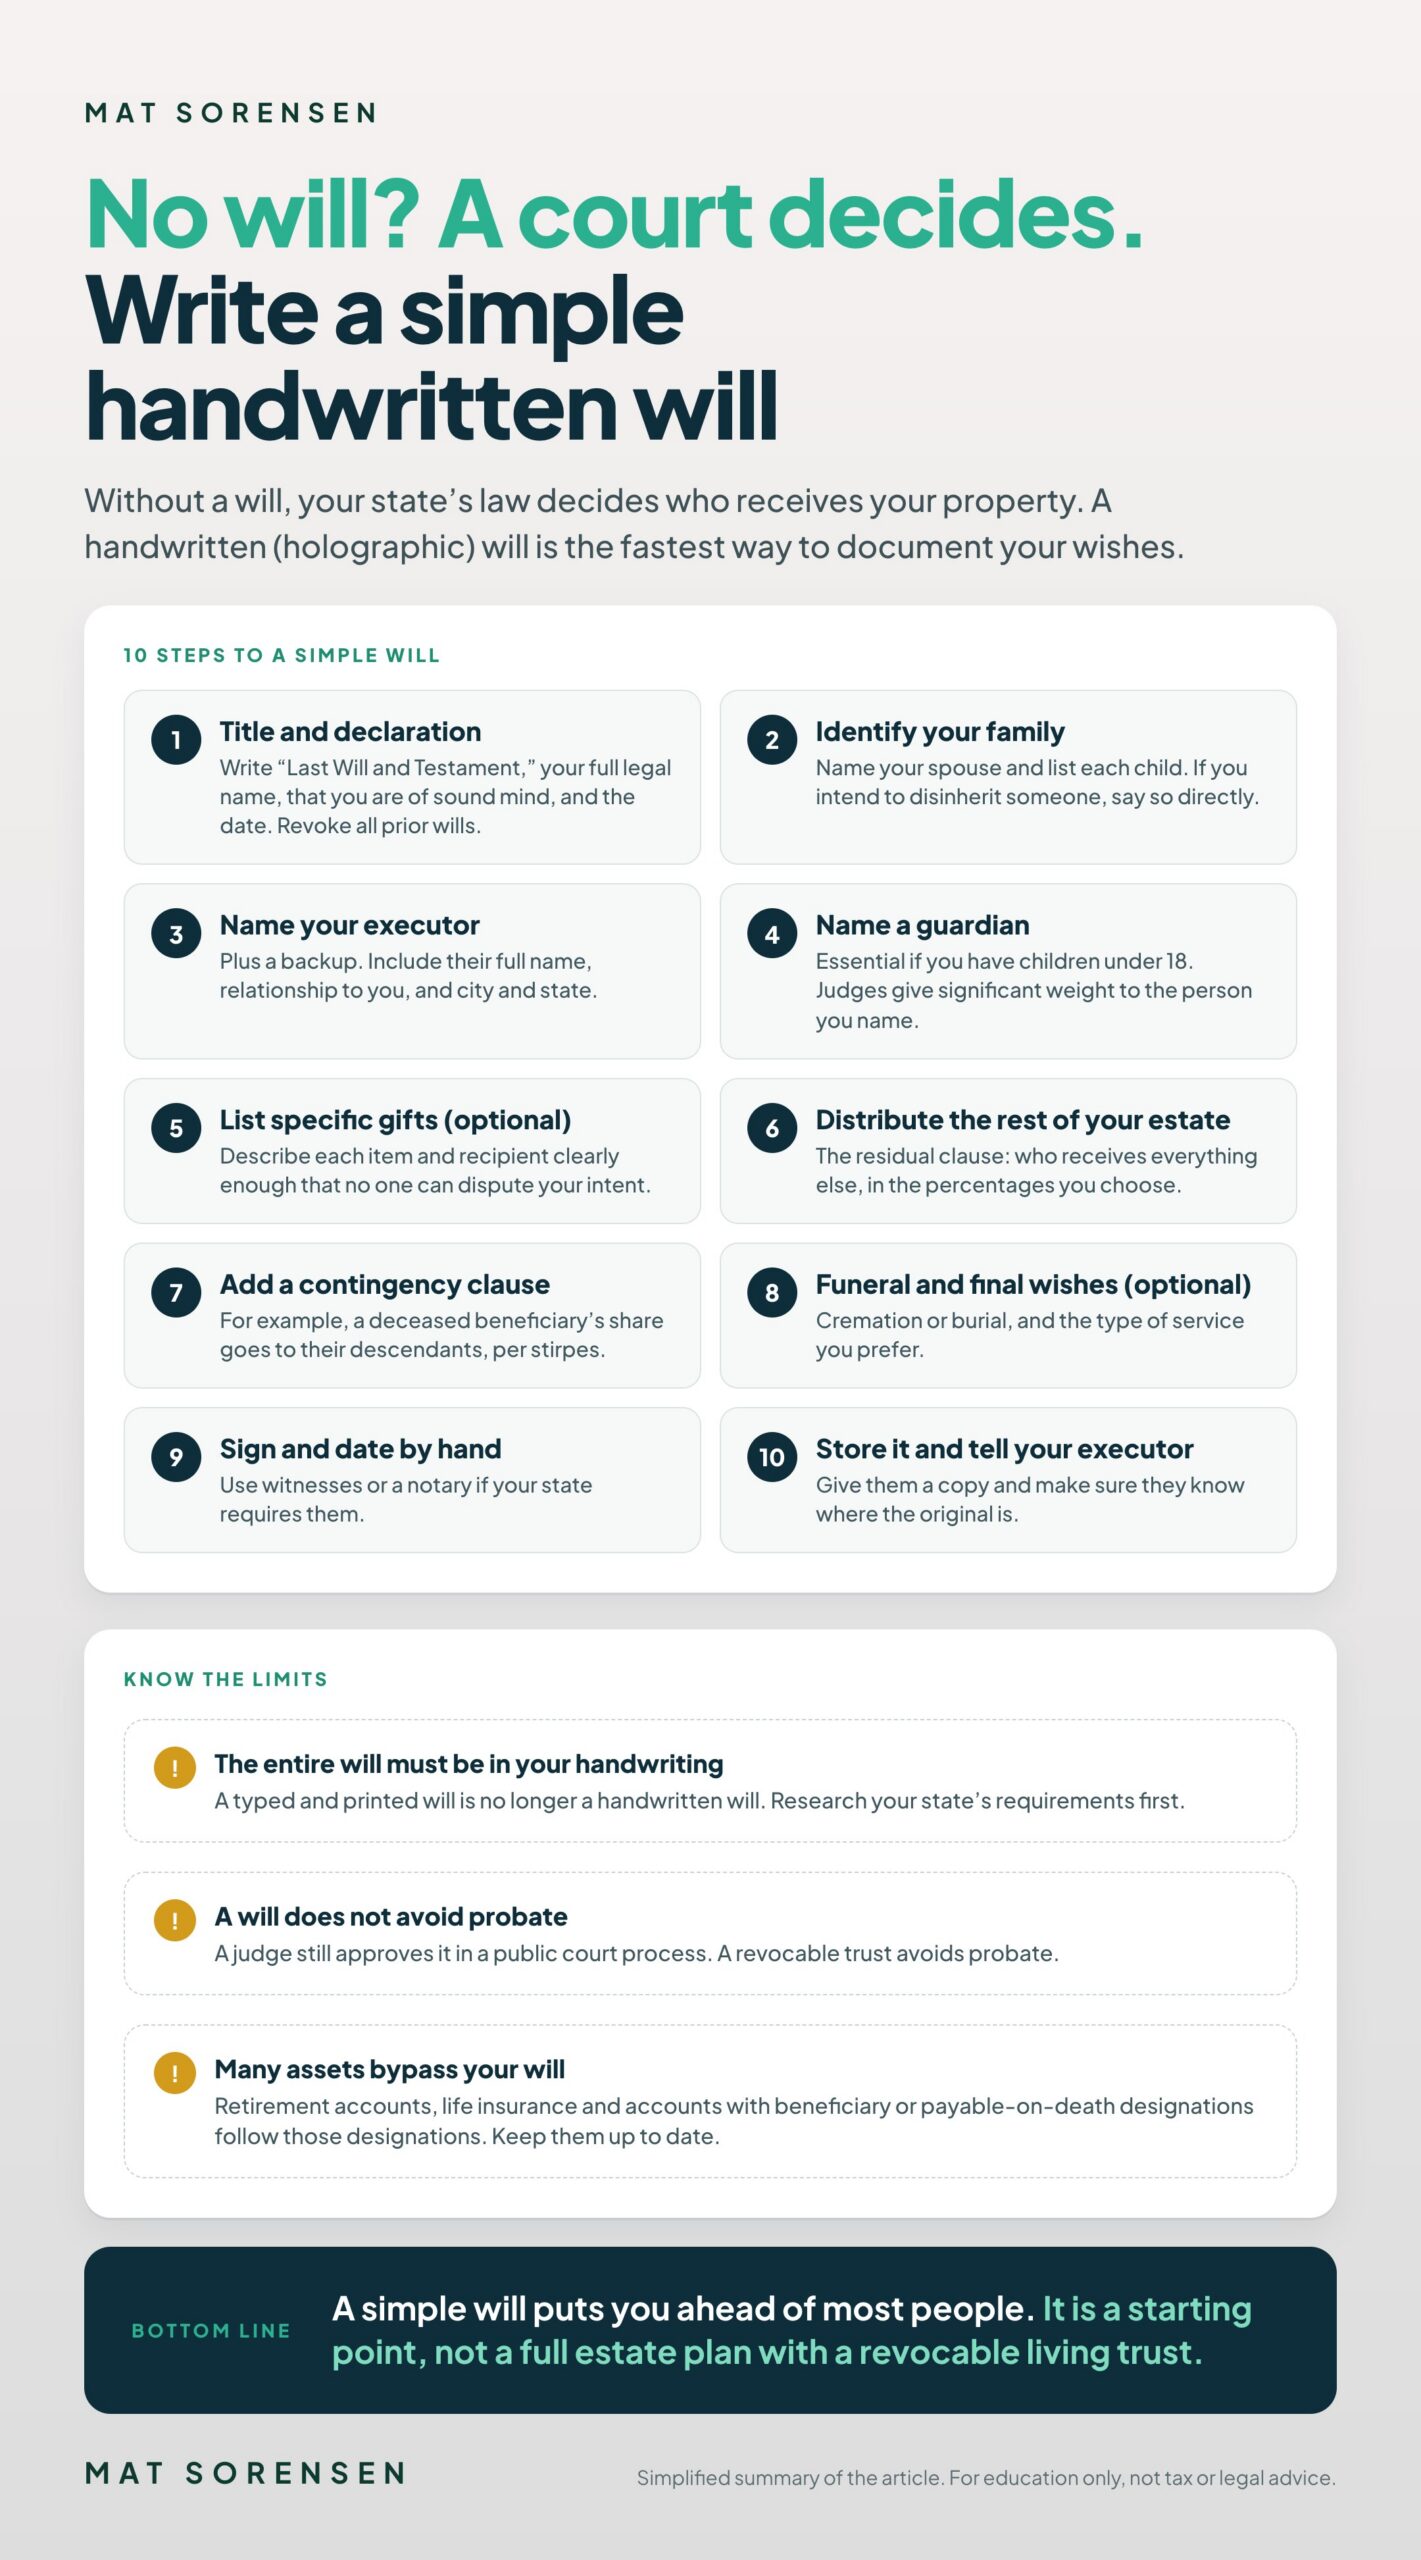
Infographic: 10 steps to write a simple handwritten will, and the limits of a will

What We’re Creating: A Simple Handwritten Will

We are creating a simple handwritten will, also known as a holographic will. This document must be handwritten and signed by you; in many states, those requirements make it legally valid and enforceable. Do not type and print this will, because it will no longer constitute a handwritten / holographic will. If you want to use this simple approach, the entire will must be in your handwriting.

CHECK YOUR STATE

Each state has unique laws regarding handwritten wills, and the laws of the state where you reside will apply to you. Many of these states do not require witnesses or other formalities, but each state is different, so you should research your state’s requirements before writing your handwritten will.

Step 1: Start With the Title and Declaration

First, write ‘Last Will and Testament’ at the top of the page. Next, include your full legal name, a statement that you are of sound mind, and the date. For example, I might write: ‘I, Mat Sorensen, being of sound mind, declare this to be my last will and testament. I revoke all prior wills and codicils.’ This language makes it clear that this document controls and cancels any earlier wills or similar documents.

Step 2: Identify Your Family

Next, you need to identify your family. Clearly state whether you are married and, if so, name your spouse. State whether you have children, and if you do, list each child in the will. This helps anyone reading the will understand whether someone was intentionally left out or simply omitted by mistake. For example, if you have three children but only list two and do not clearly disinherit the third, a court might decide to divide your estate among all three. To avoid confusion, list each child and, if you intend to disinherit someone, state that directly. Keep this section simple and factual by stating your relationships and names without extra language like ‘my favorite’ or ‘my first-born.’

Step 3: Name Your Executor

In this step, you will need to name an executor. This is one of the most important decisions in your will, because the executor handles your estate, pays any debts or taxes, and has the authority to distribute your assets.

EXAMPLE

In your handwritten will, write something like: ‘I designate [Full Name] as executor of my estate.’

In many cases, people choose a spouse or one of their children, often someone who is responsible, good with money, and able to handle the emotional and financial duties involved. You may also want to name a backup executor in case your first choice has died or is unable to serve. When listing your executor, include their full name, their relationship to you, and the city and state where they live.

Step 4: Name Your Guardian

If you have any children under 18, naming a guardian is essential. This can be one of the most critical sections of your will, because you are choosing who would raise your children if you pass away. You may feel that your parents are the best choice, but that may not be ideal if they would rather be grandparents than take on the full responsibility of parenting again. You might instead consider a sibling with children of similar ages, or a close friend or cousin you trust and who shares your values.

Note that the person you name is not automatically guaranteed to become the guardian. A court will ultimately decide who serves, based on who steps forward and what is in the best interests of your children, but judges give significant weight to the person you name in your will. If you do not list anyone, the court will decide without your guidance, which can lead to conflict within your family at a time when they are already grieving. Your family will want direction from you, so clearly list who you would want to serve as guardian for your children.

Step 5: List Specific Gifts (Optional But Helpful)

If there are particular items you want to leave to specific people, you should list them clearly. For example, you might leave a piece of jewelry to your daughter, a shared boat to your brother, or a business interest to your business partner. When you do this, be specific so there is no confusion about what goes to whom, such as: ‘I leave my electric guitar to [Full Name] in [City, State].’ The goal is to describe each item and recipient clearly enough that no one can reasonably dispute your intent. Do not overthink this section; if it slows you down, you can skip it for now and add or adjust specific gifts later. The purpose of this handwritten will is speed and clarity so you can get something in place, knowing you can always revise it in the future.

Step 6: Distribute the Rest of Your Estate

This section explains who receives the rest of your estate. It is the core distribution section of your will and is often called the ‘residual’ clause, because it covers everything that has not been specifically given away earlier. After any specific gifts you list, this clause directs all remaining assets to the people you choose in the percentages you select.

If you are married, you may want your spouse to receive everything that is left. You could say, ‘If I pass away, my surviving spouse receives the entirety of my residual estate.’ If your spouse has already died, or if you are single, you can then direct your remaining estate to your children or other beneficiaries in whatever percentages you decide.

When naming your children—whether they inherit if your spouse is not living or you are single and they are your primary beneficiaries—you should specify their shares as percentages. For example, if you have two children, you might have each inherit 50% of your estate, or you might choose a different split such as 10% for one child and 90% for the other. It is your wealth and legacy, and you decide how it is divided.

When writing this clause, you might say something like, ‘I leave the remainder of my estate to my children, to be split evenly, 50% to each.’ The key is to make it crystal clear who gets what. A simple handwritten will will not cover every possible contingency, such as what happens if a child dies before you or whether that child’s share should pass to their own children. Those details are usually addressed in an estate plan which is more comprehensive. 

Step 7: Add A Contingency Clause

If you want to add more detail about contingent beneficiaries, you can do that in this section. A common approach is to say something like, ‘If any of my beneficiaries listed above are deceased at the time of my death, I want their share to go to their descendants, per stirpes.’ This means that if you have four children who each receive 25% of your estate and one child dies before you, that child’s 25% share would go to that child’s heirs rather than being split among the surviving siblings. You may prefer a different approach, but using a per stirpes designation is a simple and widely used way to make sure a deceased beneficiary’s share passes down their family line.

Step 8: Funeral and Final Wishes (Optional)

Now you will state your funeral and final wishes. Indicate whether you prefer cremation or burial and note any preferences for the type of service, such as military or religious. You can also include any special requests that matter to you. This section is optional, and if you are trying to complete this handwritten will quickly, you can keep it very brief or skip it entirely as it is optional.

Step 9: Sign and Date Properly

This step makes this document official. You must physically sign and date your written will by hand. If your state requires witnesses or a notary, ensure they observe your signature and signing date. Not every state requires witnesses or a notary, so research your specific state’s requirements to ensure your written will is valid. In most states, your signature alone is sufficient.

Step 10: Store It and Tell Your Executor

Finally, you need to store your will safely and tell someone you trust about it and its location, because if no one knows it exists or where to find it, your executor and family cannot use it after you pass away. Make sure your executor knows they are named and understands their role, give them a copy of the will so they are familiar with your wishes, and clearly tell them where the original is stored. Your executor will need to file the original will with the probate court, so they must know exactly where it is and how to access it; do not hide it where it could be lost or overlooked.

Important Reality Check: A Will Does Not Avoid Probate

It is important to note that a will does not avoid probate—this is a common misunderstanding. With a will, you specify who receives your assets after you pass away, but the document still must go through a public court process where a judge approves it. This differs from a revocable trust, which avoids probate entirely. 

Many assets pass outside of your will anyway, such as retirement accounts, life insurance, bank accounts, or investment accounts with payable-on-death or beneficiary designations. Each has their own beneficiary designations—not within your will—which control who receives them, so make sure they are up to date. If you want to avoid probate altogether and include more detailed rules or contingencies, consider a trust-based estate plan, such as a revocable living trust.

If You Followed These Steps, You Now Have a Legally Valid Will

You now have a simple will in place that puts you ahead of most people. However, this is just a starting point, not the end. If you have substantial assets, real estate, a blended family, retirement accounts, or life insurance—and you want to avoid probate—you should consider getting a full estate plan with a revocable living trust done. 

If you want help getting this done, my law firm, KKOS Lawyers works with clients across the country, and you can book a call using the link below. We can go over the benefits of a full estate plan, the revocable living trust, power of attorney, and all the documents that help you leave your legacy behind.

Contact Us – KKOS Lawyers

The End of Real Estate LLC Privacy? New Rule Explained

The federal government is tightening its grip on real estate ownership disclosure — and if you plan to hold property in an LLC, your privacy may need to disclose the ownership and make filing to the federal government. Starting March 1, 2026, a new federal rule requires disclosure of who actually owns certain real estate in LLCs, giving regulators deeper visibility into ownership structures that many investors rely on for privacy and asset protection. Under this law, you must file a report with the federal government in any of the following situations:

  • ✓You transfer residential real estate from your personal name into your own LLC (or an LLC owned by anyone else).
  • ✓You purchase residential real estate in your LLC using cash and no licensed bank lender is involved.
  • ✓You acquire residential real estate using creative financing (such as seller-financed or “subject-to” transaction where no traditional bank mortgage is involved) and the property is held in your LLC.

If any of these situations apply to you, you are required to file this new report for each property that is transferred to or acquired in an LLC. 

UPDATE (NOV 2026)

On March 19, 2026, a federal court in Texas (Flowers Title Companies v. Bessent) vacated this rule. FinCEN says that while that order is in force, no one has to file Real Estate Reports and there is no penalty for not filing. FinCEN has appealed, so the rule could come back if the decision is reversed. (Source: FinCEN, via Holland & Knight)

Infographic: when the FinCEN residential real estate report applies to LLCs, who files it, what it discloses, and key exemptions

What Is This Law Trying to Do?

This new requirement is a FinCEN rule issued under the Bank Secrecy Act and is, frankly, a nuisance for ordinary real estate owners and investors. It is separate from the Corporate Transparency Act, the law Congress passed a few years ago that created beneficial ownership information (BOI) reporting for LLCs and corporations. While BOI reporting for many LLCs and corporations is no longer required as a result of treasury guidance saying it doesn’t apply to U.S. citizen owners, this real estate reporting rule for LLCs was not part of that change (but see the update above). Its stated purpose is to fight money laundering by making it clearer who actually owns and controls LLCs that hold real estate.

When Does This Law Apply?

Three criteria must be met for this law to apply. 

  1. 1The property must be residential real estate. This includes a single-family home, condo, duplex, fourplex, or land intended to be developed for residential use. Commercial properties or apartment buildings with five or more units do not qualify.
  2. 2The purchase must be made in your LLC without using a bank or mortgage lender. When banks or mortgage lenders are involved, they run your information through FinCEN (the Financial Crimes Enforcement Network), which satisfies the federal reporting requirement. However, if the property is purchased with cash, through seller-financed or “subject-to” arrangements, or with other forms of creative financing, there is no federal reporting in place—triggering the need for this disclosure report.
  3. 3The transaction must involve a transfer to an entity, such as an LLC or corporation. For example, if you buy real estate in your own name and then transfer it to an LLC, this new report would be required.

If all three criteria are met, you must file this residential real estate report with FinCEN online at fincen.gov.

Exemptions to the Residential Real Estate Rule

 Using a trust to purchase or hold residential real estate can qualify for an exemption from the residential real estate reporting rule. If you establish a trust (as the settlor or grantor) and transfer property from your personal name into that trust, that transfer is exempt and no real estate report is required under this rule. This exemption was primarily created to negate the requirement of individuals transferring property they own to a trust they have set-up for themselves and their family. 

Some clients have asked whether they can buy residential real estate in a trust that is owned by an LLC (LLC is beneficiary to trust) to maintain privacy and avoid filing this new report. The idea is that, even though the LLC is the beneficiary, they hope the trust exemption will still protect them. At this time, there is limited guidance on this approach because the rule is new and FinCEN has not clearly addressed this specific structure. That said, if your primary goals are privacy with the federal government and potentially avoiding the reporting requirement, there may be strategies involving additional trusts and structuring options that leverage the trust exemption, though they typically come with added complexity and cost. Keep in mind though, much like your personal tax return, the federal real estate report that is filed is not available publicly and is not searchable by the public or available under a freedom of information act request. 

Who Has to File This Report?

The person responsible for filing the residential real estate report is determined by a reporting “cascade.” In simple terms, if a title or escrow company is involved in the transaction, that company is required to file the report. If no title or escrow company is involved, the responsibility shifts to the person or firm that prepares the deed.

At my law firm KKOS Lawyers, we prepare hundreds of deeds each month, transferring properties from our clients’ personal names into LLCs or trusts. When we prepare your deed, we also handle this real estate report on your behalf. If you are working with another law firm or service provider, you should expect them to prepare and file the report whenever they are transferring property into an LLC and the rule is triggered. If you prepare the deed yourself and do not use a title or escrow company then you are the one responsible for filing the report with FinCEN.

Why Is There Controversy Surrounding This New Report?

The real estate report requires you to disclose anyone who owns 25% or more of the LLC, as well as anyone who exercises control over the LLC, such as the manager. In other words, every individual with at least 25% ownership or significant decision-making authority must be reported to the federal government. Many clients prefer not to disclose ownership information to the government, the state, or in any public record because they value privacy. However, under this rule, you are required to report all individuals who meet the 25% ownership threshold or who have control of the LLC.

How to Fill Out the New Form, Step by Step!

You can find the Real Estate Report form that must be filed with FinCEN here: RER Form

Screenshot of the FinCEN Real Estate Report form

In the first section, enter the name of the filer or the name of the trust, and select the appropriate filing type. The preparation date will be filled in automatically.

Screenshot of the FinCEN Real Estate Report form

In Part I, you will first identify who is filing and completing the report. For example, if we at KKOS Lawyers were preparing it on your behalf, we would select ‘Deed Instrument Filer’ and enter our firm’s name.

Screenshot of the FinCEN Real Estate Report form

In Part II, you will provide the property information. Enter the street address and the full legal description of the property, which you can find on your property deed.

Screenshot of the FinCEN Real Estate Report form

In Part III, you will identify who is receiving the property. Start by completing the transferee section with your LLC’s information, then list all individuals who own 25% or more of the LLC.

If you are transferring property from your personal name into an LLC for real estate investing, and no money is actually changing hands, you can indicate that no consideration was paid. Next, enter the LLC’s legal name, address, and EIN. This section is focused on the entity that will own the property.

When you reach ‘Person(s) associated with the transferee,’ you must list everyone who owns at least 25% of the LLC, as well as anyone with significant decision-making authority. If you are completing the form for your own LLC, you would list yourself as a beneficial owner, indicate your citizenship, and provide your personal information. Unlike the BOI reports that never went into effect, this form does not require you to upload a copy of your government ID. If there is more than one beneficial owner or decision-maker, use the ‘+’ button to add each additional person and include all of their required details.

Screenshot of the FinCEN Real Estate Report form

In Part IV, you will identify who is transferring (deeding) the property to the LLC. If you are moving property from your personal name into your LLC, enter your own information here. If the property is being received through any other method, list the details of the transferor accordingly.

Screenshot of the FinCEN Real Estate Report form

In Part V, you will detail any payment information involved in the transaction. This includes the amount paid, the banks used, and the account numbers where the funds were transferred. For most clients transferring property from their personal name to their own LLC for asset protection—with no money changing hands—you can simply select ‘No Consideration Paid’ and skip the rest of this section.

The core requirements of this report are straightforward: disclosing the LLC’s owners, identifying the property, and specifying the transferor. That’s the key information being filed with the federal government.

Frequently Asked Questions

1. What if I’ve already transferred properties to my LLC before March 1, 2026? Do I need to file retroactively?

No, this rule only applies to deed transfers and purchases occurring on or after March 1, 2026.

2. Where is this information stored, and can the public access it?

The report contains private information, similar to your tax return. It is not publicly searchable, and even under the Freedom of Information Act, no one can request it from FinCEN. If other government agencies were to request it, they would have to obtain a subpoena first.

3. Do self-directed IRA owners need to file if purchasing residential real estate through an IRA or IRA LLC?

If you acquire property directly in your IRA or through a custodial arrangement, no report is required. However, if an IRA LLC (or an LLC owned by your IRA) purchases residential real estate without a bank or mortgage lender involved, you must file the real estate report. If a title company, attorney, or deed preparer is handling the transaction, they will file it on your behalf.

While this new requirement adds an extra step to the process, compliance is still mandatory. Failure to file can result in civil penalties or even criminal charges. To stay compliant, engage the right professionals—like a title company, attorney, or deed preparer—who will file the report on your behalf, or complete it yourself if no such parties are involved. The goal is clear: enjoy the asset protection benefits of an LLC while ensuring this report is filed whenever you transfer residential real estate into one.

For those interested in creative strategies or leveraging the trust exemption, additional structuring may offer ways to navigate this requirement—though success depends on your state’s laws and your specific estate. Always consult a lawyer for advice tailored to your situation. If you’d like to connect with an attorney at KKOS Lawyers, click the link below—we’re here to help.

Contact Us – KKOS Lawyers