Back Door Roth IRA Rules and Steps

Roth IRAs can be established and funded for high-income earners by using what is known as the “back door” Roth IRA contribution method. Many high-income earners believe that they can’t contribute to a Roth IRA because they make too much money and/or because they participate in a company 401k plan. Fortunately, this thinking is wrong. While direct contributions to a Roth IRA are limited for taxpayers with income in excess of $153,000 ($242,000 for married taxpayers, 2026), those whose income exceeds these amounts may make annual contributions to a non-deductible traditional IRA and then convert those amounts over to a Roth IRA.
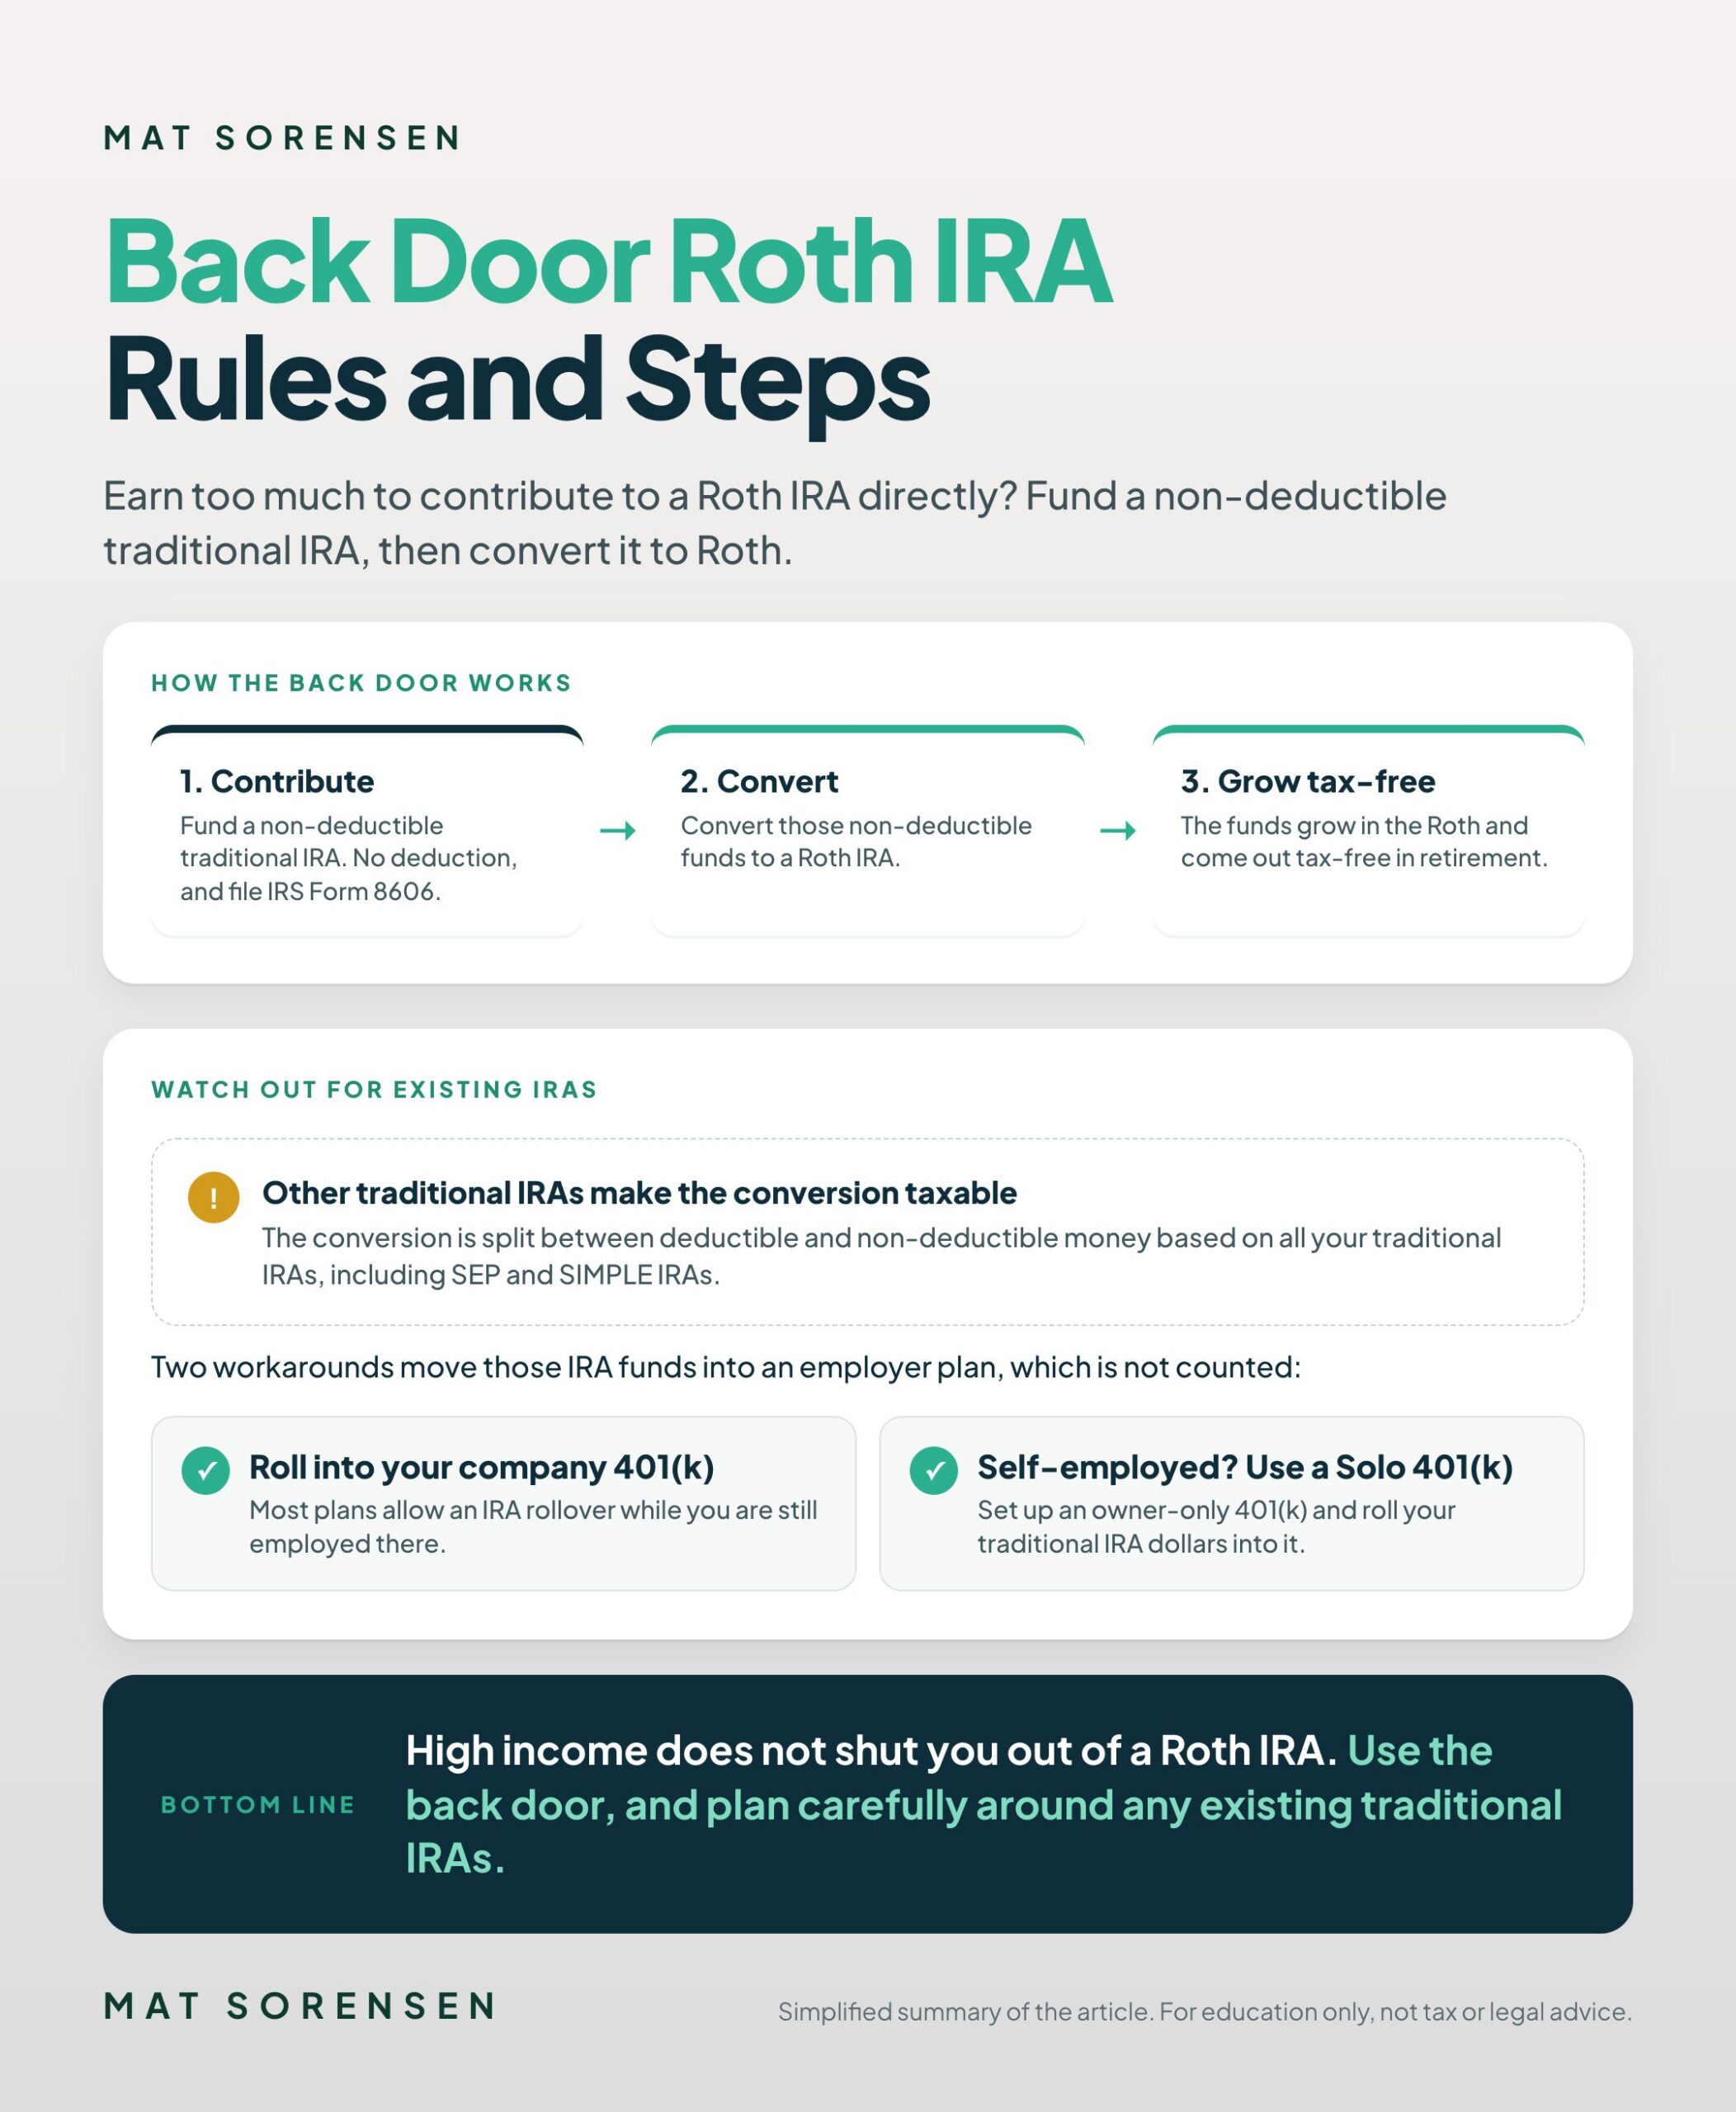
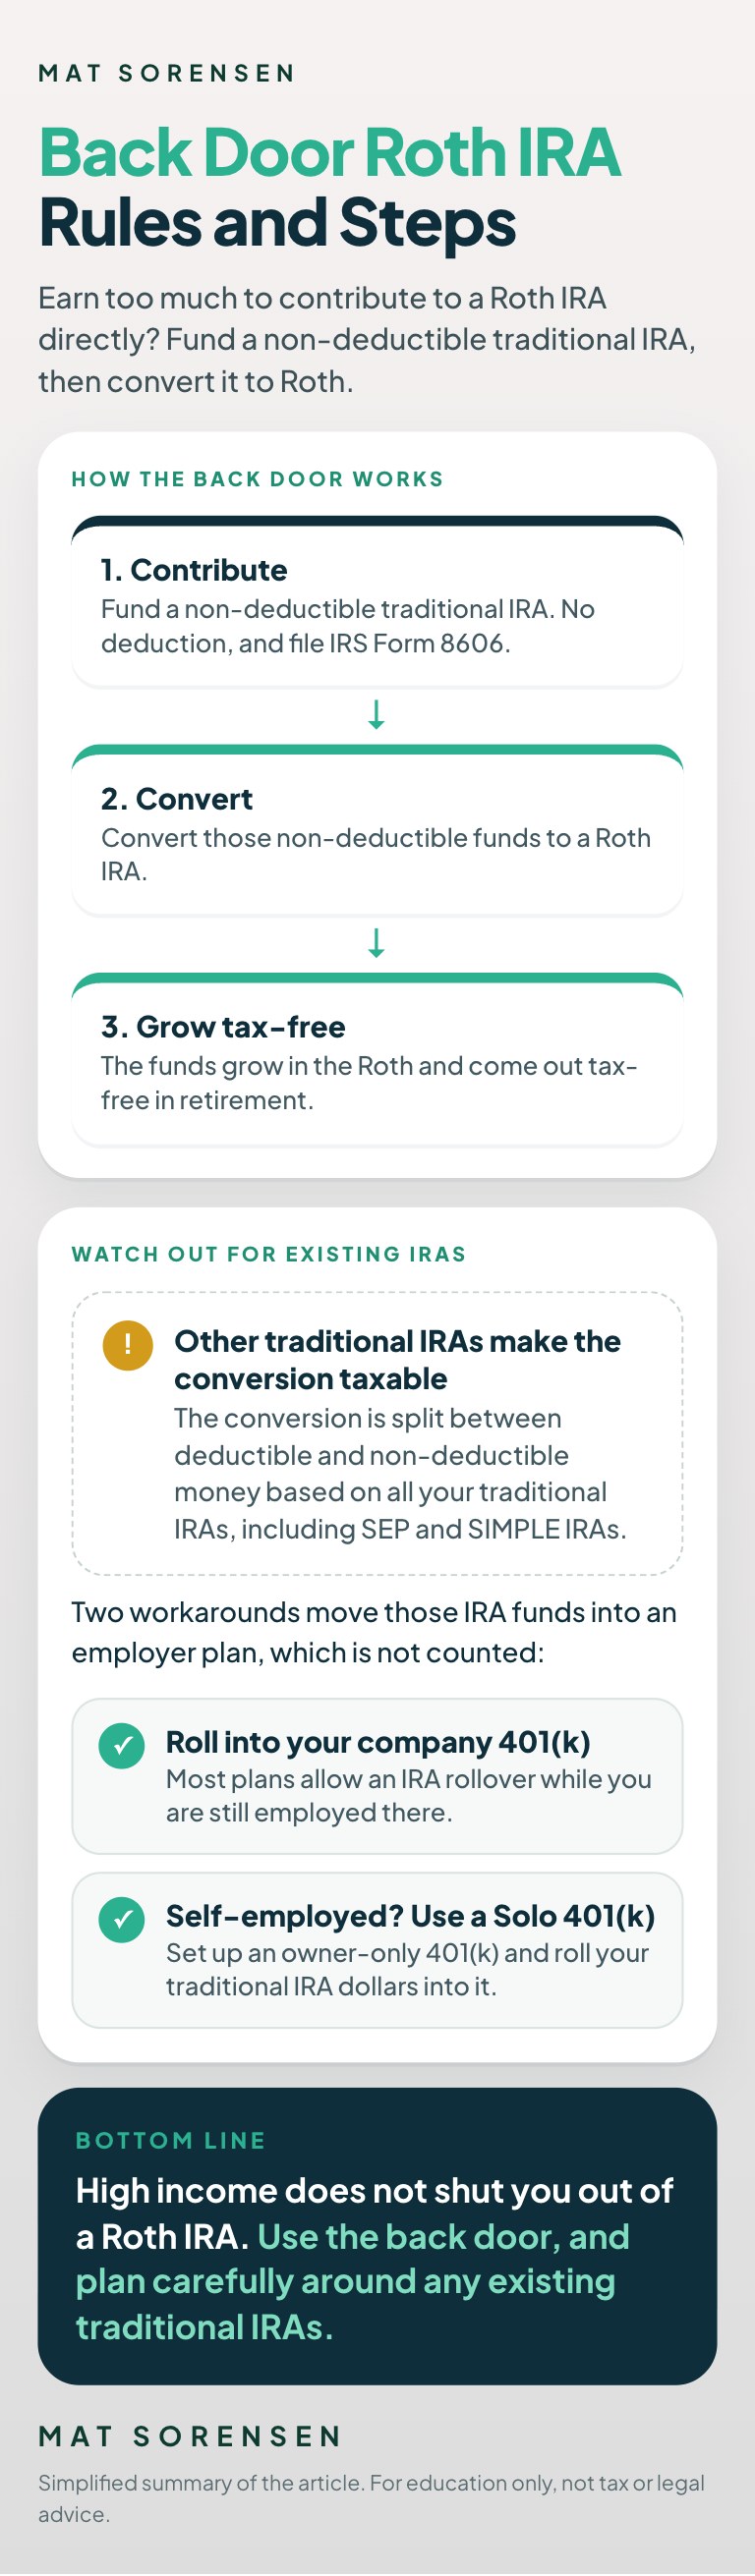
Infographic: how the back door Roth IRA works. Contribute to a non-deductible traditional IRA, convert it to a Roth IRA, and grow tax-free, plus how existing traditional IRAs make the conversion taxable and two 401(k) workarounds

Examples

Here are a few examples of earners who can establish and fund a Roth IRA.

  1. 1I’m a high-income earner and work for a company that offers a company 401(k) plan. I contribute the maximum amount to that plan each year. Can I establish and fund a Roth IRA?
    Yes, even though you are high-income and even though you participate in a company 401(k) plan, you can establish and fund a Roth IRA.
  2. 2I’m self-employed and earn over $242,000 a year; can I have a Roth IRA? Isn’t my income too high? Yes, you can contribute to a Roth IRA despite having an income that exceeds the Roth IRA income contribution limits of $242,000 for married taxpayers and $153,000 for single taxpayers

The Process

The strategy used by high-income earners to make Roth IRA contributions involves the making of non-deductible contributions to a traditional IRA and then converting those funds in the non-deductible traditional IRA to a Roth IRA. This is oftentimes referred to as a “back door” Roth IRA. In the end, you don’t get a tax deduction in the amounts contributed, but the funds are held in a Roth IRA and grow, then come out tax-free upon retirement (just like a Roth IRA). Here’s how it works.

Step 1: Fund a new non-deductible traditional IRA

This IRA is “non-deductible” because high-income earners who participate in a company retirement plan (or who have a spouse who does) can’t also make “deductible” contributions to an IRA. The account can, however, be funded by non-deductible amounts up to the IRA annual contribution amounts of $7,500. The non-deductible contributions mean you don’t get a tax deduction on the amounts contributed to the traditional IRA. You don’t have to worry about having non-deductible contributions as you’re converting to a Roth IRA, so you don’t want a deduction for the funds contributed. If you did get a deduction for the contribution, you’d have to pay taxes on the amounts later converted to Roth. You’ll need to file IRS form 8606 for the tax year in which you make non-deductible IRA contributions. The form can be found here.

If you’re a high-income earner and you don’t have a company-based retirement plan (or a spouse with one), then you simply establish a standard deductible traditional IRA, as there is no high-income contribution limitation on traditional IRAs when you don’t participate in a company plan.

Step 2: Convert the non-deductible traditional IRA funds to a Roth IRA

In 2010, the limitations on Roth IRA conversions, which previously restricted Roth IRA conversions for high-income earners, were removed. As a result, since 2010 all taxpayers are able to convert traditional IRA funds to Roth IRAs. It was in 2010 that this back door Roth IRA contribution strategy was first utilized, as it relied on the ability to convert funds from traditional to Roth. It has been used by thousands of Americans since.

If you have other existing traditional IRAs, then the tax treatment of your conversion to Roth becomes a little more complicated, as you must take into account those existing IRA funds when undertaking a conversion (including SEPs and SIMPLE IRAs). If the only IRA you have is the non-deductible IRA, then the conversion is easy because you convert the entire non-deductible IRA amount over to Roth with no tax on the conversion. Remember, you didn’t get a deduction into the non-deductible traditional IRA so there is no tax to apply on conversions. On the other hand, if you have an existing IRA with say $95,000 in it and you have $5,000 in non-deductible traditional IRA contributions in another account that you wish to convert to Roth, then the IRS requires you to convert over your IRA funds in equal parts deductible (the $95K bucket) and non-deductible amounts (the new $5K) based on the money you have in all traditional IRAs. So, if you wanted to convert $10,000, then you’d have to convert $9,500 (95%) of your deductible bucket, which portion of conversion is subject to tax, and $500 of your non-deductible bucket, which isn’t subject to tax once converted. Consequently, the “back door” Roth IRA isn’t well suited when you have existing traditional IRAs that contain deductible contributions and earnings from those sums.

There are two workarounds to this Roth IRA conversion problem and both revolve around moving the existing traditional IRA funds into a 401(k) or other employer-based plans. Employer plan funds are not considered when determining what portions of the traditional IRAs are subject to tax on conversion (the deductible AND the non-deductible). If you participate in an existing company 401(k) plan, then you may roll over your traditional IRA funds into that 401(k) plan. Most 401(k) plans allow for this rollover from IRA to 401(k) so long as you are still employed by that company. If you are self-employed, you may establish a solo or owner-only 401(k) plan and you can rollover your traditional IRA dollars into this 401(k). In the end though, if you can’t roll out existing traditional IRA funds into a 401(k), then the “back door” Roth IRA is going to cause some tax repercussions, as you also have to convert a portion of the existing traditional IRA funds, which will cause taxes upon conversion. Taxes on conversion aren’t “the end of the world” though as all of the money that comes out of that traditional IRA would be subject to tax at some point in time. The only issue is it causes a big tax bill initially, so careful planning must be taken.

The bottom line is that Roth IRAs can be established and funded by high-income earners. Don’t consider yourself “left out” on one of the greatest tax strategies offered to Americans: the Roth IRA.

FREE SELF-DIRECTED IRA GUIDE

Learn how a self-directed Roth IRA can invest in real estate, private companies, notes, and more, and keep the growth tax-free.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

Mat Sorensen

Mat has been at the forefront of the self-directed IRA industry since 2006. He is the CEO of Directed IRA & Directed Trust Company where they handle all types of self-directed accounts (IRAs, Roth IRAs, HSAs, Coverdell ESA, Solo Ks, and Custodial Accounts) which are typically invested into real estate, private company/private equity, IRA/LLCs, notes, precious metals, and cryptocurrency. Mat is also a partner at KKOS Lawyers and serves clients nationwide from its Phoenix, AZ office.

He is published regularly on retirement, tax, and business topics, and is a VIP Contributor at Entrepreneur.com. Mat is the best-selling author of the most widely used book in the self-directed IRA industry, The Self-Directed IRA Handbook: An Authoritative Guide for Self-Directed Retirement Plan Investors and Their Advisors.

Seller Financed Deals and Installment Sales

Seller financed deals can be a win-win strategy for buyers and sellers of real estate or businesses. Seller financing means the seller of the asset, whether a business or property, agrees to take payments over time for the purchase price and as a result the seller is financing the sale of the asset to the buyer. This has many benefits for a seller as it only opens up more buyers and hopefully a higher sales price but it also includes a tax incentive to the seller who will get to consider the sale of the asset as an installment sale. An installment sale allows the seller to defer recognition of the gain until the time the payments and the resulting gain are received.

Infographic: how an installment sale taxes each seller-financed payment using the gross profit percentage, a worked example, the benefits and drawbacks for the seller, and the documents that protect the sale

How an Installment Sale Is Taxed

In an installment sale, you report your gain on the sale of asset only as it is received. Each payment will be partially non-taxable as it represents a return of basis (what you invested into the asset) and the taxable part which is your profit (gain, appreciation). So, when you sell an asset on an installment sale you do not pay all of the taxes in the year you sell the asset because you have not fully received payment. Instead, you pay taxes only as you receive payment. To correctly report the taxes, you need to determine what portion of each installment payment is a return of basis versus profit.

Calculating the Taxable Portion of Each Payment

To do this, you divide your gross profit (selling price minus basis) by the contract price.

EXAMPLE

For example, say you purchased a property for $100,000 and later sell it for $400,000 under seller financed terms. Since you purchased the property for $100,000, you have a basis of $100,000 (you would also adjust the basis for improvements, depreciation, and other factors) and we are assuming here a contract sale price is $400,000. This gives you a gross profit of $300,000 (selling price minus basis). You then divide your gross profit of $300,000 by the $400,000 contract sale price, which equals 75%. You then take this 75% and apply it to each payment to determine which portion of the payment is taxable. This makes sense because each payment you receive, in this example, equally consists of a return of your basis, which is not taxable, and a payment towards the gross profit, which is taxable. To finish this example at 75%, if the annual payments totaled $40K, you’d have $30K that is taxable and $10K that is not taxable. If there is interest charged on the amount due that interest portion is also taxable as it is received.

$300,000

Gross profit ($400,000 sale price minus $100,000 basis)

75%

Of each payment is taxable

$30K of $40K

Annual payments that are taxable

Benefits and Drawbacks for the Seller

The tax benefit of the installment sale is that you only take a portion of the gain into income each year over time. This gives the advantage of deferring taxes over time and can also keep you in a lower tax bracket on your other income. The major disadvantage is that you do not obtain the sale proceeds immediately and as a result you cannot invest them elsewhere. To counter this, most sellers will charge the buyer interest on the seller financed balance that is due, say 7-10%, to offset the inability to invest the funds immediately.

As a seller, you will want to have a properly drafted promissory note as well as a security document that is secured against the asset being sold (e.g. mortgage/deed of trust recorded against the property). Make sure you are collaborating with experienced professionals when selling assets with seller-financing as there are tax considerations and legal protections you want to ensure are being considered in the structuring and documents.

Self-Directed IRA Versus Solo 401(k)

Many self-directed investors have the option of choosing between a self-directed IRA or a self-directed solo 401k. Both accounts can be self-directed so that you can invest in any investment allowed by law such as real estate, LLCs, precious metals, or private company stock. However, depending on your situation, you may choose one account type over the other. What are the differences? When should you choose one over the other?

We’ve been advising clients for over a decade on self-directed IRAs and solo 401(k)s and what we’ve learned is that there is no universal answer to the question. Instead, you need to learn what is best based on your personal situation and investment objectives. Do you even qualify for a solo(k)? What investments do you plan to make and does one account type make a difference for your investments? The good news is that either way you go, we can help with a self-directed IRA at Directed IRA, where we are a licensed trust company and can serve as custodian of your IRA. Or, we can set-up a solo(k) at KKOS Lawyers using our pre-approved plan documents.

Infographic: how a self-directed IRA and a solo 401(k) compare on eligibility, contributions, Roth options, set-up, control, and leveraged real estate

Comparing the Two Accounts

IRA Solo 401K
Qualification Must be an individual with earned income or funds in a retirement account to roll over. Must be self-employed with no other employees besides the business owner and family/partners.
Contribution Max $6,000 max annual contribution. Additional $1,000 if over 50. $61,000 max annual contribution (it takes $140K of wage/se income to max out). Contributions are employee and employer.
Traditional & Roth You can have a Roth IRA and/or a Traditional IRA. The amount you contribute to each is added together in determining total contributions. A solo 401(k) can have a traditional account and a Roth account within the same plan. You can convert traditional sums over to Roth as well.
Cost and Set-Up You will work with a self-directed IRA custodian who will receive the IRA contributions in an SDIRA account. You must use an IRS pre-approved document when establishing a solo 401k. This adds additional cost over an IRA.
Custodian Requirement An IRA must have a third-party custodian involved in the account (e.g. bank, credit union, trust company) who is the trustee of the IRA. Of course we recommend our company, www.directedira.com. A 401(k) can be self-trustee’d, meaning the business owner can be the trustee of the 401(k). This provides for greater control but also greater responsibility.
Investment Details A self-directed IRA is invested through the self-directed IRA custodian. A self-directed IRA can be subject to a tax called UDFI/UBIT on income from debt leveraged real estate. A Solo 401(k) is invested by the trustee of the 401(k) which could be the business owner. A solo 401(k) is exempt from UDFI/UBIT on income from debt leveraged real estate.

UPDATE (NOV 2026)

This table uses 2022 limits. For 2026, the IRA limit is $7,500, plus $1,100 if you’re 50 or older, and the Solo 401(k) total limit is $72,000, plus catch-up contributions ($8,000 at age 50+). (Source: IRS)

Keep in mind that the solo 401(k) is only available to self-employed persons while the self-directed IRA is available to everyone who has earned income or who has funds in an existing retirement account that can be rolled over to an IRA.

Conclusion

Based on the differences outlined above, a solo 401(k) is generally a better option for someone who is self-employed and is still trying to maximize contributions as the solo 401(k) has much higher contribution amounts. On the other hand, a self-directed IRA is a better option for someone who has already saved for retirement and who has enough funds in their retirement accounts that can be rolled over and invested via a self-directed IRA as the self-directed IRA is easier and cheaper to establish.

Another major consideration in deciding between a solo 401(k) and a self-directed IRA is whether there will be debt on real estate investments. If there is debt and if the account owner is self-employed, they are much better off choosing a solo 401(k) over an IRA as solo 401(k)s are exempt from UDFI tax on leveraged real estate.

Choosing between a self-directed IRA and a solo 401(k) is a critical decision when you start self-directing your retirement. Make sure you consider all of the differences before you establish your new account.

FREE SOLO 401(K) GUIDE

Self-employed? Learn how a self-directed Solo 401(k) works and how much you can contribute.

Get the Free Solo 401(k) Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

Mat Sorensen

Mat has been at the forefront of the self-directed IRA industry since 2006. He is the CEO of Directed IRA & Directed Trust Company where they handle all types of self-directed accounts (IRAs, Roth IRAs, HSAs, Coverdell ESA, Solo Ks, and Custodial Accounts) which are typically invested into real estate, private company/private equity, IRA/LLCs, notes, precious metals, and cryptocurrency. Mat is also a partner at KKOS Lawyers and serves clients nationwide from its Phoenix, AZ office.

He is published regularly on retirement, tax, and business topics, and is a VIP Contributor at Entrepreneur.com. Mat is the best-selling author of the most widely used book in the self-directed IRA industry, The Self-Directed IRA Handbook: An Authoritative Guide for Self-Directed Retirement Plan Investors and Their Advisors.

6 Critical Trademark Considerations

Many clients wonder whether they need to trademark their business name. A trademark is a legal protection given to a business name or slogan and allows the owner to prevent others from using the same name or slogan. The purpose of a trademark is to give the owner of the mark exclusive use of the name or slogan so as to distinguish itself from its competitors. Trademarks provide protections against counterfeits or cheats trading on a good business name (and cashing in on someone else’s marketing) and also allow a business to avoid having someone else operate under the same name which helps to avoid confusion amongst consumers.

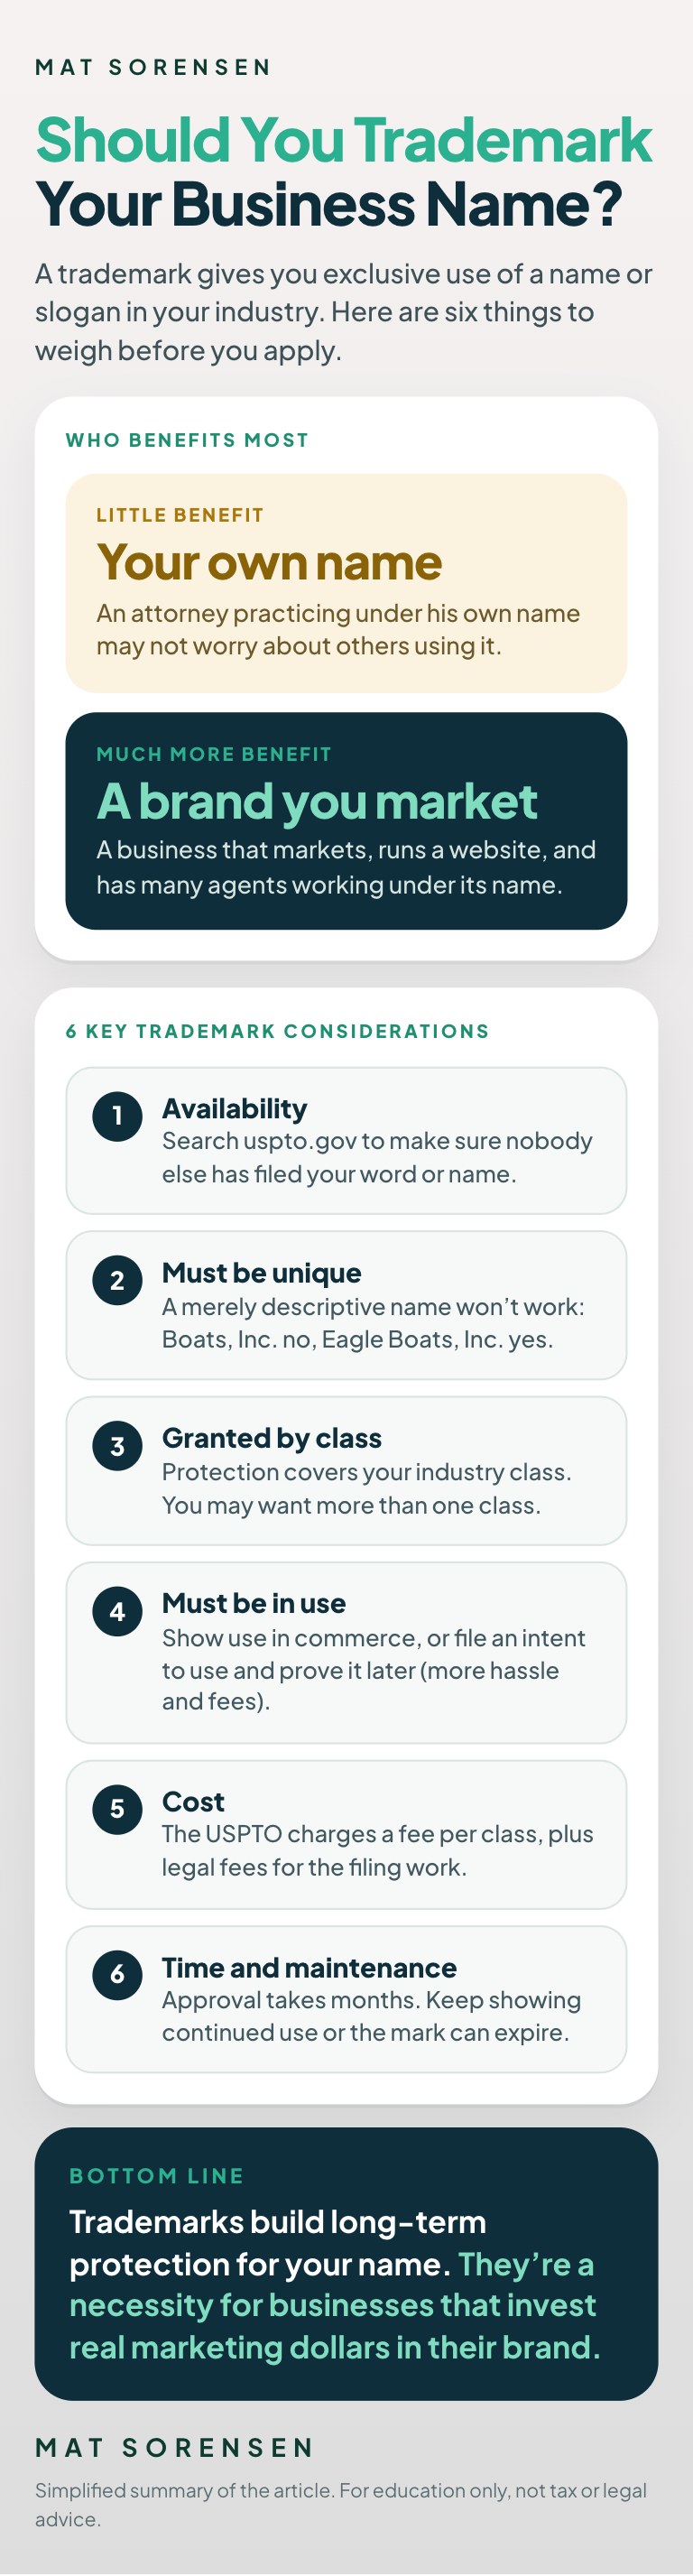
Infographic: who benefits most from a trademark and six key trademark considerations

EXAMPLE

For example, the business name “Google” is a trademark of Google, Inc. This trademark grants Google, Inc. the exclusive use of this name in their industry and prevents a competitor from simply opening up a website or business and offering products or services with the good “Google” name. This also protects consumers from doing business with someone they weren’t intending to do business with and also prevents other businesses from benefiting off of someone else’s marketing and brand recognition.

Do You Need a Trademark?

When deciding whether to trademark your business name or service you must first determine whether you want your name protected in the marketplace from use by others. An attorney operating as Mathew Sorensen Attorney at Law may not worry about someone operating under his business name and may see little benefit from a trademark. But a business named something like Paramount Real Estate Brokerage which conducts marketing under that name, maintains a website under that name, provides services under that name, and which employs many agents using that name would see much more benefit from a trademark. Trademark protection is done on a national basis so when your trademark is approved it grants national protection of your name or slogan. Those who use the name in violation of the trademark are in violation of law and can be sued by the owner of the mark for damages.

Key Trademark Considerations

When applying for a trademark keep in mind the following items.

1. Trademark Availability- Make sure nobody else has filed a trademark with your word/name. This can be searched at the uspto.gov website. Keep in mind that there can be similar names or marks in different industries (see point 3 below).

2. Trademark Must be Unique- The mark may not be merely descriptive. For example, you cannot expect to trademark the business name Boats, Inc. to sell boats as that is merely descriptive of what you do and doesn’t distinguish your business from others. A name like Eagle Boats, Inc. on the other hand is distinguishable since your use of the word Eagle in the industry could be unique.

3. Trademarks Are Granted by Industry/Class- A trademark is granted based on the industry your business is in (called class by USPTO). What this means is that your mark is protected in your area of business but is not protected across all businesses and product lines. For example, the word Paramount may be registered by one group in the USPTO entertainment class as Paramount Pictures but may be registered and owned by a totally different group as Paramount Real Estate in the USPTO real estate class. Keep in mind that your business may cross over into two classes and you may want the mark approved in more than one class.

4. Trademarks Must be In Use- The trademark must be in use in the economy (on a website, in a brochure) before the mark will be approved and this use must be shown to the USPTO with your filing. You can also state an intent to put the mark in commerce without actually doing it yet but then you need to go back to the USPTO to show the use later and this is much more of a hassle. It also costs more in fees.

5. Trademark Cost- The USPTO fee to do a trademark is $350 per class.

6. Trademark Time Frame and Maintenance- It typically takes about 9 months on average to get approval of a trademark with the USPTO. After the mark is approved you can start using TM next to your name or slogan (if you desire). You also have to show continued use of the mark to the USPTO every 5 years or so to maintain the mark. If you fail to show continued use the mark expires and may be picked up by someone else.

Trademarks are a great way to build long-term protection of your business name or product/service. They are a necessity for many businesses that invest significant marketing dollars into their business name or products/services. If you want to learn more, please contact the law firm to speak with one of the attorneys.

How to Disinherit a Child from your Estate?

What do you do when you have a child you’d like to disinherit from your estate? It’s not as easy as you think, so make sure you follow the proper procedures to specifically cut them out. Don’t just leave their name out of things and think that this will accomplish your goals as the laws in most states will presume you intended to have them be an heir unless you specifically state otherwise.
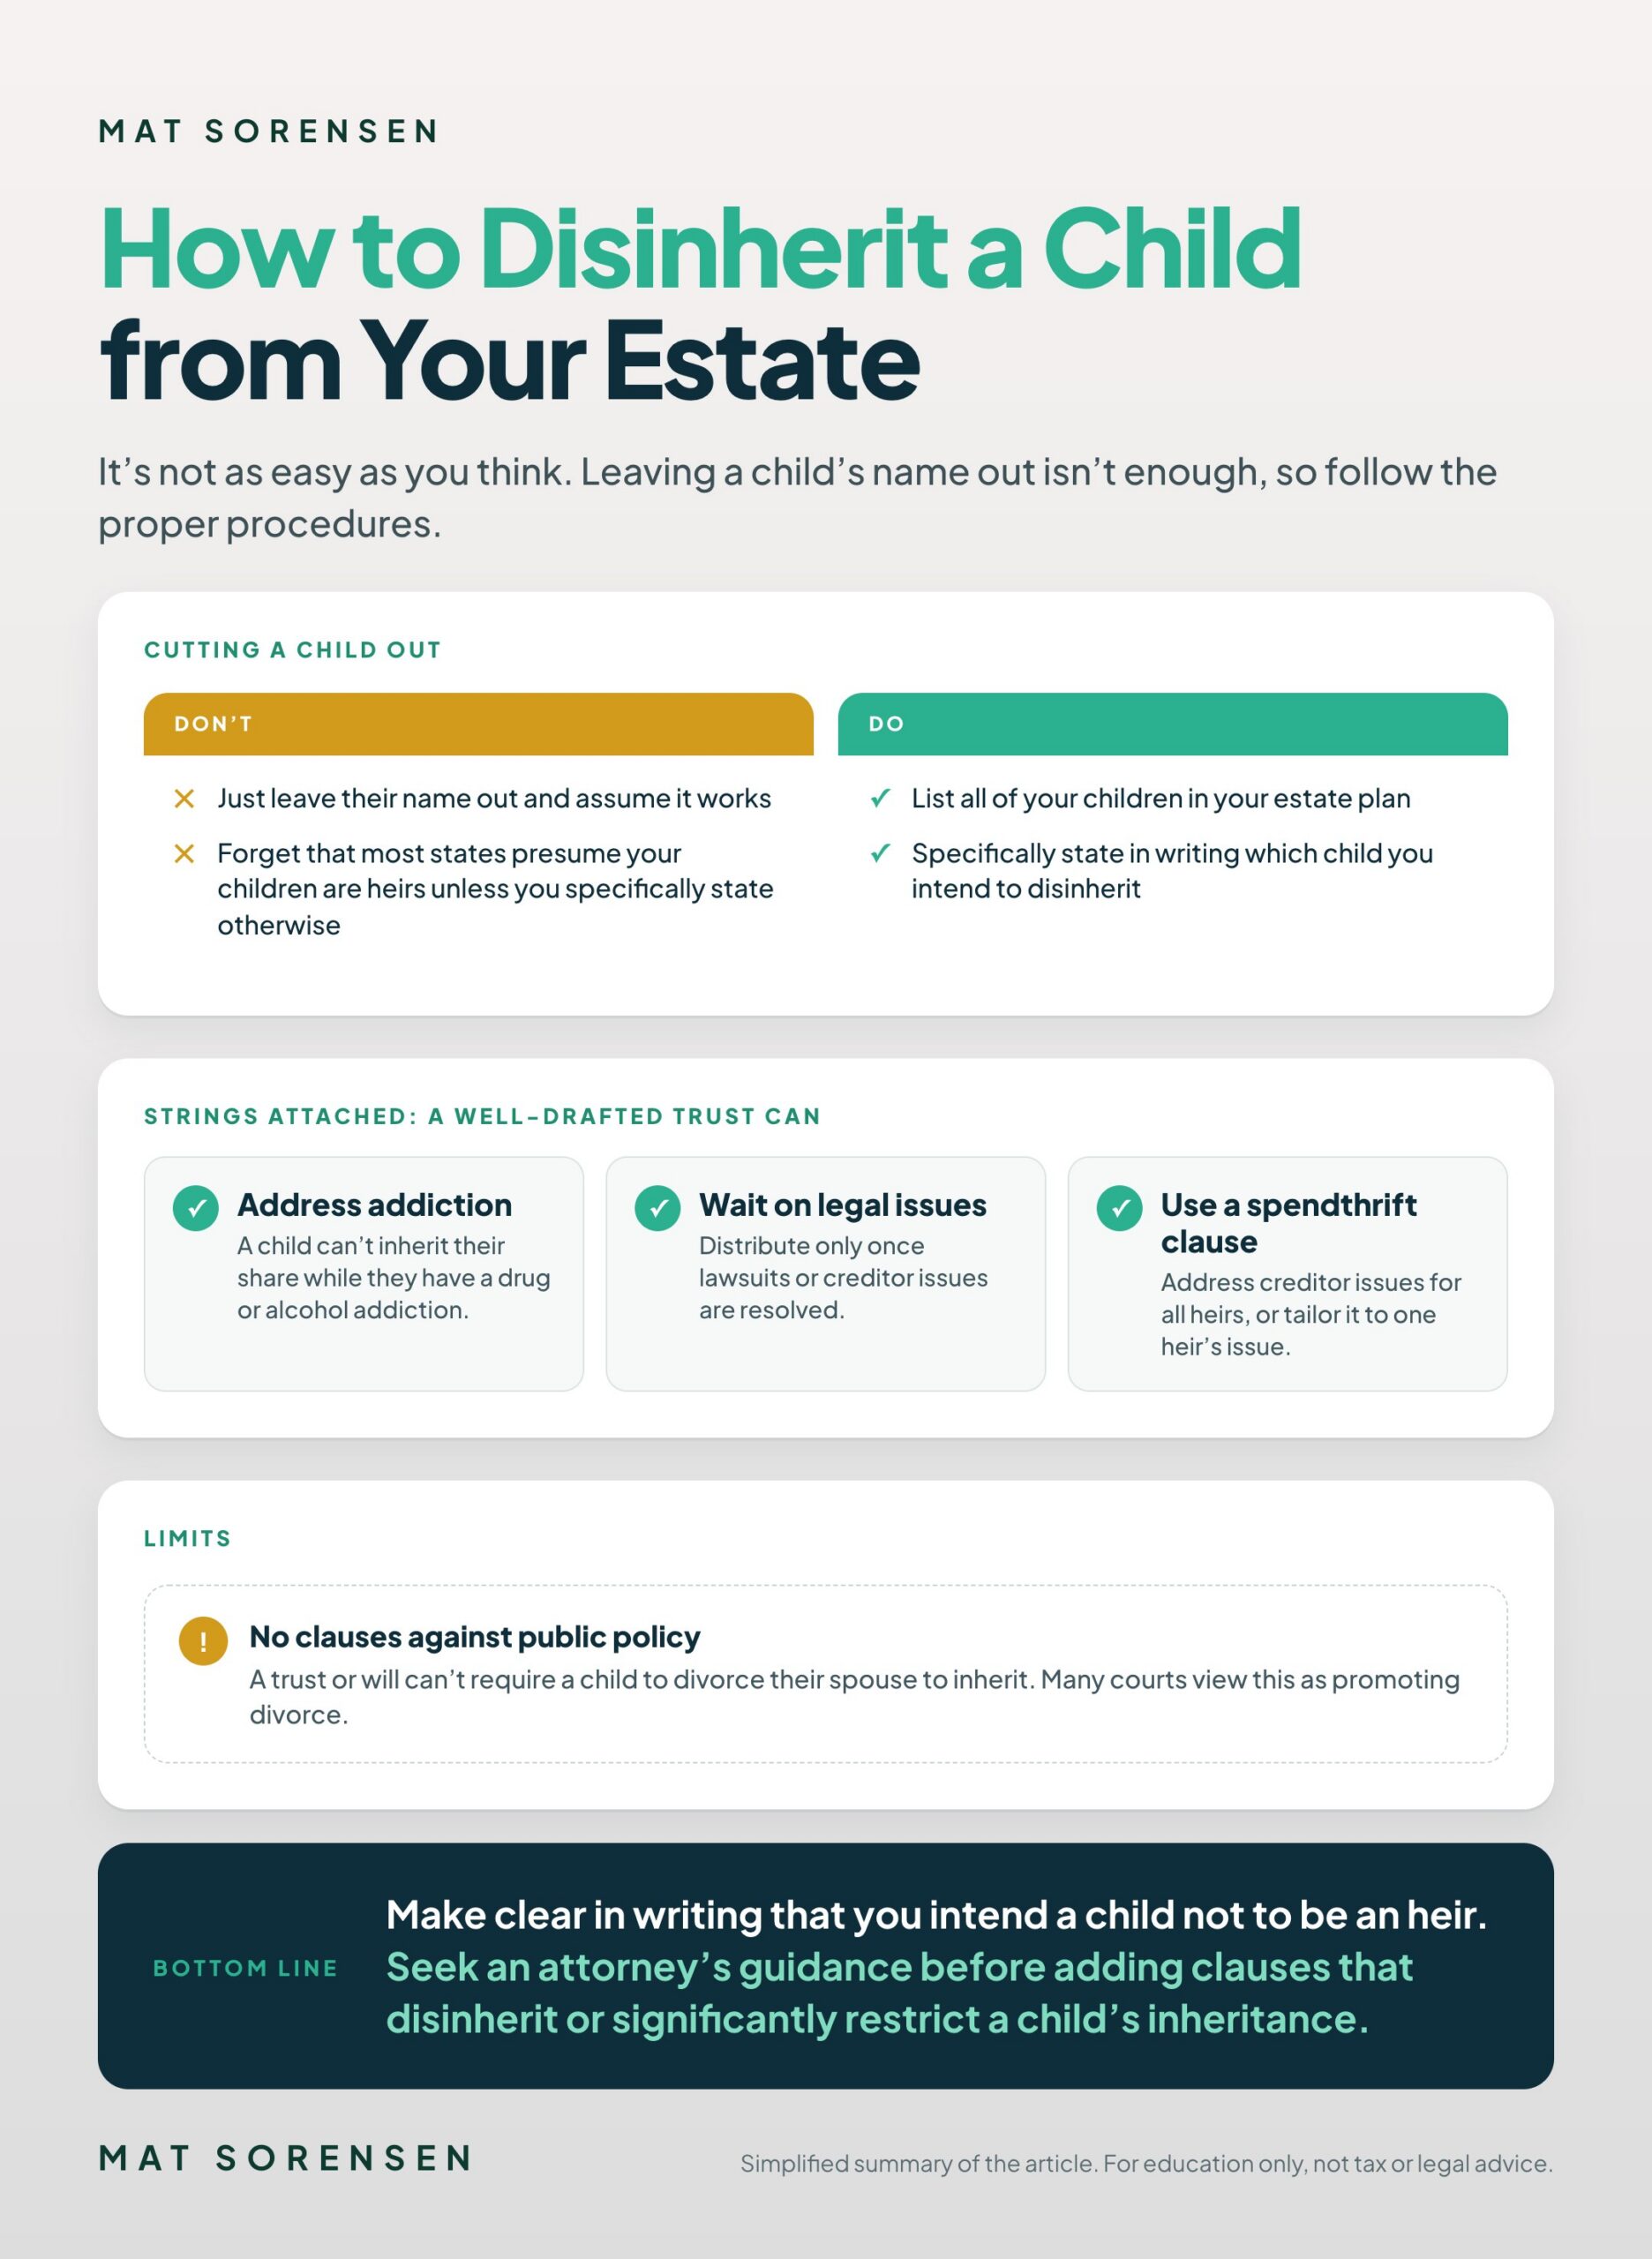
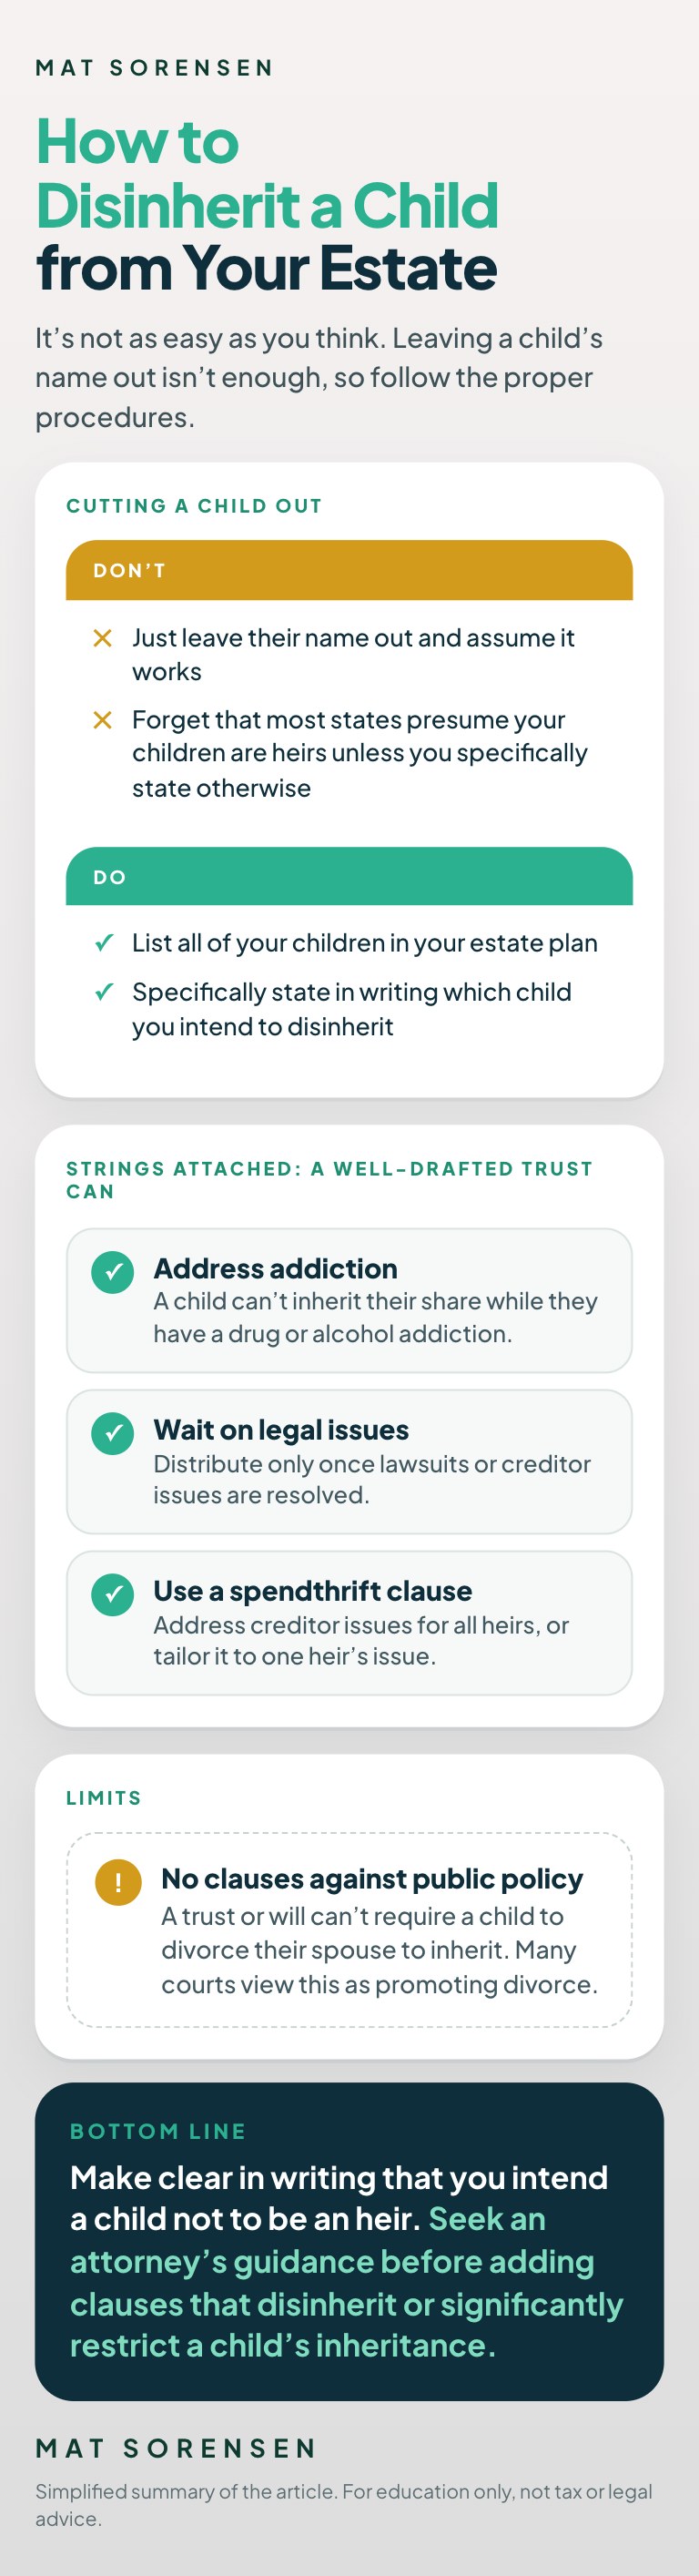
Infographic: how to properly disinherit a child, trust restrictions you can add for a problem child, and clauses courts will not enforce

Your children, along with your spouse (if you have one), are the presumed heirs to your estate by law in the absence of an estate plan. As a result, it is important to complete an entire list of your children in the estate plan and to specifically mention any child who will not be an heir to your estate by stating something like, “it is the intention of the settlor (you) to disinherit the following child from the estate.” It’s that simple; just make clear writing indicating that you specifically intend them not to be an heir to your estate and they’re out.

Adding Strings Attached for a Problem Child

If you have a problem child who you still want to provide for but want some strings attached, you can add a lot of excellent restrictions and controls to the estate through a well drafted trust.

EXAMPLE

For example, you could state that the problem child can’t inherit their share of the estate if they have a drug or alcohol addiction. You could also be specific about something in their life. Say you had a child with legal issues or that has creditors chasing them down. You could state that the trust will only distribute once the child has resolved issues in their lawsuit or with creditors.

Many trusts will have a spendthrift clause that addresses creditor issues for all heirs but you can also make it specific to an issue an heir may have that you want resolved before they inherit.

Clauses a Court Won’t Enforce

WATCH OUT

It is important to note that a trust (or will) cannot be created and enforced to go against public policy, promote illegal activities, and promote tortious acts. One of the common problematic clauses is one which requires a child to divorce their spouse in order for them to receive their inheritance. For example, you can’t say, “Johnny doesn’t get anything from the estate so long as he is married to Susie”. Many courts view this as a violation of public policy as it promotes divorce. As a result, avoid clauses such as these and seek the guidance of an attorney when adding clauses which disinherit or significantly restrict a child’s inheritance.

If you completed your estate plan but now you’d like to disinherit a problem child from your estate, consider having a lawyer review your documents. Or, if you know you are in need of a new plan, visit our website to learn more about our Estate Planning Special or simply to set-up an appointment with an Attorney at www.kkoslawyers.com

Contract Hand-offs

From my article on Realtor Magazine

Mat Sorensen’s Contract Hand-offs article in Realtor Magazine

Investors eyeing foreclosures and other residential properties to flip often connect with other investors looking for opportunities in the single-family rental market. Contract assignments are a common tool in these kinds of transactions because they enable investors to get a property under contract quickly and, rather than assume the risk that comes with turning it into a long-term investment, turn it over to an end buyer before closing in exchange for a fee.

Read the article at Realtor Magazine here.