California Rollover IRAs Can Receive ERISA-Style Creditor Protection

Have you rolled over your 401(K) plan or other employer based plan to a rollover IRA? Has someone told you that your rollover IRA in California isn’t protected from creditors. They’re wrong.
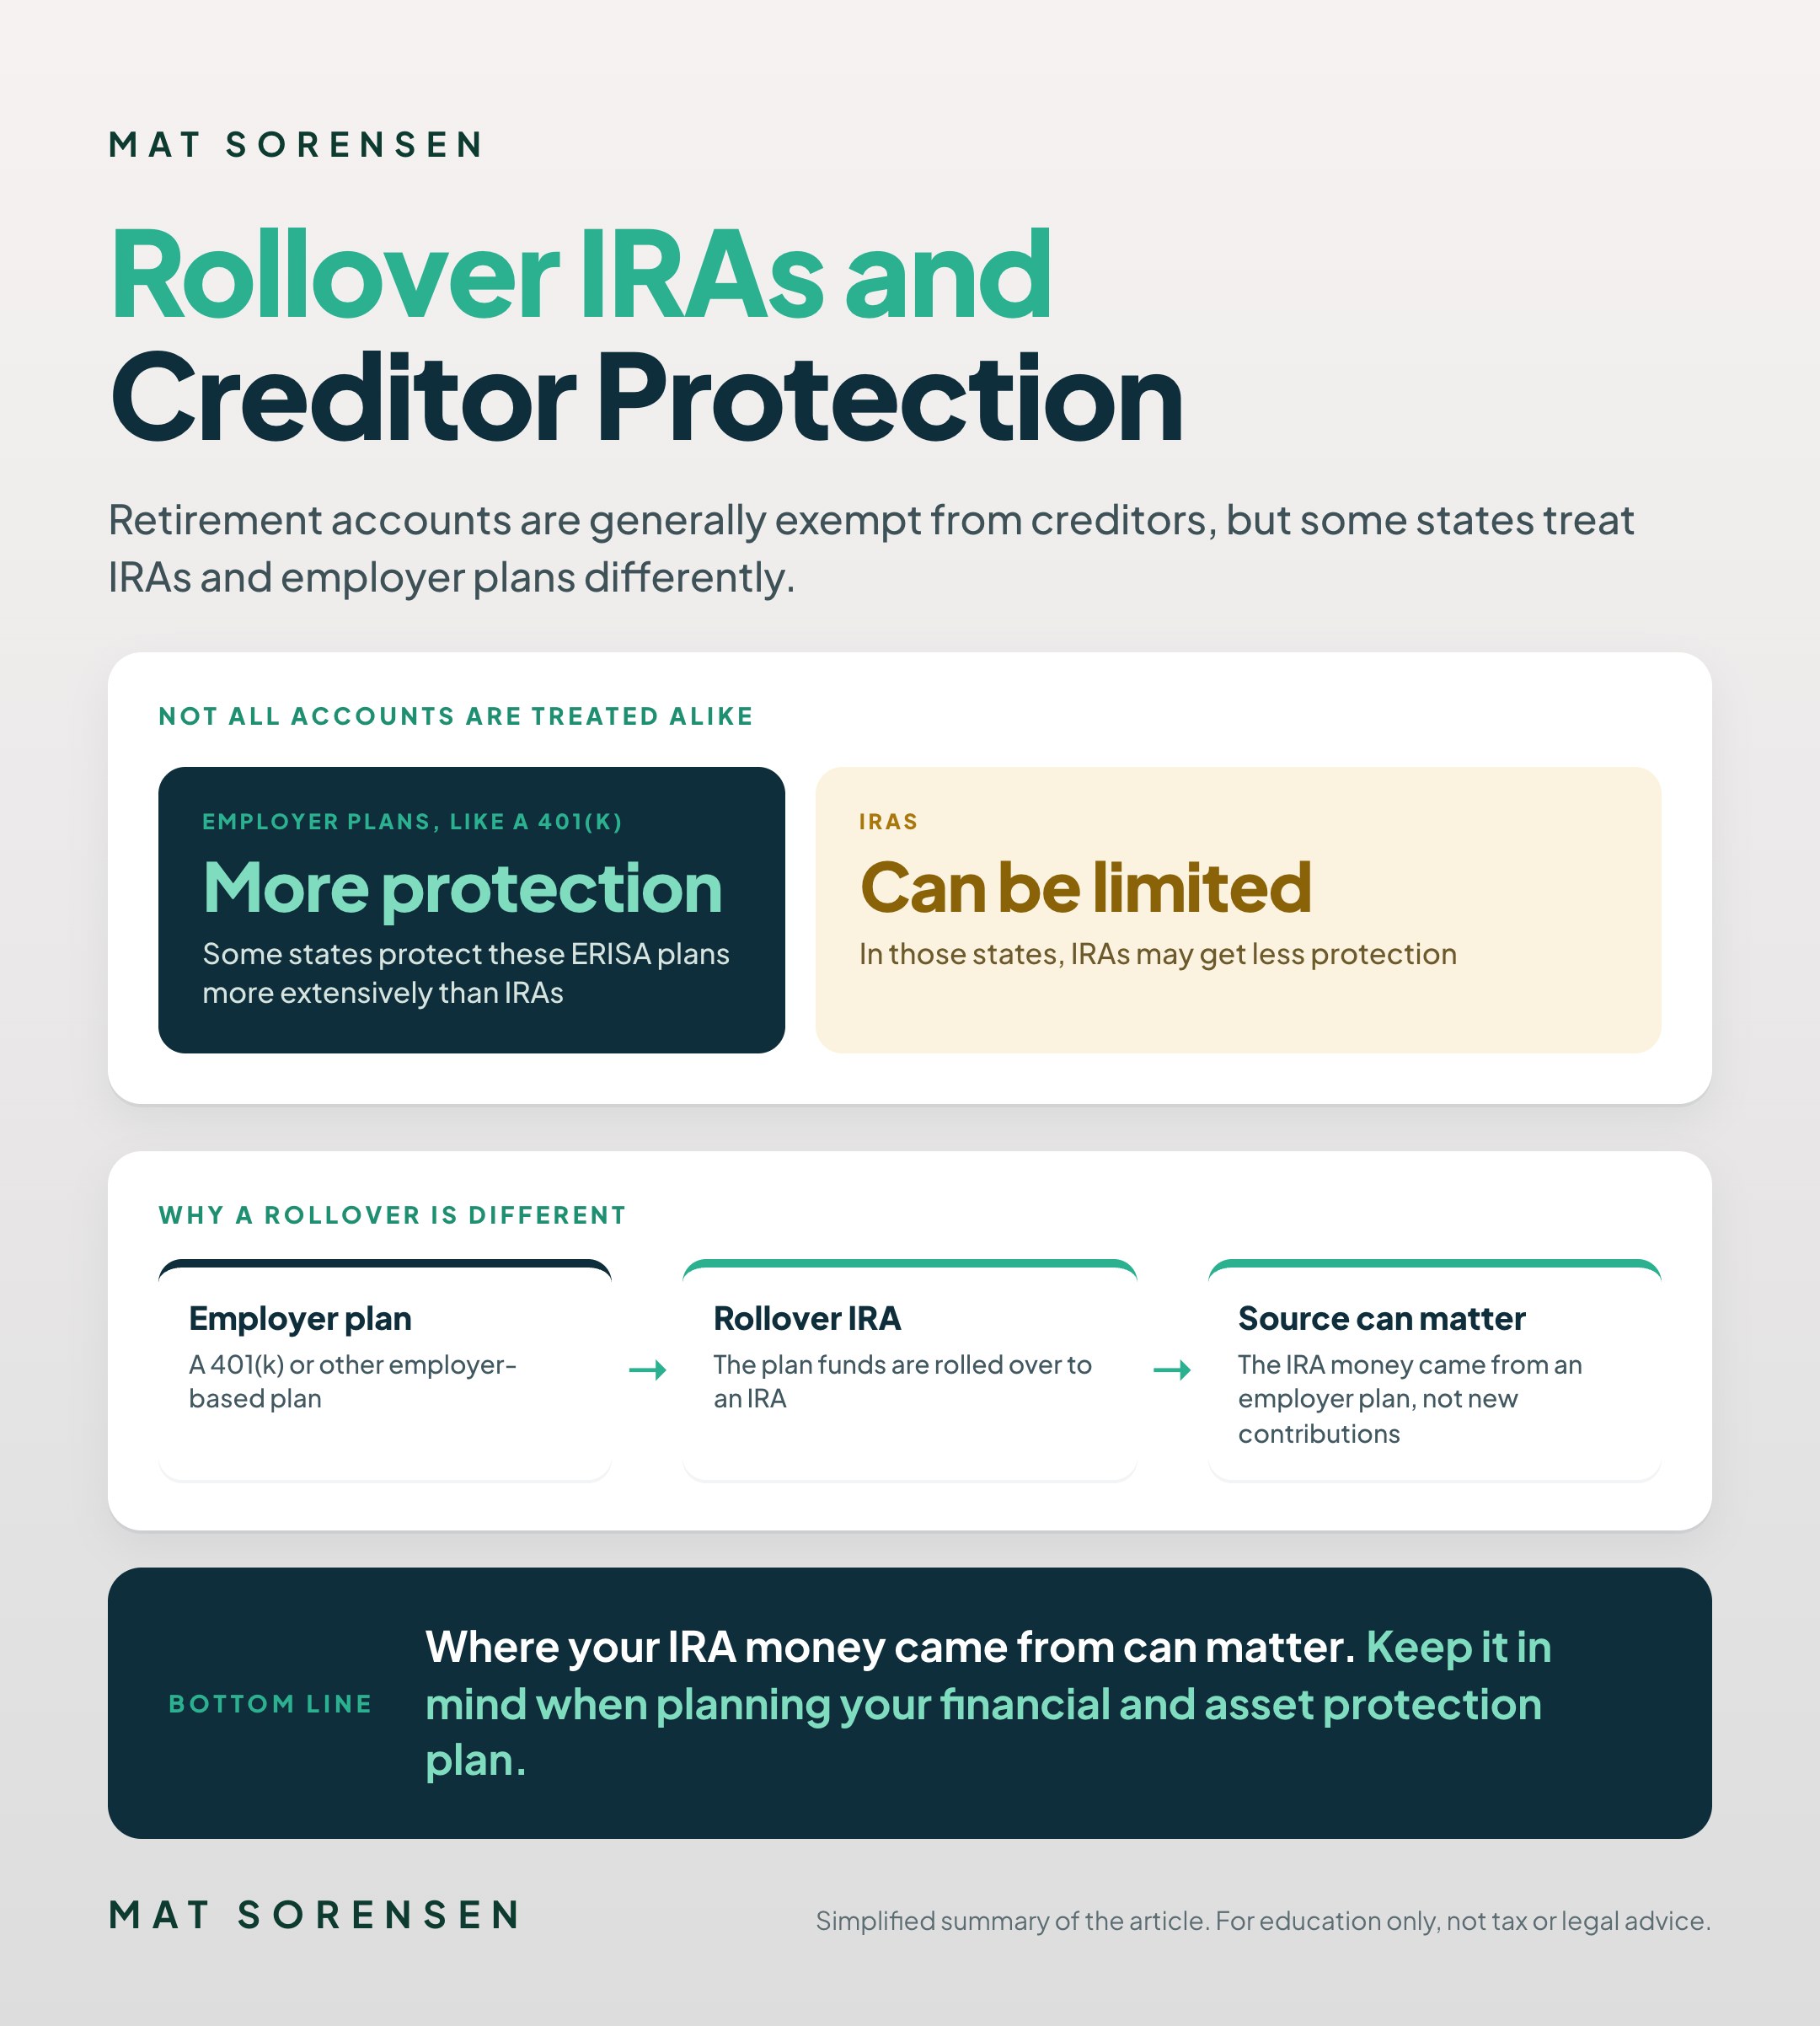
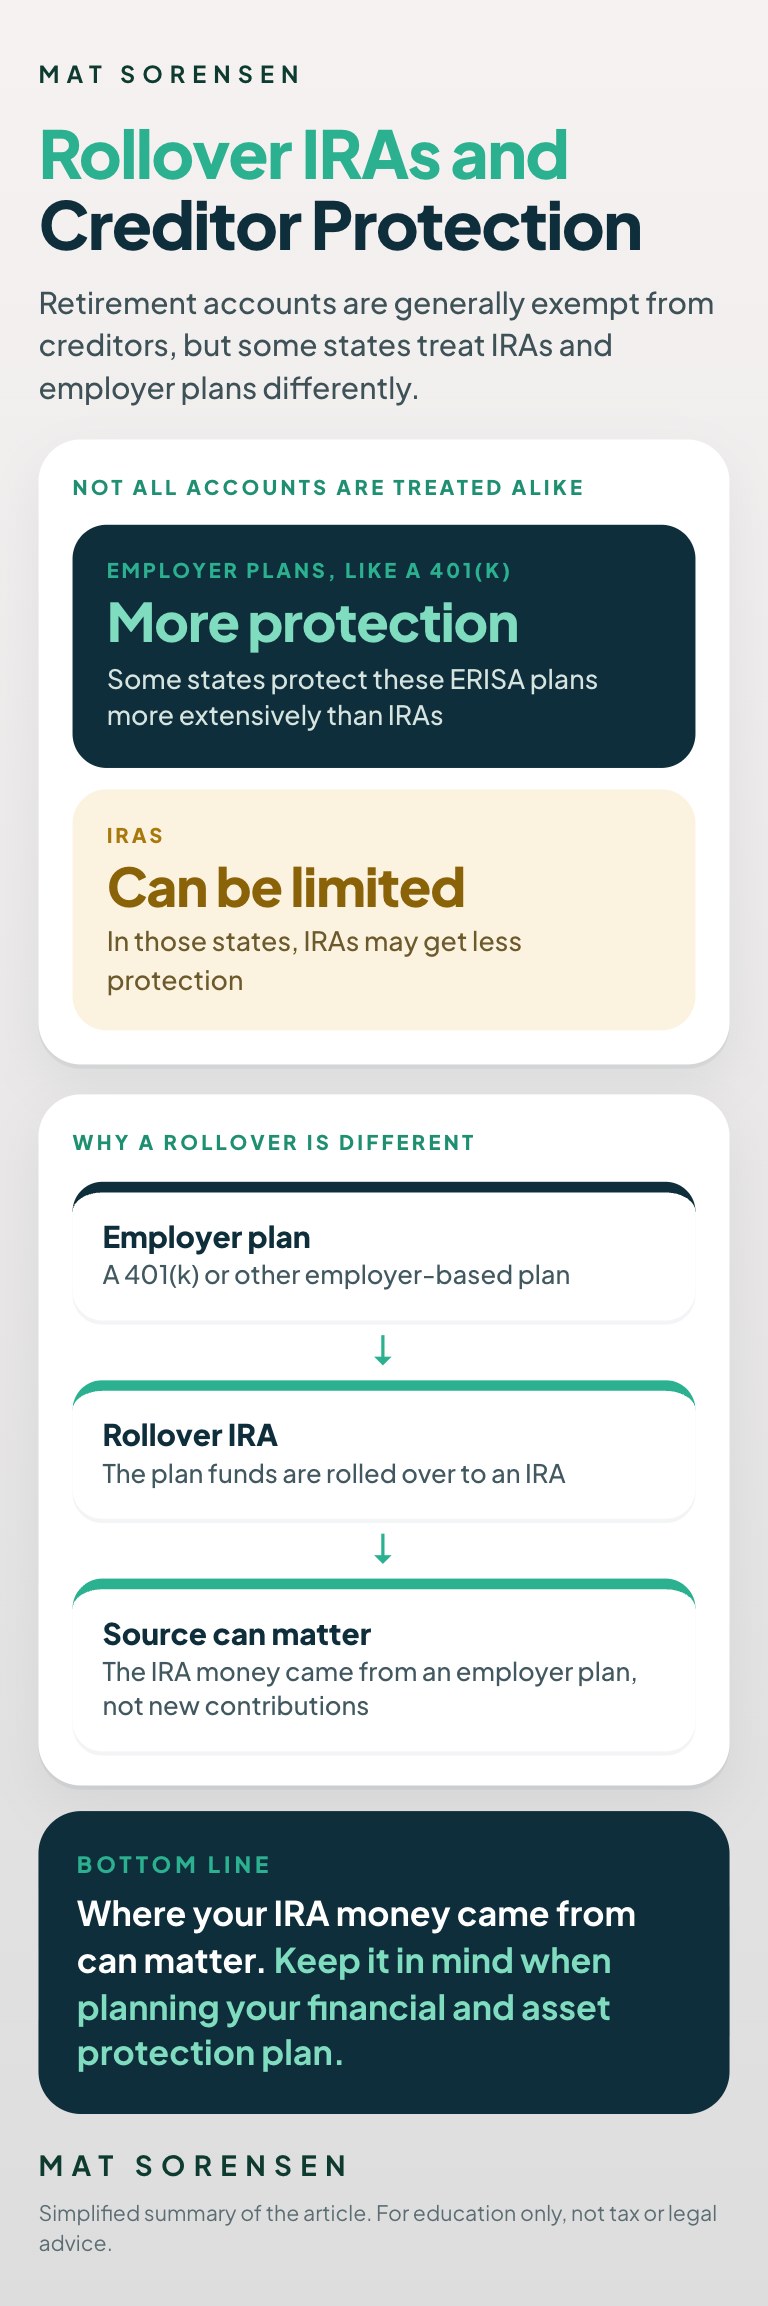
Infographic: retirement accounts are generally exempt from creditors, but some states protect employer plans like a 401(k) more than IRAs, and a rollover IRA holds money that came from an employer plan

California Exemptions

Retirement plans are known for being great places to build wealth and they have numerous tax and legal advantages. One of the key benefits of building wealth in a retirement account is that those funds are generally exempt from creditors. However, some states have laws that protect employer based retirement plans (aka, ERISA Plans) more extensively than IRAs. California is one of those states as their laws treat IRAs and ERISA based plans differently (the California Code refers to ERISA based plans, such 401(k)s, as private retirement plans) .

California Code of Civ. Proc., § 704.115, subds. (b),(d), treats funds held in a private retirement plan as fully exempt from collection by creditors. “Private retirement plans” include in their definition “profit-sharing” plans. The most common type of profit sharing plan is commonly known as a 401(k) plan.

IRAs, on the other hand, are only exempt from creditors up to an amount “necessary to provide for the support of the … [IRA owner, their spouse and dependents] … taking into account all resources that are likely to be available…” In other words, the exemption protection for IRAs is “limited”. California Code of Civ. Proc., § 704.115, subdivision (e).

McMullen v. Haycock

Notwithstanding the limited creditor protections for IRAs outlined above, the California Court of Appeal has ruled that rollover IRAs funded from “private retirement plans” receive full creditor protection as if they were a fully protected private retirement plan under California law. McMullen v. Haycock, 54 Cal.Rptr.3d 660 (2007). In McMullen v. Haycock, McMullen had a judgement against Haycock for over $500,000.  McMullen attempted to get a writ of execution against Haycock’s IRA at Charles Schwab. In defending against the writ of execution, Haycock claimed that the entire IRA was a rollover IRA funded and traceable to a private retirement plan and thus fully protected from collection as a private retirement plan. Haycock relied on California Code of Civ. Proc., § 703.80, which allows for the tracing of funds for purposes of applying exemptions.

Haycock lost at the trial court level but appealed and the appellate court found in his favor and ruled that his rollover IRA was fully protected from the collection of creditors as the funds in the rollover IRA were traceable to a fully exempt private retirement plan (e.g. former employer’s 401(k) plan).

As a result of McMullen v. Haycock, California IRA owners whose IRAs consist entirely of funds rolled over from a private retirement plan of an employer are fully protected from the collection efforts of creditors. IRAs that consist of individual contributions and are not funded from a prior employer plan rollover will only receive limited creditor protection. It is unclear so far how an IRA would be treated that consists of both private retirement plan rollover funds and new IRA contributions. Presumably, the Courts will trace the funds and separate out the private retirement plan rollover IRA portions from the regular IRA contributions and the regular IRA contributions would then receive the limited protection. Unfortunately, there is no case law or guidance yet as to rollover IRAs with mixed rollover and regular IRA contributions.

McMullen v. Haycock was a big win for IRA owners with funds rolled over from a private retirement plan and one that should be kept in mind when planning your financial and asset protection plan.

FREE ROLLOVER GUIDE

Learn how to move an old 401(k) or IRA into a self-directed IRA, tax-free.

Get the Free Transfers & Rollovers Guide

Prefer to talk it through? Book a call with a Directed IRA specialist
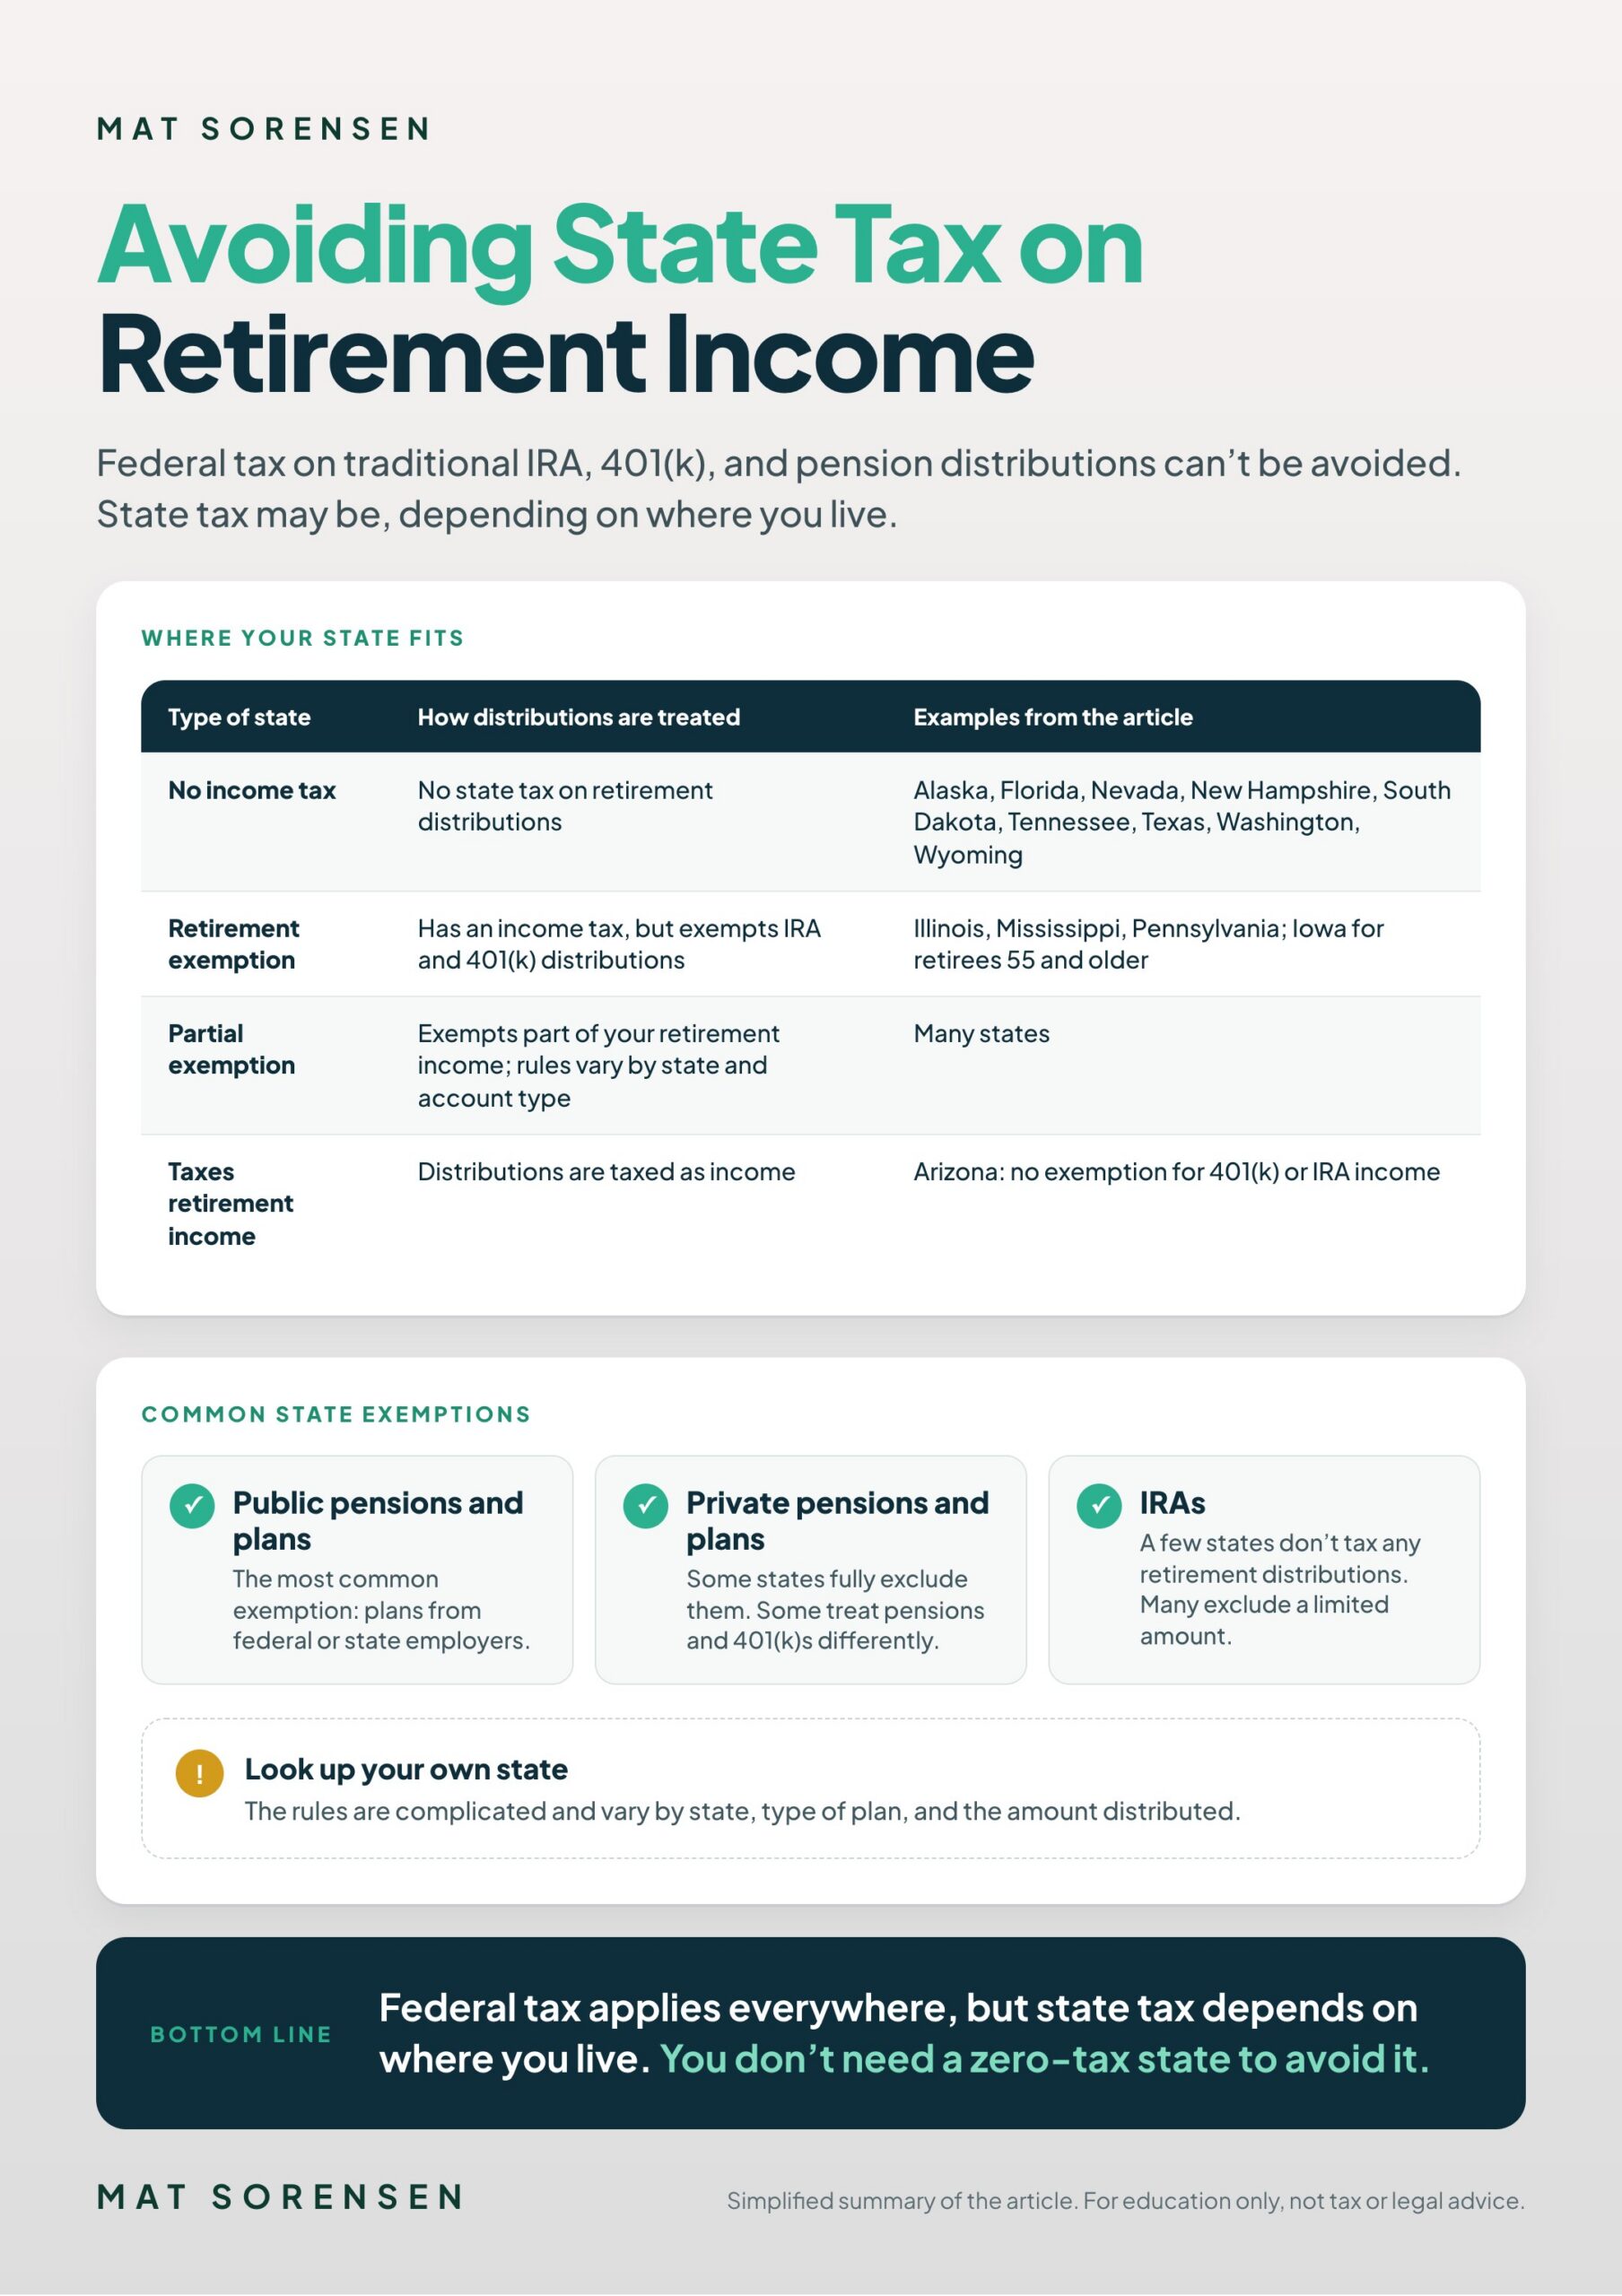
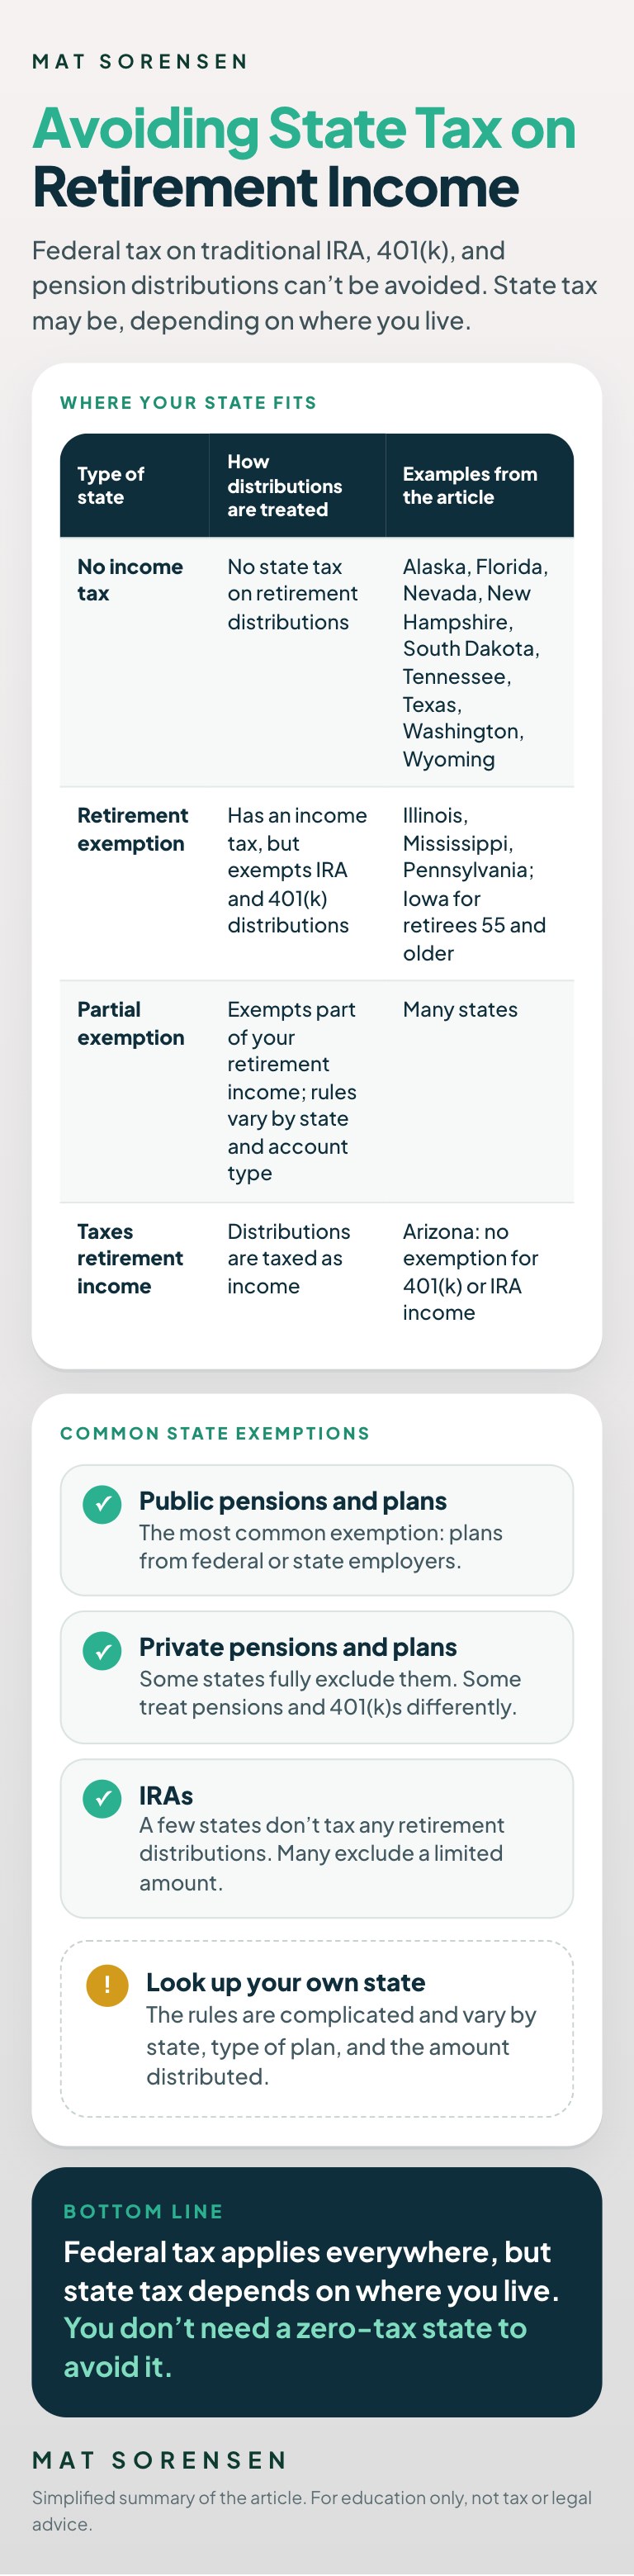
Avoiding State Income Tax on Retirement Plan Distributions

When a retiree begins taking distributions from a traditional IRA, 401(k), or pension plan, those distributions are taxable to the retiree under federal income tax and any applicable state income tax rules. While federal taxation cannot be avoided, state taxation may be avoided depending on your state of residency. In general, there are some states that have zero income tax and therefore don’t tax retirement plan distributions, some states that have special exemptions for retirement plan distributions, and other states that do in fact tax retirement plan distributions. This article breaks down the basics and discusses some of the states where income taxes can be avoided.

Infographic: how no-income-tax states, retirement exemption states, and taxing states treat IRA, 401(k), and pension distributions, plus common state exemptions

The No State Income Tax States

First, the easiest way to avoid state income tax on retirement plan distributions is to establish residency in a state that has no state income tax. It isn’t just the fun and sun of Florida that helps attract all of those retirees. It’s the tax-free state treatment of all that money stocked away in your retirement account. As of 2026, nine states have no income tax on wages or retirement distributions: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming.

States with Retirement Income Exclusions

Second, some states have an income tax but exempt retirement plan distributions. In 2026, Illinois, Mississippi, and Pennsylvania exempt IRA and 401(k) distributions, and Iowa exempts them for retirees 55 and older. Many other states exempt part of your retirement income, and the rules vary by state and by type of account. Here’s a quick summary of the common exemptions found in the states.

  1. 1For Public Pensions and Retirement Plans. Distributions from federal or state employer plans are exempt from taxation in many states. This is the most common exemption amongst states that have an income tax but who exempt some types of retirement plan distributions from income. Most of the states that have an exemption for retirement plan income provide an exemption for public employee pensions and retirement plans.
  2. 2For Private Pensions and Retirement Plans. Some states offer a full exclusion for private pensions and retirement plans. Some of them differ between pension and contributory plans (e.g. 401(k)) and some of them make no distinction. Pennsylvania, for example, excludes all income distributions. Hawaii excludes certain distributions from state income tax for private retirement plans and for portions from company plans rolled over to a rollover IRA and then distributed from the rollover IRA.
  3. 3For IRAs. There are some states that do not tax any retirement plan distributions, including IRA distributions to retirees. Illinois for example does not tax distributions from retirement plans at all (pensions, IRAs, 401(k)s). There are also numerous states that exclude a certain limit of retirement plan income from taxation.

Know Your State’s Rules

In sum, the state tax rules for retirement plan distributions are complicated and vary significantly. Each state can be understood rather quickly though and everyone planning for retirement should understand how state income taxes may eat into their planned retirement plan distributions.

EXAMPLE

I, for example, looked into Arizona and found that there is no exemption for 401(k) or IRA income in the state of Arizona. While we do have a low state income tax rate, Arizona state income tax includes income from private retirement plans (pensions and 401(k)s) and IRAs and has a modest deduction for distributions from public retirement plans.

Each state is unique to the type of plan, and the amounts being distributed but don’t just think you need to be in a state with zero income tax to avoid taxes on retirement plan distributions. For example, you could be in Illinois, Tennessee, or New Hampshire and could realize state income tax-free distributions of your IRA or 401(k).  The National Conference of State Legislators has an updated 2015 chart that is very useful and can be used to look up your state’s tax treatment of retirement plan distributions for retirees.

FREE SELF-DIRECTED IRA GUIDE

Learn how to invest your IRA in real estate, private companies, notes, precious metals, and more.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist
IRS Announces 2015 Retirement Plan Contribution Limits

The IRS recently announced 2015 retirement plan contributions limits. Despite the typical bad news coming from the IRS, this year we see increases in HSA and 401(k) contributions for 2015. Here’s a quick breakdown on the changes.

– IRA contribution limitations (roth and traditional) stayed at $5,500 with an additional $1,000 catch-up amount for those 50 and older.

– HSAs contribution limits increased ($50 indiv/$100 fam) from $3,300 individual and $6,550 family to $3,350 individual and $6,650 family.

– 401(k) contributions also increased on the employee and employer side. Employee contribution limitations increased from $17,500 to $18,000 for 2015. Also, the additional catch-up contribution for those 50 and older increased from $5,500 to $6,000. The annual maximum 401(k) (defined contribution) total contribution amount increased from $52,000 to $53,000 ($59,000 for those 50 and older).

There were additional modest increases to defined benefit plans and to certain income phase-out rules. Please refer to the IRS announcement for more details here.

All of these accounts provide tax advantageous ways for an individual to either save for retirement or to pay for their medical expenses. If you’re looking for tax deductions, you should determine which of these accounts is best for you. Keep in mind there are qualification and phase out rules that apply so make sure you are getting competent advice about which accounts should be set up in your specific situation.

By: Mat Sorensen, Attorney & Author of The Self Directed IRA Handbook

401(k) Contributions from S-Corp Income

A properly structured s-corporation is utilized best when business owners adopt and contribute to a 401(k) plan. Whether the business has only one owner/employee (or spouses only) or whether the business has dozens or even hundreds of employees. Simply put, a 401(k) plan can be used as a tool for putting the income of the business owner (any applicable employees) away for retirement with the added benefit of a tax deduction for every dollar that can be contributed. There are so many neat things about 401(k) plans and there are so many options.  For example, you can do Roth 401(k) plans, you can self direct a 401(k) plan, and you can even loan money to yourself from your 401(k) account. While books have been written about all of these options and benefits, one of the most misunderstood concepts of 401(k) plans is how s-corporation owners can contribute their income to the plan. That is the focus of this article.

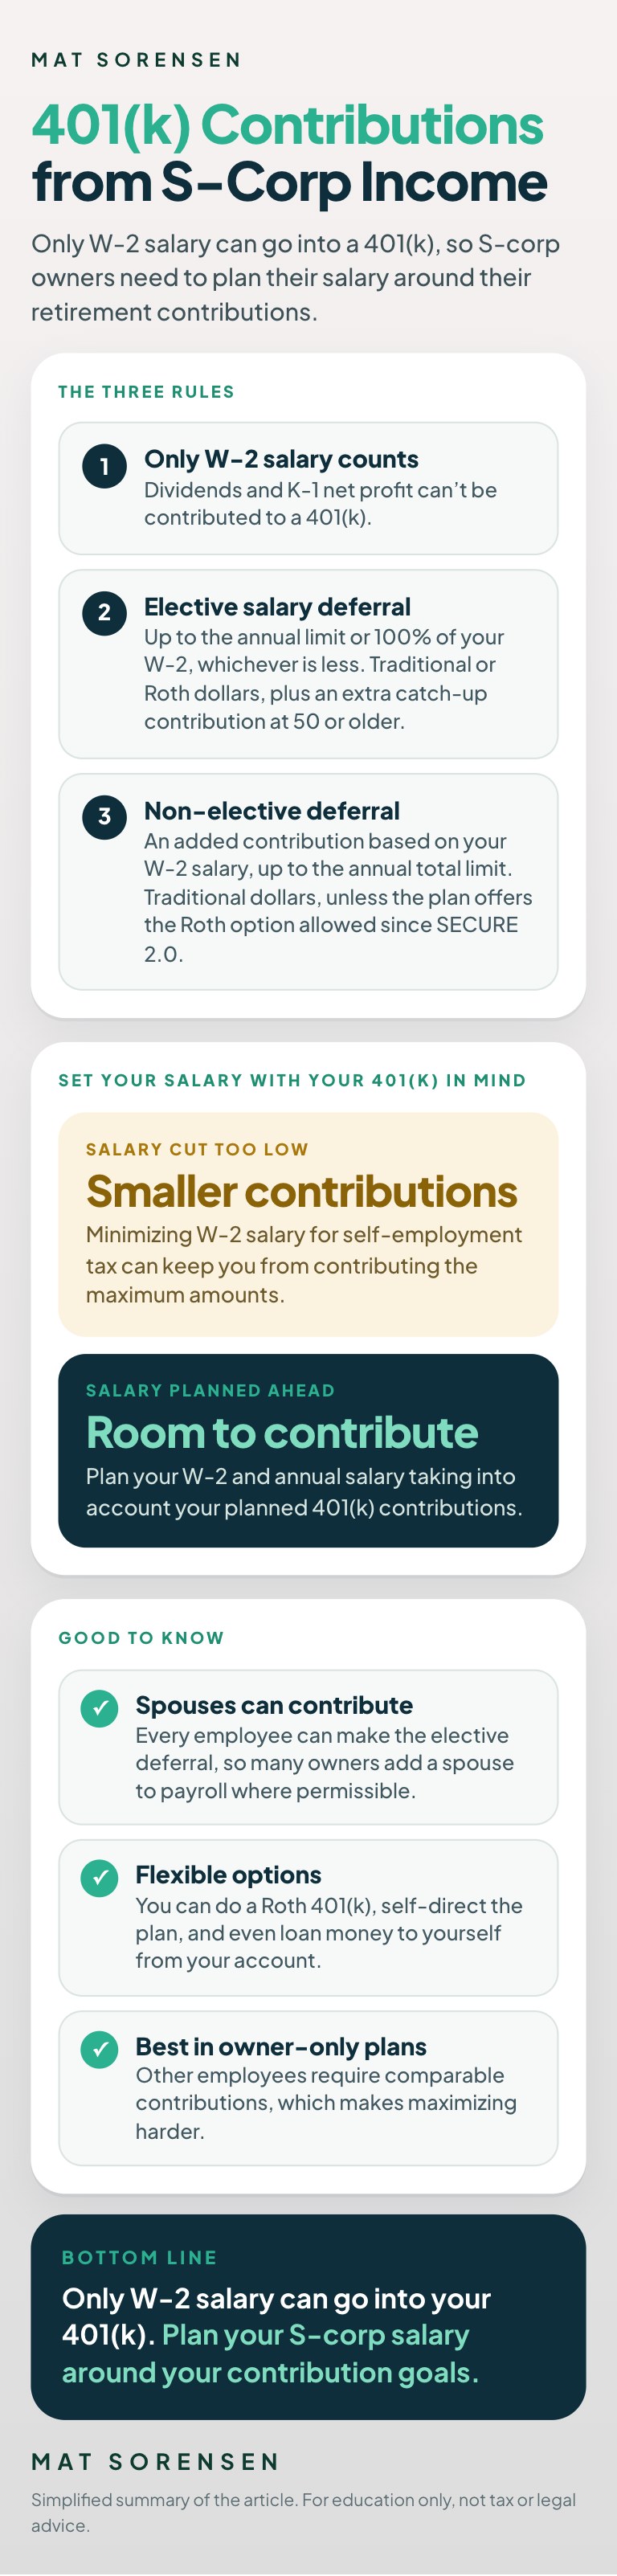
Infographic: the three rules for making 401(k) contributions from S-corporation income and why S-corp owners should plan their W-2 salary

Rules for 401(k) Contribution

In order to understand how s-corporations income can be contributed to a 401(k) plan, you need to understand the following three basic rules:

  1. 1Only W-2 Salary Income can be Contributed to a 401(k). You cannot make 401(k) contributions from dividend or net profit income that goes on your K-1. See IRS.gov for more details. Since many s-corporation owners seek to minimize their W-2 salary for self-employment tax purposes, you must carefully plan your W-2 and annual salary taking into account your annual planned 401(k) contributions. In other words, if you cut the salary too low you won’t be able to contribute the maximum amounts. On the other hand, even with a low W-2 Salary from the s-corporation you’ll still be able to make excellent annual contributions to the 401(k) (up to $17,500 if you have at least that much in annual W-2 salary).
  2. 2Easy Elective Salary Deferral Limit of $17,500 or 100% of Your W-2, whichever is less. If you have at least $17,500 of salary income from the s-corporation, you can contribute $17,500 to your 401(k) account.  Every employee under the plan is allowed to make this same contribution amount. As a result, many spouses are added to the s-corporation’s payroll (where permissible) to make an additional $17,500 contribution for the spouse’s account. If you are 50 or older, you can make an additional $5,500 annual contribution.  Follow this link for the details from the IRS on the elective salary deferral limits. The elective salary deferral can be traditional dollars or Roth dollars.
  3. 3Non-Elective Deferral of 25% of Income Up to a $52,000 total Annual 401(k) Contribution. In addition to the $17,500 annual elective salary contribution, an s-corporation owner can contribute 25% of their salary compensation to their 401(k) account up to a maximum of a $52,000 total annual contribution.  This non-elective deferral is always made with traditional dollars and cannot be Roth dollars. So, for example, if you have an annual W-2 of $100,000, you’ll be able to contribute a maximum of $25,000 as a non-elective salary deferral to your 401(k) account. If you have employees who participate in the plan besides you (the business owner) and your spouse, then the non-elective deferral calculation gets much more complicated. But for now, let’s assume there are no other employees and run through the examples.

UPDATE (NOV 2026)

Since the SECURE 2.0 Act (2022), a 401(k) plan can let employees choose Roth treatment for employer matching and profit-sharing contributions (if fully vested); those contributions are taxable in the year they’re made. (Source: IRS Notice 2024-2)

Examples

Let’s run through two examples. The first is an s-corporation business owner looking to contribute around $30,000 per year. The second is a business owner looking to contribute the maximum of $52,000 a year.

EXAMPLE

Example 1: Seeking a $30,000 Annual Contribution.

S-Corporation Owner W-2 Salary = $50,000

Elective Salary Deferral = $17,500

25% of Salary Non-Elective Deferral = $12,500 (25% of $50,000)

Total Possible 401(k) Contribution = $30,000

EXAMPLE

Example 2: Seeking Maximum $52,000 Annual Contribution

S-Corporation Owner W-2 Salary = $138,000

Elective Salary Deferral = $17,500

25% of Salary Non-Elective Deferral = $34,500 (25% of  $138,000)

Total Possible 401(k) Contribution  (maximum) = $52,000

As a result of the calculations above, in order to contribute the maximum of $52,000, you need a W-2 salary from the s-corporation of $138,000. Keep in mind that if you have other employees in your business (other than owner and spouse) that you are required to do comparable matching on the 25% non-elective deferral and as a result such maximization is often difficult to accomplish in 401(k)s with employees other than the owner and their spouse. Consequently, the additional 25% non-elective salary deferral is best used in owner only 401(k) plans.

UPDATE (NOV 2026)

The rules and examples above use the limits from when this article was written. For 2026, the employee deferral limit is $24,500 ($32,500 at age 50+) and the total limit is $72,000. (Source: IRS)

FREE SOLO 401(K) GUIDE

Self-employed? Learn how a self-directed Solo 401(k) works and how much you can contribute.

Get the Free Solo 401(k) Guide

Prefer to talk it through? Book a call with a Directed IRA specialist