What is a Foreign LLC or Corporation, and When Do I Need to Register My Company in Another State?

Business owners and investors doing business in multiple states often ask the question of whether their company, that is set up in one state needs to be registered into the other state(s) where they are doing business. This registration from your state of incorporation/organization into another state where you also do business is called a foreign registration. For example, let’s say I’m a real estate investor in Arizona and end up buying a rental property in Florida. Do I need to register my Arizona LLC that I use to hold my real estate investments into Florida to take ownership of this property? The answer is generally yes, but after reviewing a few states laws on the subject I decided to outline the details of when you need to register your LLC or Corporation into another state where you are not incorporated/organized. (Please note that the issue of whether state taxes are owed outside of your home state when doing business in multiple states is a different analysis).

In analyzing whether you need to register your out of state company into a state where you do business or own property it is helpful to understand two things: First, what does the state I’m looking to do business in require of out of state companies; and Second, what is the penalty for failure to comply.
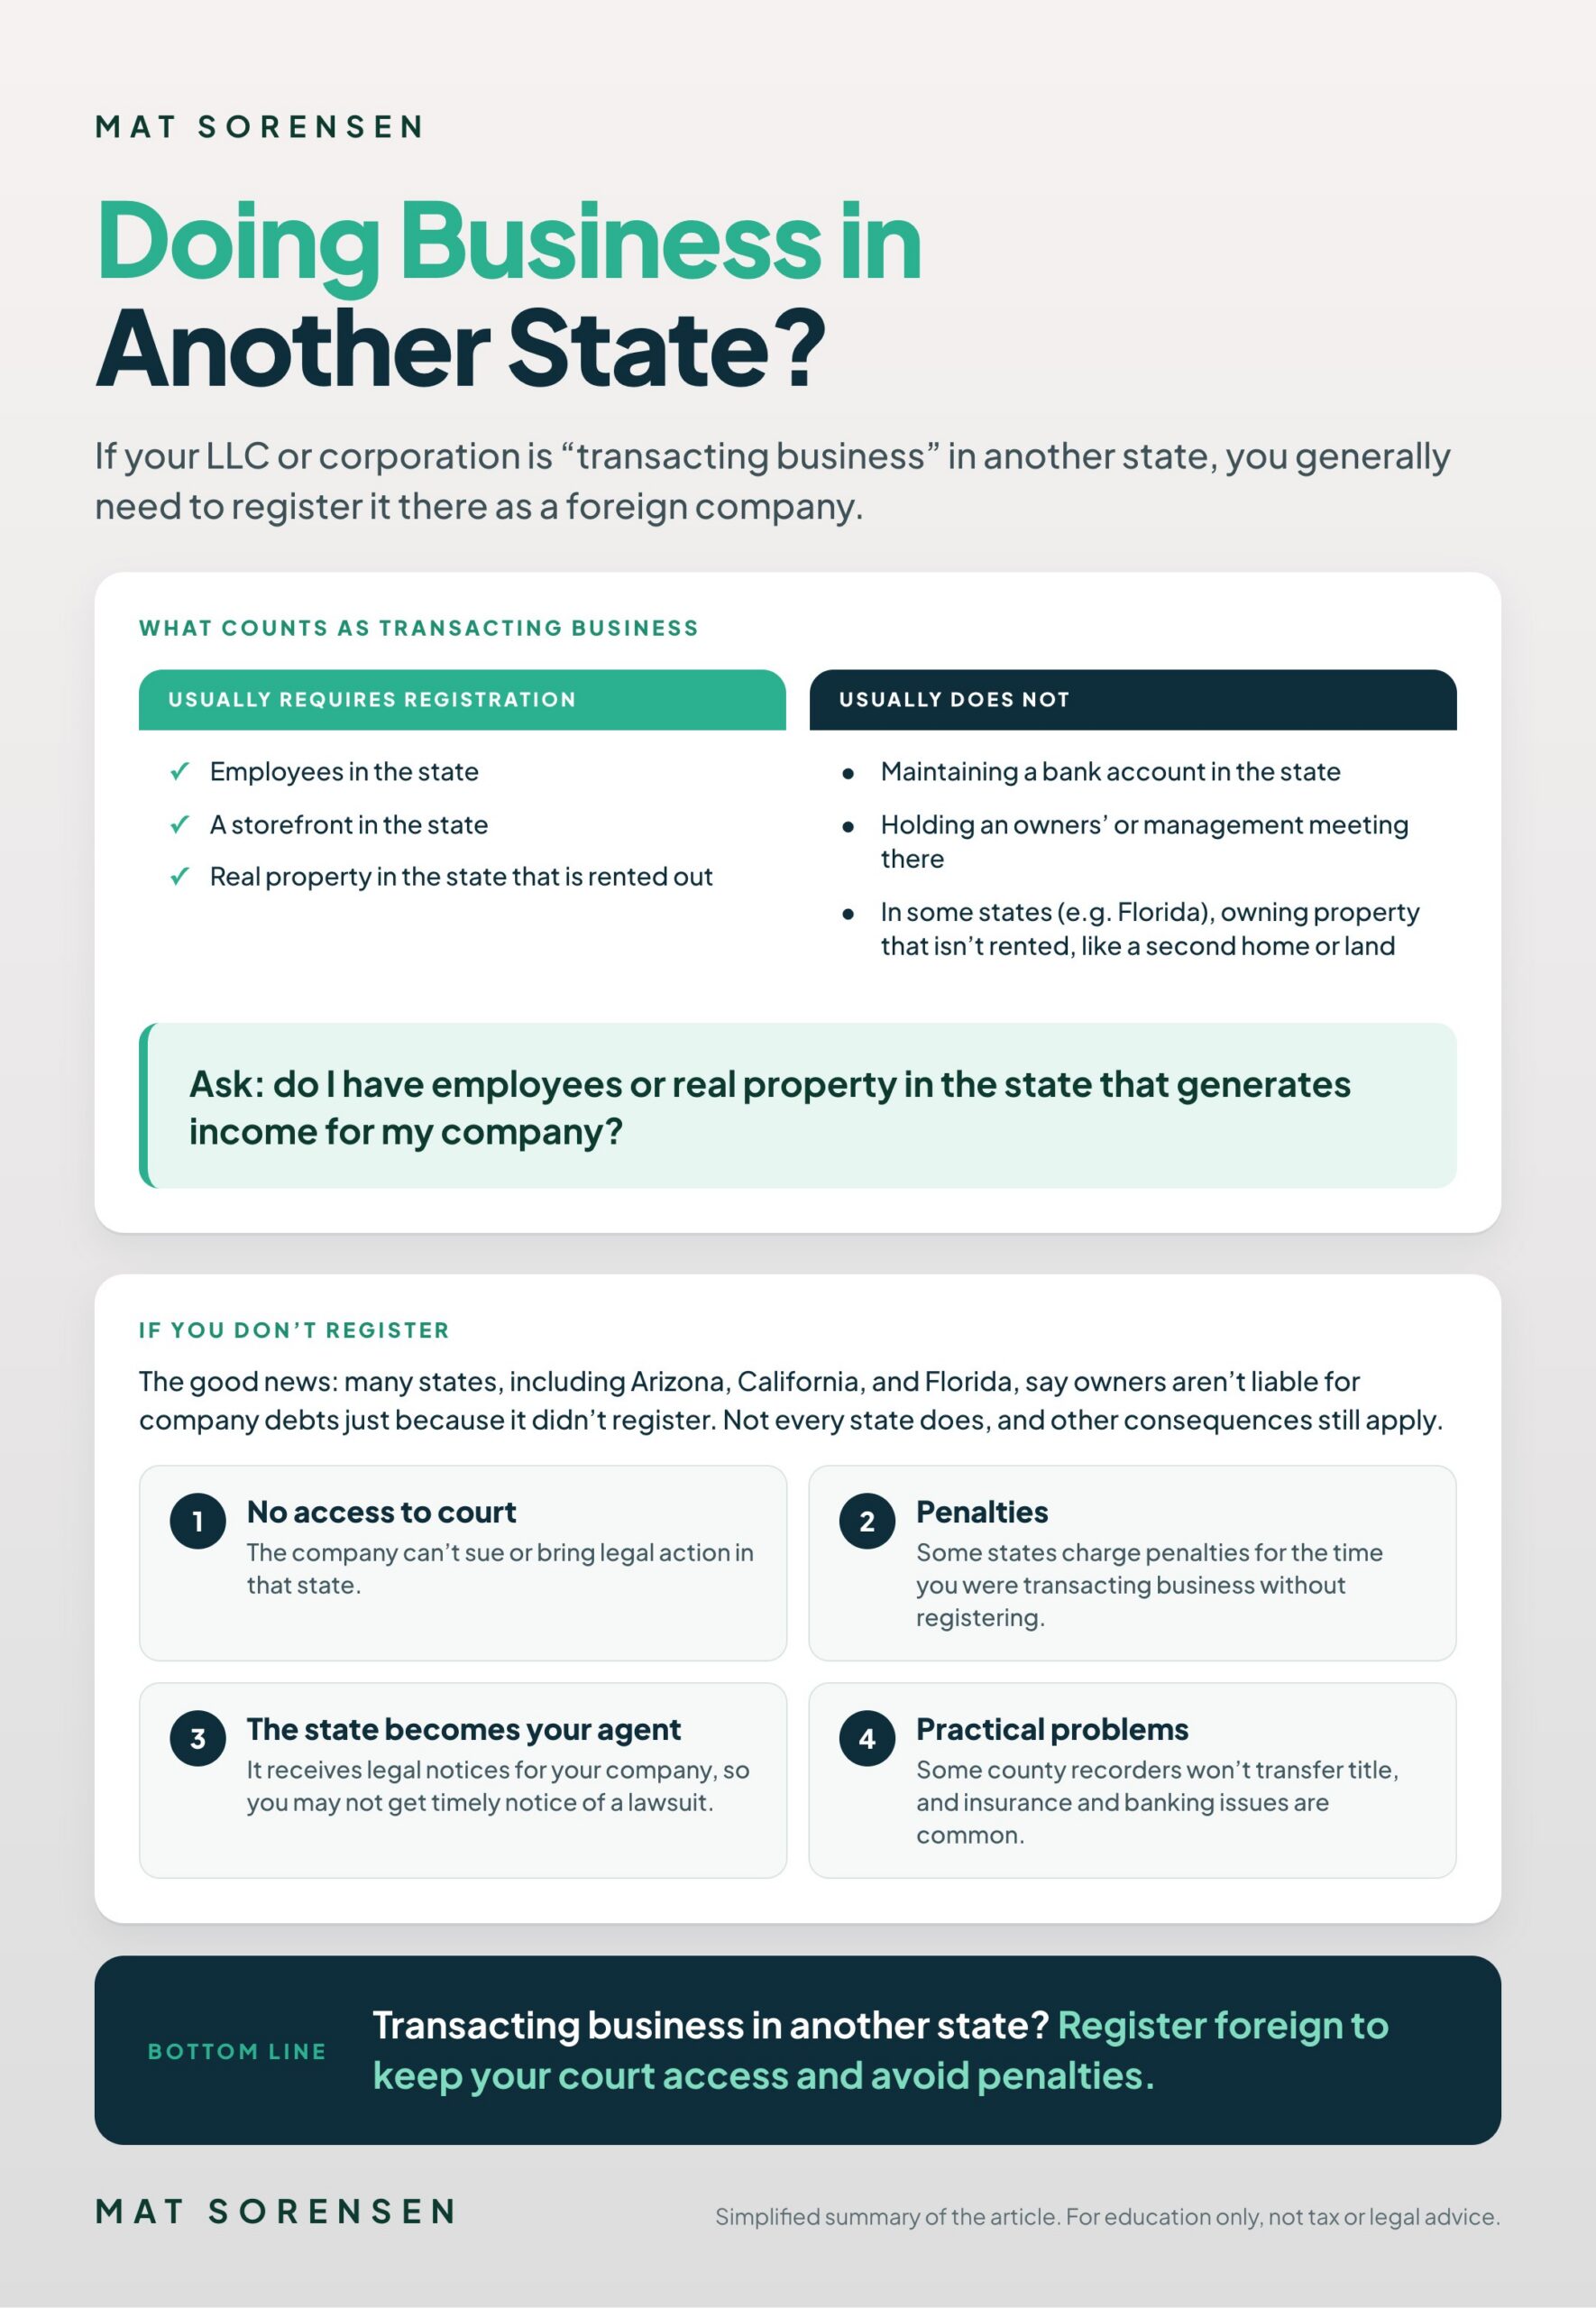
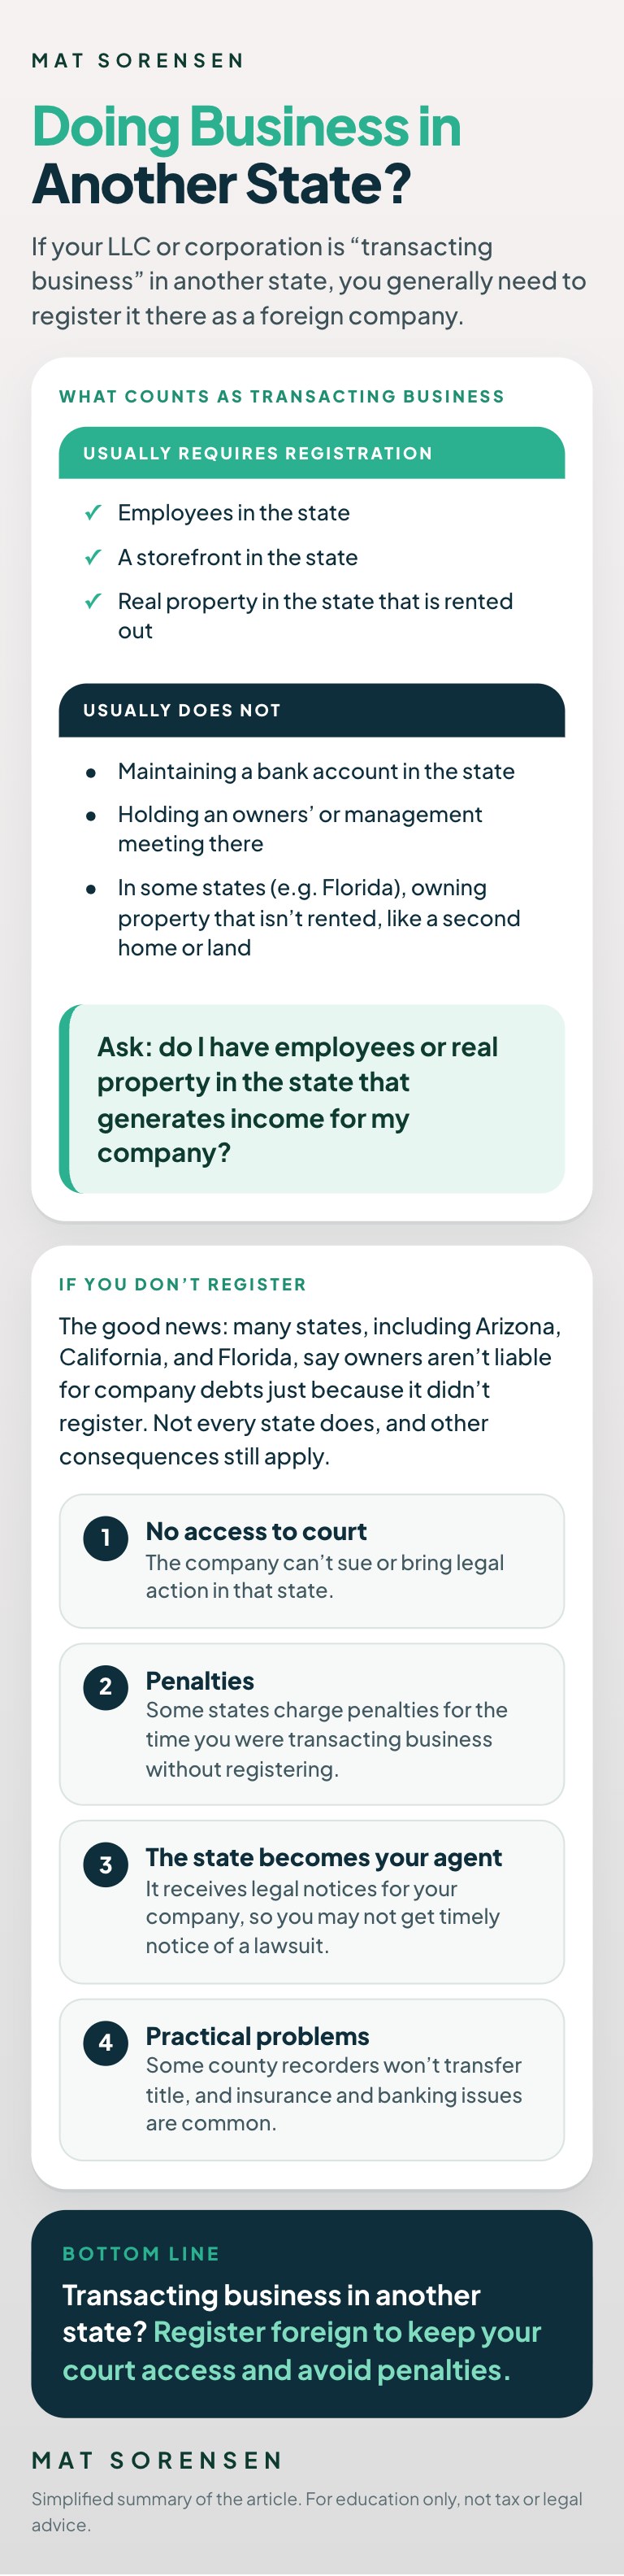
Infographic: what counts as transacting business in another state and what happens if an LLC or corporation fails to register as a foreign company

When Do I Need to Register Foreign?

First, a survey of a few state statutes on foreign registration of out of state companies shows that the typical requirement for when an out of state company must register foreign into another state is when the out of state company is deemed to be “transacting business” into the other state. So, the next question is what constitutes “transacting business”? The state laws vary on this but here are some examples of what constitutes “transacting business” for purposes of foreign registration filings.

  1. 1Employees or storefront located in the foreign registration state.
  2. 2Ownership of real property that is leased in the foreign registration state. Note that some states (e.g. Florida) state that ownership of property by an out of state LLC does not by itself require a foreign registration (e.g. a second home or maybe land) but if that property was rented then foreign registration is required.

Here is an example of what does not typically constitute “transacting business” for foreign registration requirements.

  1. 1Maintaining a bank account in the state in question.
  2. 2Holding a meeting of the owners or management in the state in question.

So, in summary, the general rule is that transacting business for foreign registration requirements occurs when you make a physical presence in the state that results in commerce. Ask, do I have employees or real property in the state in question that generates income for my company? If so, you probably need to register. If not, you probably don’t need to register foreign. Note that there are some nuances between states and I’ve tried to generalize what constitutes transacting business so check with your attorney or particular state laws when in question.

What is the Penalty if I Don’t Register Foreign?

Second, what is the penalty and consequence for failing to file a foreign registration when one was required? This issue had a few common characteristics among the states surveyed. Many company owners fear that they could lose the liability protection of the LLC or corporation for failing to file a foreign registration when they should have but most states have a provision in their laws that states something like the following, “A member [owner] of a foreign limited liability company is not liable for the debts and obligations of the foreign limited liability company solely by reason of its having transacted business in this state without registration.” A similar provision to this language was found in Arizona, California and Florida, but this provision is not found in all states that I surveyed. This language is good for business owners since it keeps the principal asset protection benefits of the company intact in the event that you fail to register foreign.  On the other hand, many states have some other negative consequences to companies that fail to register foreign. Here is a summary of some of those consequences.

  1. 1The out of state company won’t be recognized in courts to sue or bring legal action in the state where the business should be registered as a foreign company.
  2. 2Penalty of $20 per day that the company was “transacting business” in the state when it should have been registered foreign into the state but wasn’t. This penalty maxes out at $10,000 in California. Florida’s penalty is a minimum of $500 and a maximum of $1,000 per year of violation. Some states such as Arizona and Texas do not charge a penalty fee for failure to file.
  3. 3The State where you should have registered as a foreign company becomes the registered agent for your company and receives legal notices on behalf of your company. This is really problematic because it means you don’t get notice to legal actions or proceedings affecting your company and it allows Plaintiffs to sue your company and to send notice to the state without being required to send notice to your company. Now, presumably, the state will try to get notice to your company but what steps the state actually takes and how much time that takes is something I couldn’t find. With twenty to thirty day deadlines to respond in most legal actions I wouldn’t put much trust in a state government agency to get me legal notice in a timely manner nor am I even certain that they would even try.
  4. 4In addition to the statutory issues written into law there are some practical issues you will face if your out of state company is not registered into a state where you transact business. For example, some county recorders in certain states won’t allow title to transfer into your out of state company unless the LLC or corporation is registered foreign into the state where the property is located. It is also common to run into insurance and banking issues for your company until you register foreign into the state where the income generating property, employee, or storefront is located.

In summary, you should register your company as a foreign company in every state where you are “transacting business”. Generally speaking, transacting business occurs when you have a storefront in the foreign state, employees in the foreign state, or property that produces income in the foreign state. Failure to file varies among the states but can result in penalties from $1,000 to $10,000 a year and failure to receive legal notices and/or be recognized in court proceedings. Bottom line, if you are transacting business outside of your state of incorporation/organization you should register as a foreign entity in the other state(s) to ensure proper legal protections in court and to avoid costly penalties for non-compliance.

Legally Raising Money for Others

If you are receiving a fee for assisting someone else’s company in raising money, then you must operate within the confines of securities laws. These laws provide three different ways in which one may legally raise money for another company for a fee. You can’t get a “commission” or “bonus” or anything of value for bringing an investor to another company or person unless you fit into one of these three categories:

Infographic: the three legal ways to be paid for raising money for another company, the limits on finder’s fees, and the director or officer safe harbor

Broker Dealer License

First, if you are licensed and are registered with an SEC registered broker dealer, you may receive commissions and other forms of compensation for raising money in public or private offerings (e.g. private placements).  The newest form of registration from FINRA is designed to license and regulate those who operate as “investment bankers,” called a “Series 79 license.” This license allows a holder to collect commissions and other fees for raising funds for an offering of equity (e.g. stock) or debt (e.g. notes or bonds). In addition to passing the licensing test, you’ll need to associate with a broker dealer.

Finder’s Fee

Second, if you take a limited role in the raising of funds and are paid a flat or hourly fee, as opposed to commissions based on funds raised, you may be able to be paid a finder’s fee for introducing investors to others. A finder’s fee can only be paid to a finder so long as:

  1. 1The finder isn’t involved in negotiations of the securities being sold.
  2. 2The finder doesn’t discuss the details of the securities.
  3. 3The finder isn’t paid based on money raised (e.g. no commission).
  4. 4The finder doesn’t perform “finding” services on a regular basis.

In sum, a finder’s fee may be paid but only to someone who makes introductions of potential investors, and the fee amount must be based on some factor other than compensation relating the persons or amount of securities sold to those introduced by the finder.

Director or Officer of Offering Company

Third, you may be able to assist in raising funds for another if you are an Officer or Director of the company whom you are raising money for. The SEC promulgated Rule 3a4-1 which is a Safe Harbor from enforcement and allows someone who serves as a paid Director or Officer to assist in selling the company’s securities. There are many ways to qualify under this Rule but the most common is to meet the following criteria:

  1. 1Be paid as a Director or Officer by salary or other criteria that is not linked to sales of securities made (e.g. be the CFO or Treasurer and offer financial consulting advice in addition to working with potential investors).
  2. 2Can’t be associated with a Broker Dealer and cannot have a prior SEC disciplinary history.
  3. 3Should stay on with the company following closing of the offering so as to show your purpose as a Director or Officer was not just for raising funds.
  4. 4Takes a passive and restrictive role in selling the securities and refers to the CEO or President for details and negotiations.

WATCH OUT

Failure to comply with the securities laws can result in civil and criminal action. In addition, investors who can claim a failure to comply with the laws outlined above are able to rescind their investment and can subject the company’s founders and the person soliciting the investment with personal liability for any losses.

What Trump’s Lawyer, “Breaking Bad,” and “The Godfather” Teach Us About Attorney-Client Privilege

President Trump’s private lawyer, Michael Cohen, recently had his home and office raided by federal agents. But wait, isn’t all of his information attorney-client privileged? If you’re confused at how a lawyer’s records could be raided, your instincts are right. We’ve all learned about the fourth amendment, which protects us against unreasonable search and seizure, and requires the government to obtain a warrant. But, lawyer records and client information is especially protected, and any old warrant won’t allow the government to search or seize a lawyer’s records. In the case of Trump’s private lawyer, Michael Cohen, the government was able to blow past attorney-client privilege by alleging and providing credible information that they suspected Mr. Cohen was part of criminal activity himself. So, what can upstanding business owners learn from the Michael Cohen saga? Well, quite a bit.

When planning your business and tax structure with your lawyer, it is important to understand what is privileged and what is not. Often times, clients divulge information to their lawyer and wonder whether that information is “attorney-client privileged” or not.  Attorney-client privilege is an important legal protection offered to persons, companies, and organizations who provide confidential information and who seek counsel from their lawyer or law firm. Under law, an attorney cannot be required to provide attorney-client privileged information to a plaintiff in a law suit (e.g. creditor) or to a government agency (e.g. the IRS) except under limited situations. Here are a couple of common situations where you may lose attorney-client privilege and some tips to make sure your confidential information provided to your lawyers doesn’t run into the exceptions.

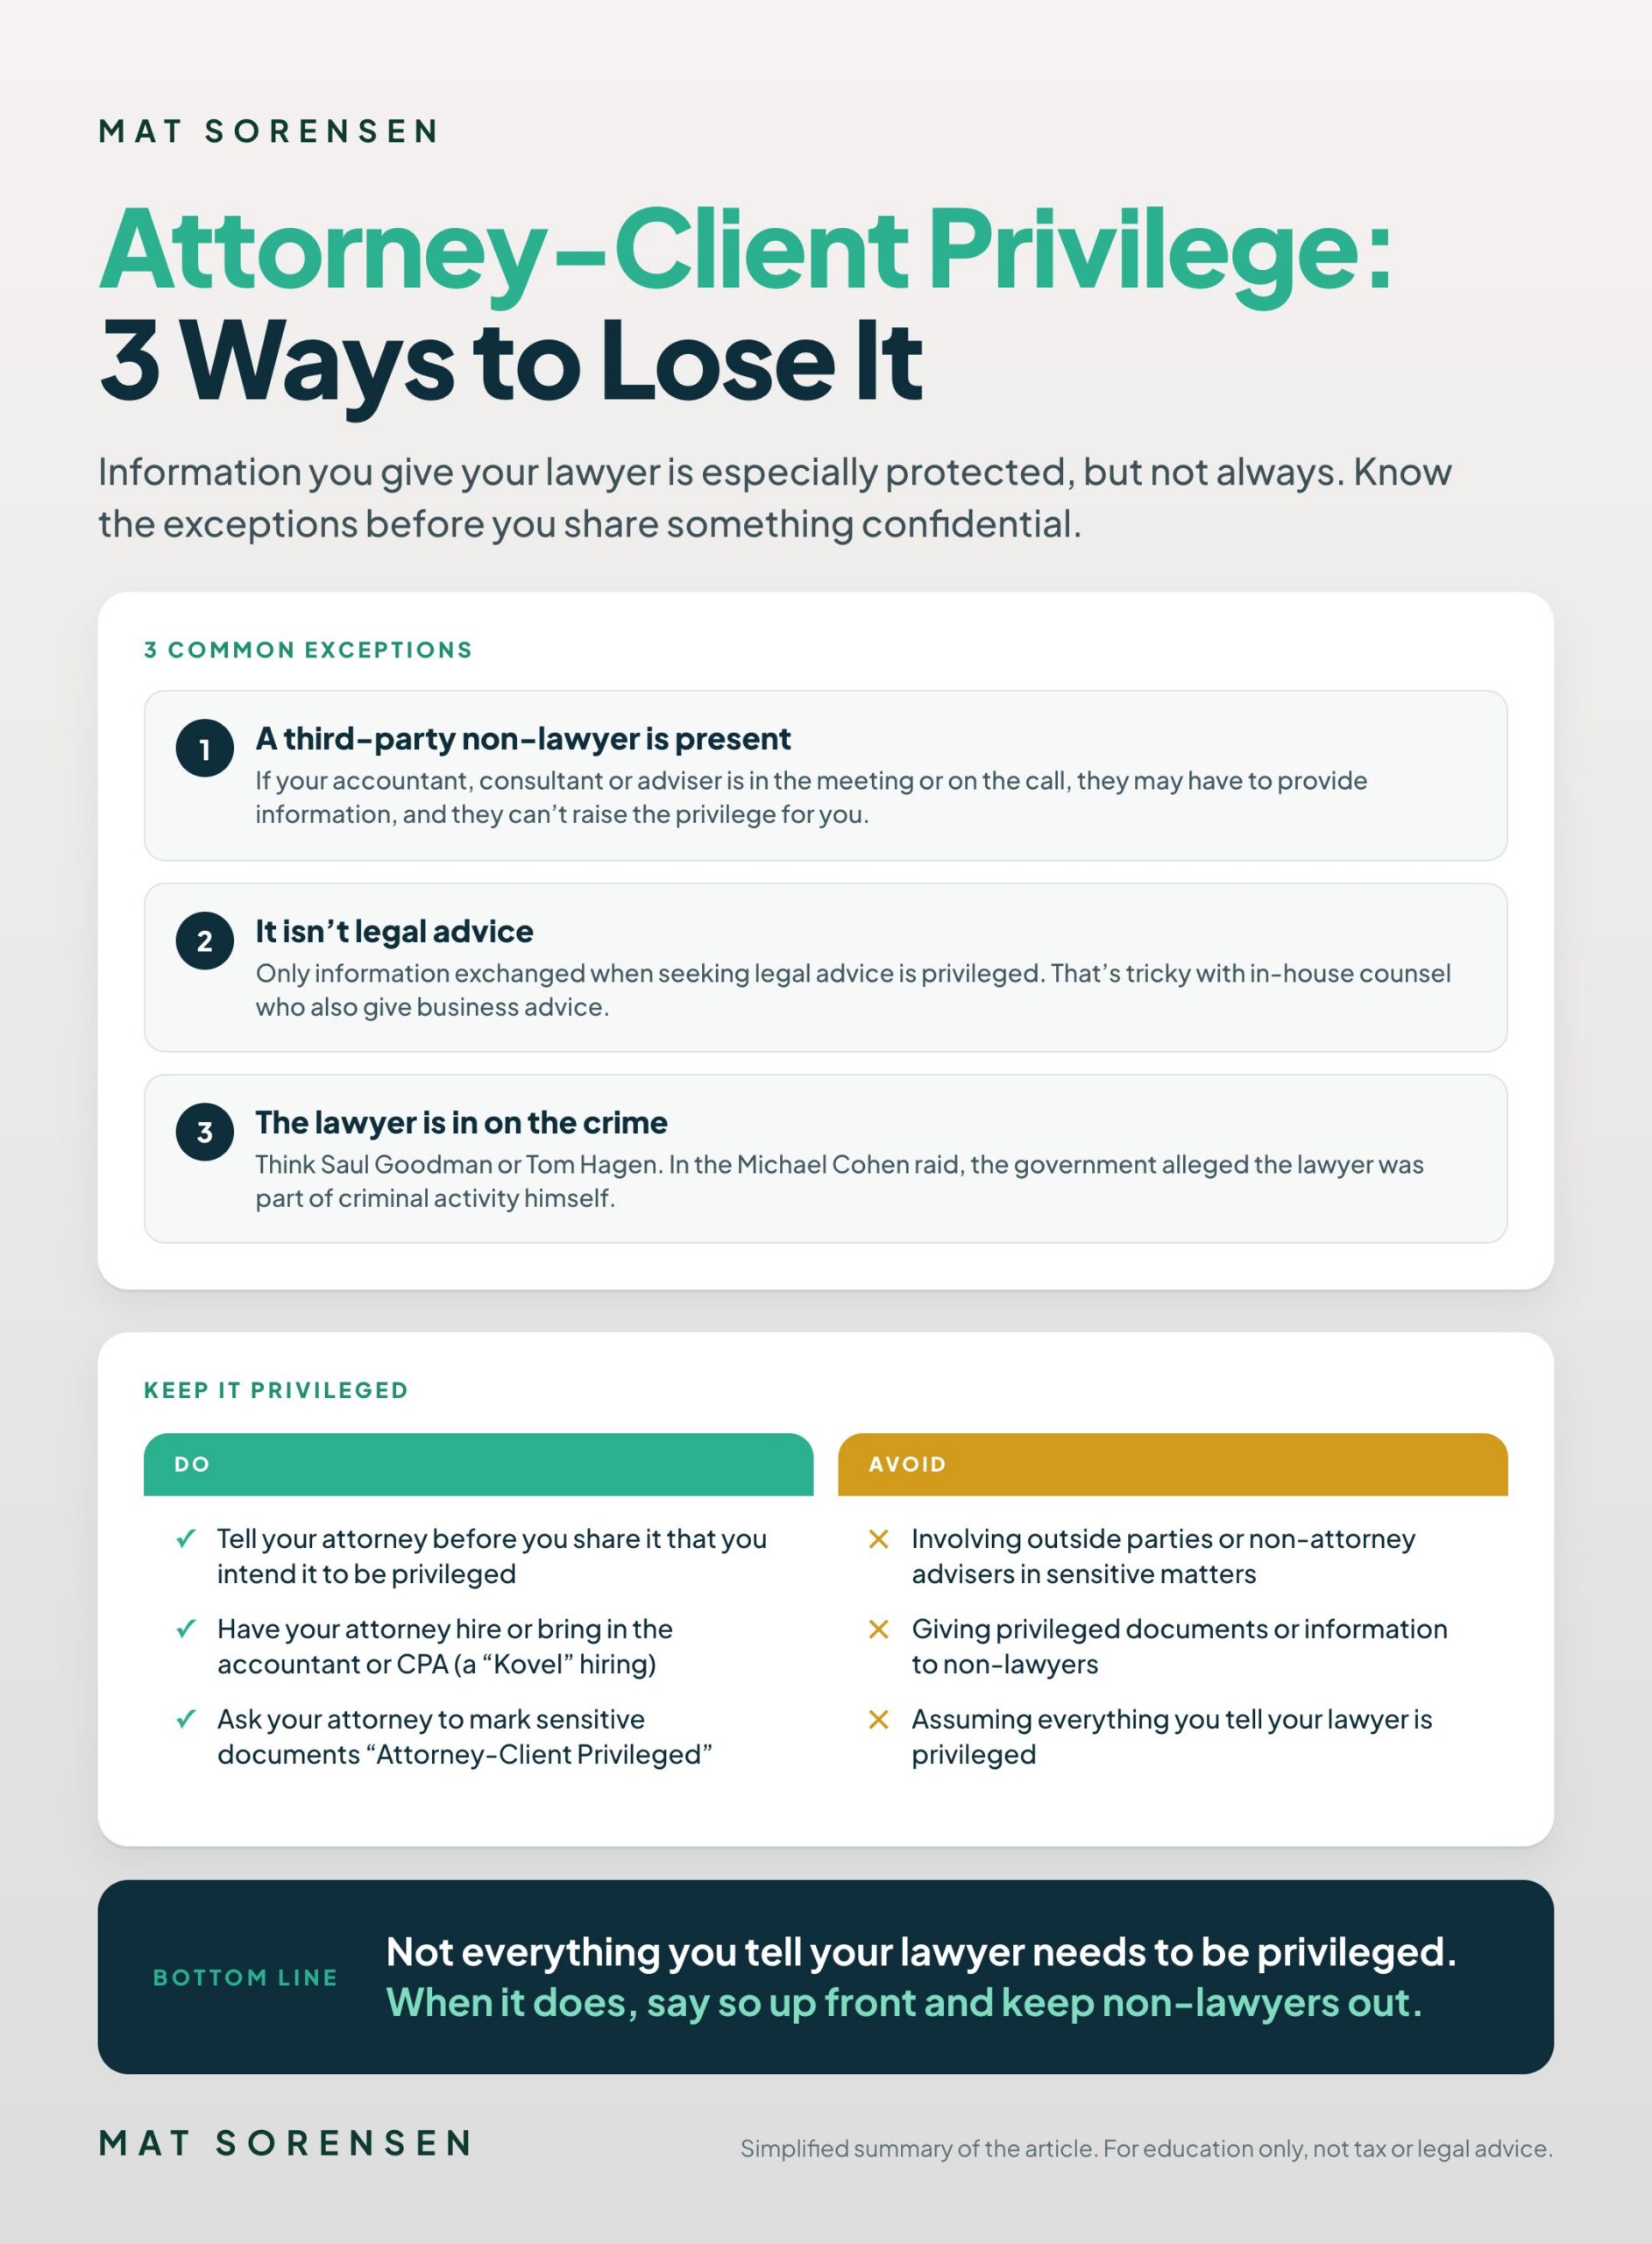
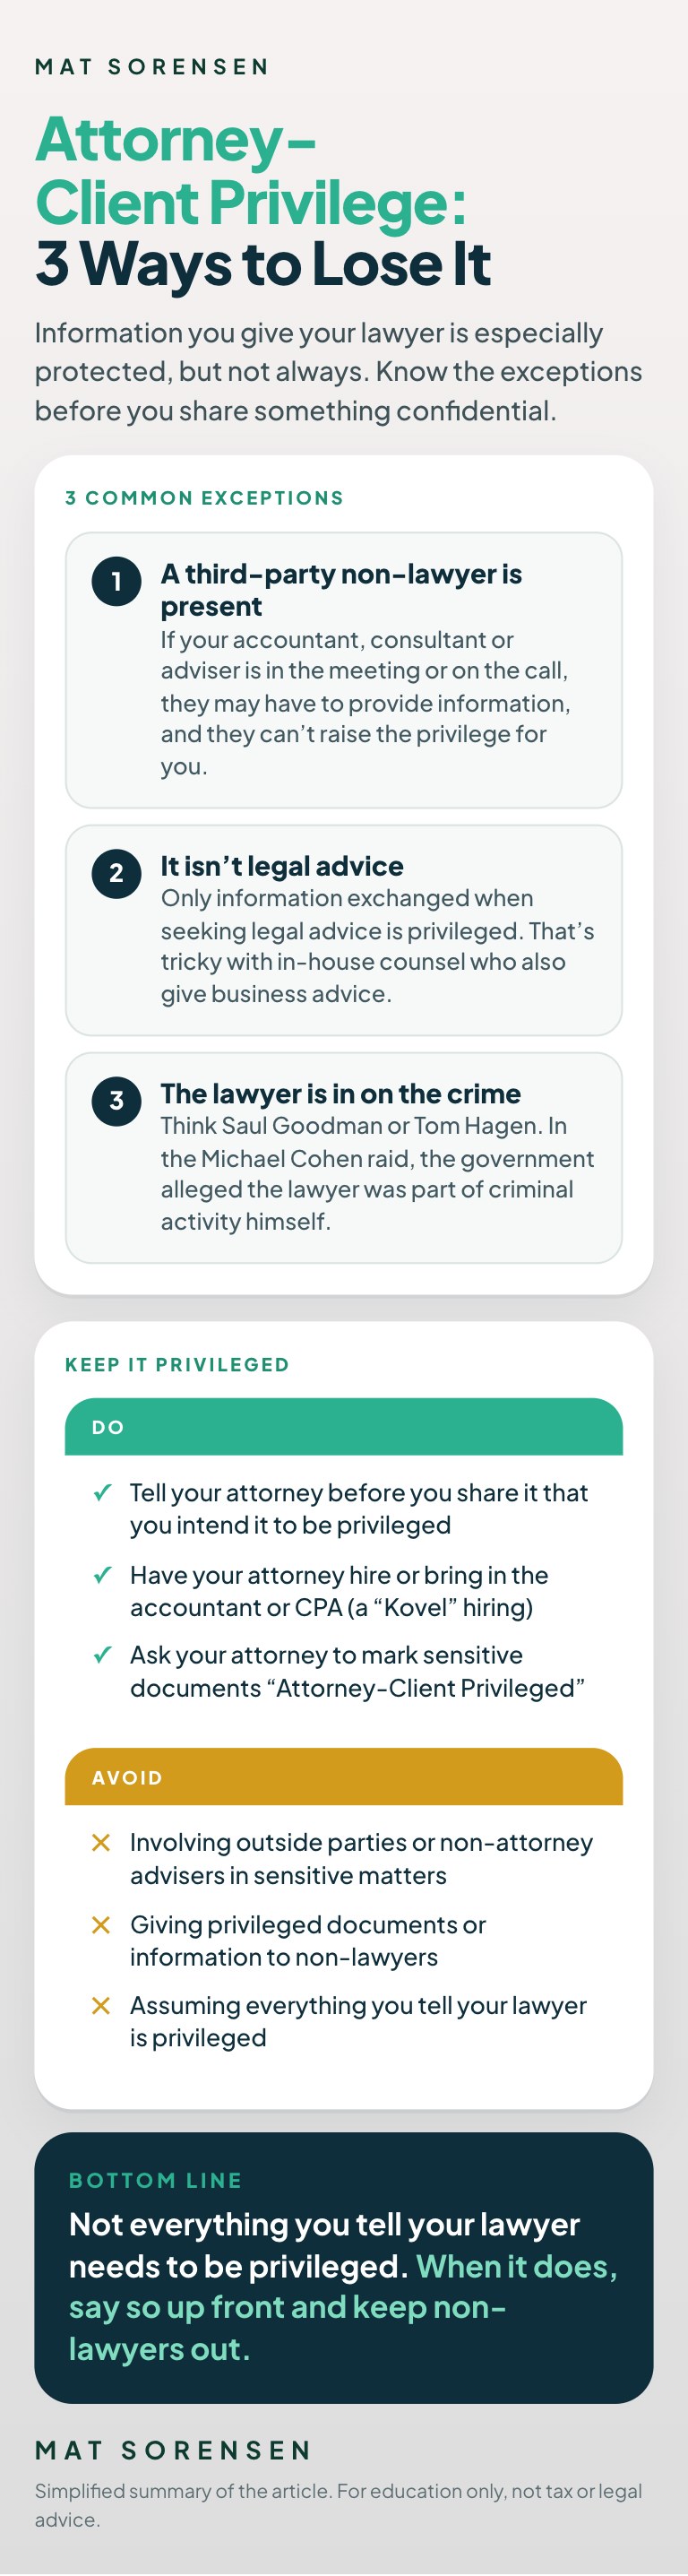
Infographic: three common exceptions to attorney-client privilege and tips to keep your information privileged

Exceptions to the Attorney-Client Privilege Rule

1. Third-party non-lawyer present

Was a third-party present with your lawyer when the information you want to be privileged was discussed. For example, was your accountant or financial adviser present when discussing information you want to remain confidential and privileged? Keep in mind that if a third-party is present in a meeting or on a conference call then that third-party may be required to provide information or documents from the meeting and that your accountant, consultant or adviser can’t raise the attorney-client privileged defense for you unless they’re actually your attorney. If a third-party professional does need to be hired (e.g. an accountant or CPA), that third-party can be hired or brought into the matter by the attorney and the privilege may remain intact. This is known as a “Kovel” hiring of the accountant, and stems from a case where a lawyer engaged an accountant for the client, and the accountant’s work was therefore covered under the lawyer’s attorney-client privilege.

Tip: For sensitive matters where you want information to remain confidential and privileged, do not involve outside parties as those outside parties or non-attorney advisers cannot raise the attorney-client privileged defense.

2. Only legal advice is attorney-client privileged

Only information exchanged when seeking legal advice is attorney-client privileged. This is especially tricky for companies who have their own “in-house” legal counsel who also offers business advice. Only the information exchanged that pertains to legal advice would be privileged. For example, was an organization chart of the company’s holdings “privileged” when provided to the company lawyer who also manages those assets for the business? Also, what if that lawyer disseminated that organization chart to accountants, property managers, or other non-lawyers? If they did, then that information is no longer attorney-client privileged.

Tip: If you have sensitive documents or information you want to keep in communication only with your lawyer, ask your attorney to identify the document as “Attorney-Client Privileged” and do not provide it to non-lawyers.

3. If the lawyer is in on the crime, it is no longer attorney-client privileged

This tip comes compliments of the Michael Cohen case outlined at the beginning of this article. You may also think of “Breaking Bad’s” famed lawyer, Saul Goodman. Or maybe you’re “The Godfather” kind of person, and you think of the mafia lawyer, Tom Hagen. In the case of Goodman and Hagen, they were lawyers who were part of the criminal enterprise of their bosses. As a result, their records are not protected by attorney-client privilege.

Tip: While this third scenario is less likely applicable to our readers, I hope, it’s more fun to talk about than when your accountant can receive incriminating information.

KEY TAKEAWAY

Remember that not all information provided to your lawyer needs to be attorney-client privileged. Keep these tips in mind when communicating highly-sensitive information to your attorney, and let your attorney know before you provide the confidential information that you intend it to be privileged, so that they can ensure that your information is properly handled and so that non-lawyer third-parties are only involved when the privilege can be maintained.

Three Instances of When You Need a New Subsidiary Entity for Your Business

Are you growing your business? Adding new products or services? New locations? Adding partners or owners? If so, these are all instances when you should consider setting up a subsidiary or other new entity for your existing company. While you can run multiple streams of business through one entity, there are tax, asset protection, and partnership reasons why you may want to open up a new subsidiary entity for your new activity.

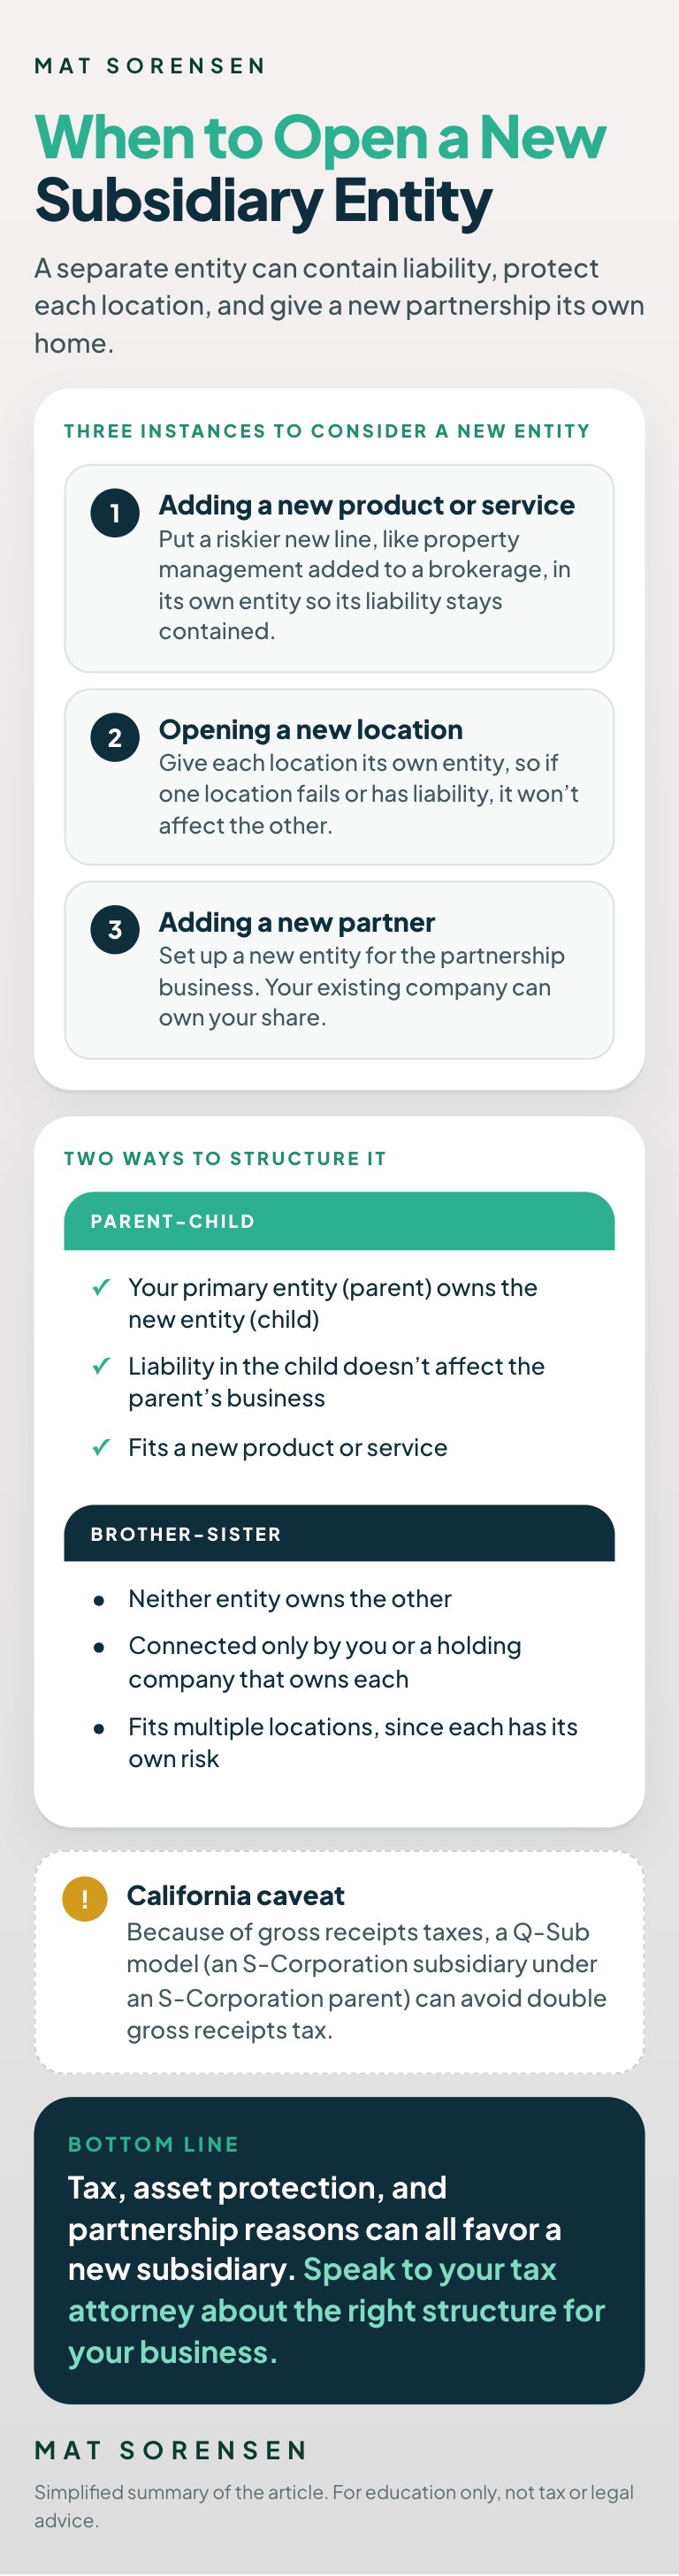
Let’s run through a few common situations when it makes sense to open up a subsidiary entity. And by subsidiary, I mean “a new entity which is owned wholly or partly by your primary business entity or by a common holding company.” Your new subsidiary could result in a parent and child relationship where your primary entity (parent) owns the new subsidiary entity (child), or it could be a brother and sister type structure where the primary business is a separate entity (brother) to the new entity (sister) and the two are only connected by you or your holding company that owns each separately and distinctly. (See the diagrams below to view the differences.)

Infographic: three instances when a business should consider a new subsidiary entity, parent-child versus brother-sister structures, and a California caveat

I. Adding a New Product or Service

You may want a new entity to separate and differentiate services or products for liability purposes.

EXAMPLE

For example, let’s say you are a real estate broker providing services of buying and selling properties and you decide to start providing property management services. Because the property management service entails more liability risk, a new entity owned wholly by your existing business could be utilized. The benefit of the new subsidiary is that if anything occurs in the new property management business, then that liability is contained in the new subsidiary and does not go down and affect your existing purchase and sale business.

On the other hand, if you ran the property management services directly from the existing company without a new subsidiary and a liability arose, then your purchase and sale business that is running through the same entity would be affected and subject to the liability.

For tax purposes, in this instance, the income from the new subsidiary entity (child) will flow down to the parent entity without a federal tax return, and as a result, there is no benefit or disadvantage from a tax planning standpoint.

Diagram displaying the Parent-Child Subsidiary structure

II. Opening a New Location

What if you’re establishing a new retail or office location for your business? Let’s say you are a restaurant opening up your second location. For asset protection purposes, you should consider setting up a second entity for the new location. This can limit your risk on the lease (don’t sign a personal guarantee) for the new location or for any liability that may occur at the new location. In this instance, if one location fails or has liability, it won’t affect the other location as they are held in separate entities. The saying goes, “don’t put all your eggs in one basket.” In this case, the basket is the same entity and the locations are your eggs. 

In the multiple location scenario, you should consider the brother-sister subsidiary structure such that each location is owned in a brother-sister relationship (e.g. neither owns the other) and their common connection is simply the underlying company (or person) who owns each entity for each location. Because both locations have risk it is useful for each to have their own entity and not to own each other (as can occur in the parent-child subsidiary). When structured in a brother-sister relationship, the liability for each location is contained in each subsidiary entity and cannot run over into the other subsidiary entity (the sibling entity) or down to the owner (which may be you personally or your operational holding company).

For tax purposes, the brother and sister subsidiary income (usually single member LLCs) flows down to the parent or primary entity where a tax return is filed (usually an S-Corp). (See the diagram below for an illustration.)

Diagram displaying the Brother-Sister Subsidiary structure

III. Adding a New Partner

Maybe you’re starting a new business or operation where you have a new partner involved. If this partner isn’t involved in your other business activities or your existing company, it is critical that a new entity be established to operate the new partnership business. If you have an existing entity where you run business operational income (e.g., an S-Corporation), then this entity may own your share of the new partnership entity (e.g., an LLC) with your new partner. Your share of the new partnership income flows through the partnership to your existing business entity where you will recognize the income and pay yourself. In this instance, your existing entity is the parent and the new partnership is a partial-child subsidiary. The new partnership entity will typically file a partnership tax return.

IV. California Caveat

Because of gross receipts taxes in California, you may use a Q-Sub entity model where the subsidiary entity is actually another S-Corporation and is called a Q-Sub. This is available only when the parent entity is an S-Corporation and can avoid double gross receipts tax at the subsidiary and parent entity level.

Make sure you speak to your tax attorney for specific planning considerations as there are asset protection and tax considerations unique to each business and subsidiary structure.