Using the Law to Protect Your Reputation Online

Have you given a negative review of a company? Have you ever posted something unflattering about someone you didn’t like?  Do you own a business with a Facebook, Yelp, Google+, or Linkedin page? Well, there’s no shortage of lawsuits about posts people make about businesses. And I get it. If you order a Pepsi and you get a Coke, well that’s one star down on Yelp. If you wait on hold for more than 10 minutes, that calls for a Facebook post about your “crappy” mortgage loan company. While these are trivial things we may have been critical about when posting reviews or comments on-line, there have been hundreds of cases over on-line reviews or comments about businesses that have resulted in legal action.
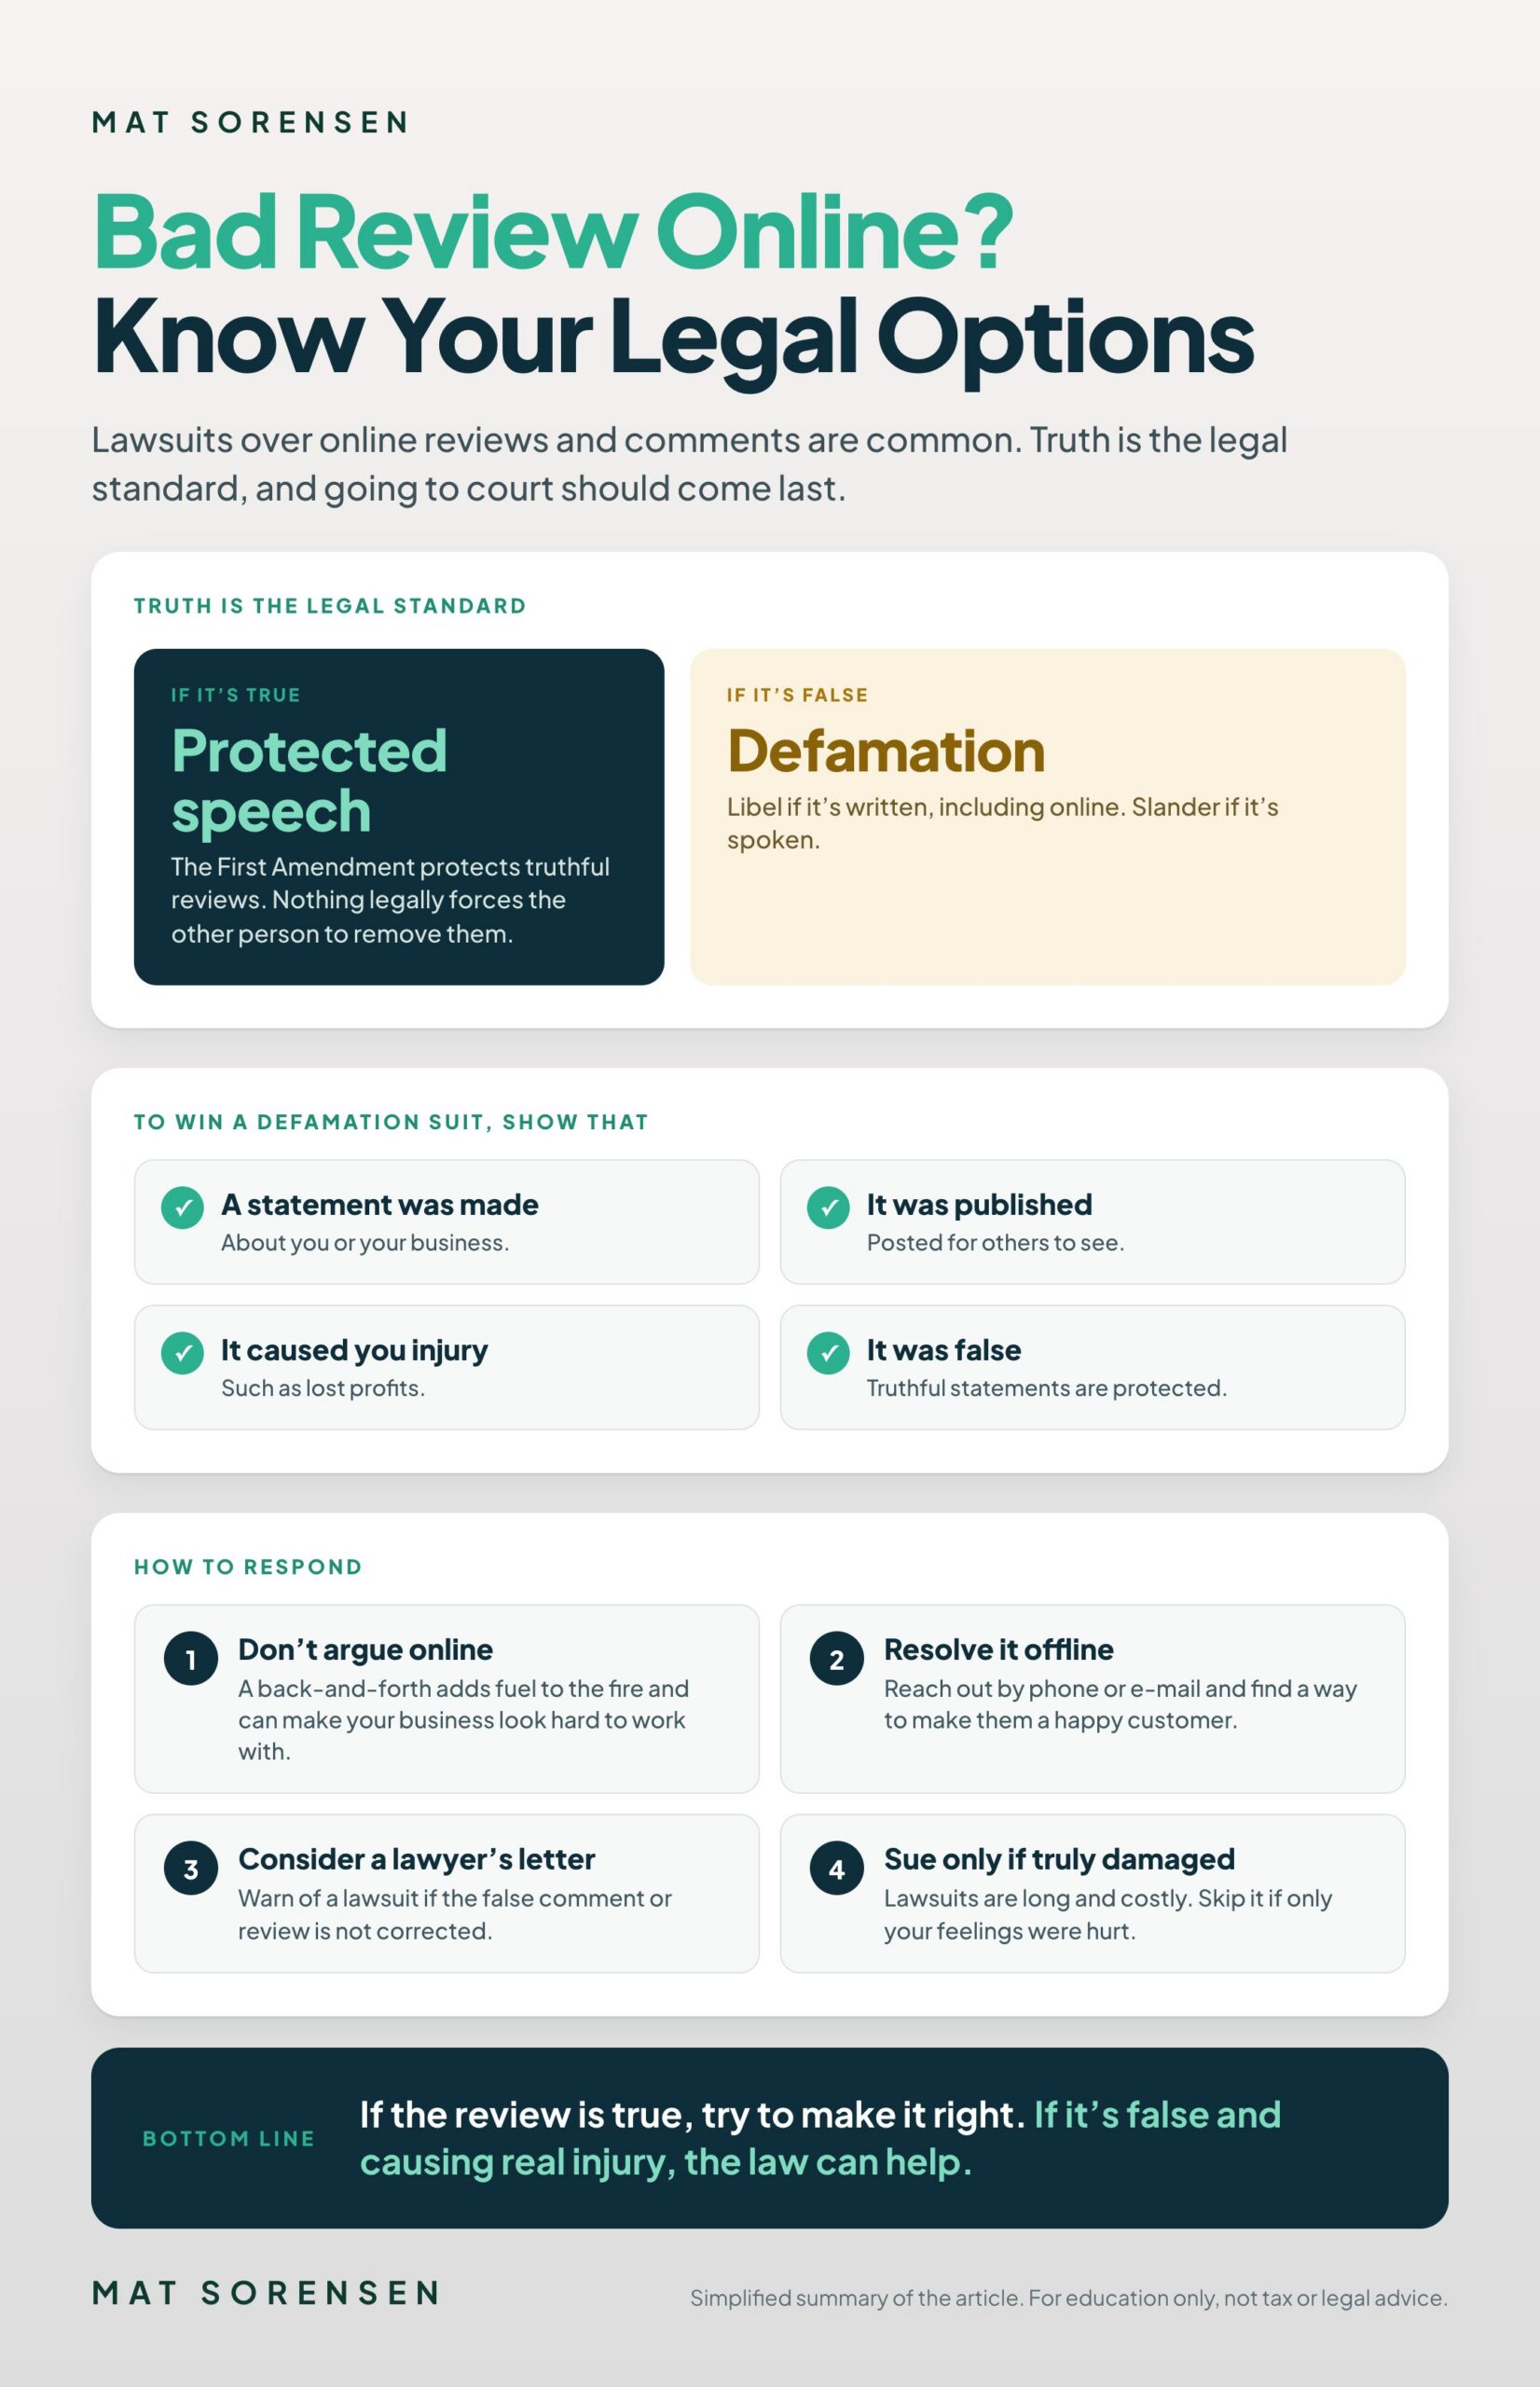
Infographic: truth is the legal standard for online reviews, what you must show to win a defamation suit, and how to respond to a negative review

Real Cases Over Online Reviews

Consider the case of Jane Perez who wrote scathing reviews of her contractor on Yelp where she accused him of botching her home renovation and stealing jewelry during construction. Well, the allegations of Ms. Perez weren’t truthful and her contractor sued her for defamation and alleged $750,000 in damages from lost business as a result of the un-truthful review. Ms. Perez counter-sued alleging that her contractor’s responses weren’t true either and she too was defamed. The case went to a jury who eventually found that both parties were untruthful in their on-line comments and postings and as a result didn’t award damages to either. However, as reported by Mandi Woodruff on Yahoo Finance, not every case ends like this. In a recent case, a disgruntled patient of 2 Arizona surgeons created an entire website alleging that they botched her plastic surgery. Well, the Arizona surgeons found her website un-truthful and took her to court and won damages of $12 million dollars. And lastly, Southwest Airlines sued a passenger for defamation, slander, and libel when the passenger posted numerous complaints about the airline and its agent on her personal Facebook and Twitter accounts. The complaints alleged that the airline refused to allow the passenger to sit next to her children.

Legal Lessons From These Cases

There are a few important legal lessons to be learned from these companies.

1. Truth is the Legal Standard

Every case that seeks to silence negative reviews or social media comments must allege that the comments posted are not truthful. The first amendment protects all of us when giving negative reviews or comments but only when those reviews are truthful. Consequently, any case brought to remove or silence a negative comment or review must allege that the comment is not truthful. If the comment or review was the truth, then there is nothing legally that you can do to force the other person to remove or correct the comment. You should certainly attempt to make it right though by contacting the customer to see what can be done to fix whatever the situation is that caused the negative statements.

2. Defamation and Libel

If the information posted about you or your business on-line is untruthful, then the legal action you may bring is called defamation. There are two types of defamation. The first type is libel and this has to do with defamation that is written. This would include on-line writings. The second type is slander and this has to do with defamation that is spoken. In order to win a defamation suit you must show the following; a) that a statement was made, b) that it was published for others to see, c) that the statement caused you injury,  and d) that the statement was false.

Awards in a defamation suit generally consist of removal of the false statement(s) and damages for the amount of lost profits or injury that was caused. Keep in mind that while lawsuits can be powerful and can remedy harm caused to you or your business, they are also costly and they don’t resolve your case in an expedient manner.

Try to Resolve It Offline First

Before heading off to court though, heed the advice of digital marketing expert Chris Bennett. Chris is the CEO of 97th Floor and was a guest on our recent radio show. Chris suggested that if your business is subjected to negative comments or reviews on-line, that it is best to attempt to remedy those issues off-line. Don’t write a spirited rebuttal on-line. If you are dealing with a disgruntled person, you are not going to win them over by telling them they are wrong. And, you typically add more fuel to the fire when a comment thread or review thread grows from back-and-forth comments between a business and a customer. This is sage advice and reminds me of a review I read on VRBO.com about a vacation rental I was looking to rent. I was distracted by a 1 star review that was given on a property I was interested in. I read the back and forth between the renter and the property owner and without knowing who was right or wrong (how could a third party), I was only left with a feeling that the property owner was hard to work with because they kept arguing in the comments instead of leaving them as is or saying thanks for your feedback. Instead of arguing on-line in responses to comments, Chris advises businesses to reach out to the disgruntled customer through phone or e-mail and find a way to make them a happy customer.

When a Lawsuit Makes Sense

If you’re unable to resolve the negative comment or review through personal communication and if that comment or review is false AND is causing you or your business injury, you can bring a lawsuit against the person who caused you harm and can resolve it in the Courts. You could also engage a lawyer to write a letter warning of a lawsuit if the false comment or review is not corrected. Keep in mind, a lawsuit can be a long and costly process so you only want to engage in this effort if you truly are being damaged. If only your feelings were hurt, or if the statements were mostly true, then don’t waste your time with a lawsuit as it won’t be worth the legal fees.
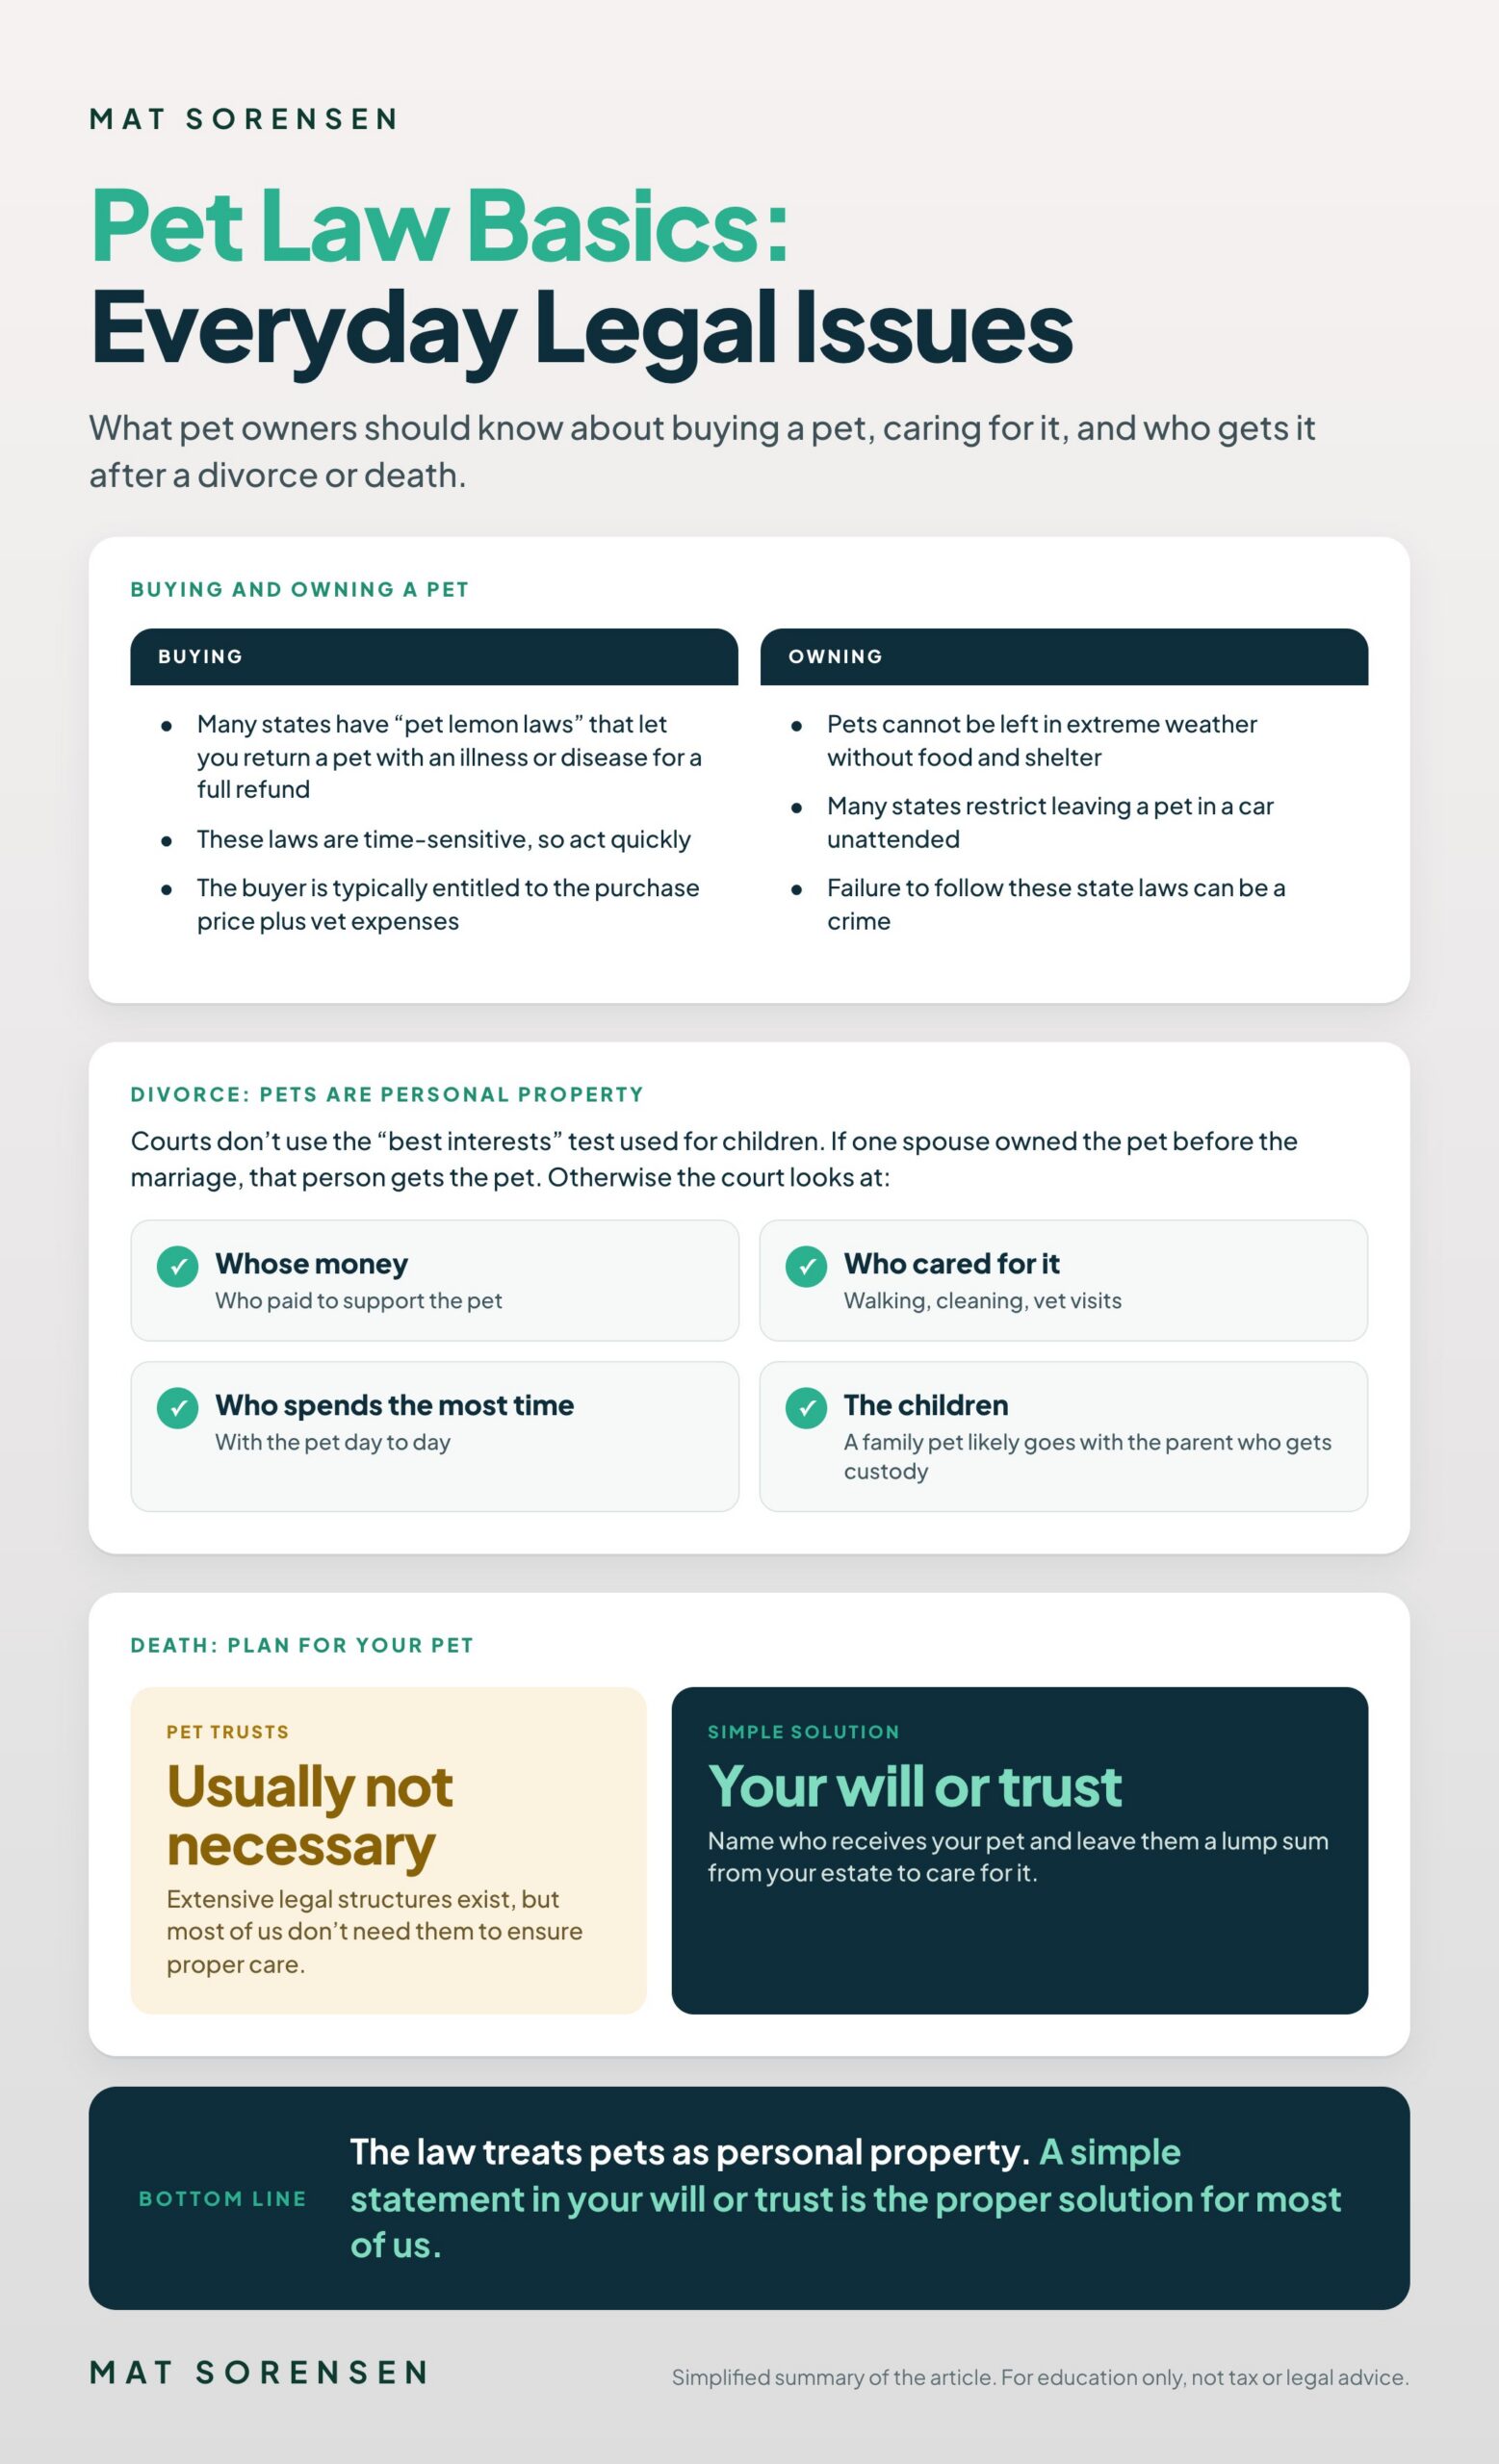
Pet Law Basics

While I’m no “pet lawyer,” I do own a 9-year-old Chihuahua and, along with other pet owners, have often looked up the laws affecting pets. For example, what happens in divorce to the family dog or cat? What if I want to return my pet to the seller? What happens to my pet upon my passing? Well, I’ve wondered this stuff too and decided to write about it. I know it’s off of my typical path, but we all encounter these everyday legal issues:

Infographic: pet law basics for buying and owning a pet, who gets the pet in a divorce, and planning for your pet after death

1. Buying a Pet

According to the American Veterinary Medical Association, 21 states have so-called “pet lemon laws” that allow a buyer of a pet to return the pet to the seller for a full refund in the event that the pet has an illness or disease. These laws are time-sensitive and the buyer of a pet with an illness or disease must act quickly.

EXAMPLE

For example, in Arizona, a buyer of a pet has 15 days to return the pet to the seller in the event that the pet has an illness or disease. The buyer has 60 days to return the pet in the event of congenital or hereditary disease (California’s time frame is one year).

Upon returning the pet, under these laws the buyer is typically entitled to their purchase price plus any veterinary expenses.

2. Owning a Pet

There are a number of laws that govern the care you should extend to your pet. Again, these laws are at the state level and vary from state to state. One common law relating to pet ownership is that pets cannot be left in extreme weather conditions without food and shelter. Another common law found in many states restricts a pet owner from leaving their pet – typically dog – in a car unattended. These laws are designed to protect the pet, and failure to abide by them can be a crime.

3. Divorce and Death

I know, the D words. One is common and the other is certain, and if you own a pet, the law may determine your pet’s new owner in these situations.

Pets and Divorce

Let’s address divorce first. By law, pets are personal property, like your furniture, guns or jewelry. Although there is typically much more meaningful attachment to our pets than to personal effects, the law treats them the same. As a result, in the event of divorce where the ownership of a pet is in dispute, the court will analyze certain factors to determine who should receive the pet. These factors are different from the factors a court will consider when determining custody of children, which generally is determined by considering the best interests of the child. In determining ownership of a pet following divorce, the court would look to who owned the pet. Was this pet owned by one person before the marriage? In this case, the person who owned the pet prior to marriage would get ownership of the pet upon divorce. What if the pet was bought by both parties during the marriage, or even before marriage. Then, the court will look at whose money supported the pet, who took care of the pet (e.g. who walked, cleaned, took to vet, etc.), and who spends the most time with the pet to determine the appropriate owner of the pet. If the pet is a family pet and if children are involved, it is likely that the “family pet” would go to the person who receives custody of the children.

Pets After Your Passing

The second situation where ownership of your pet may come into question is upon your death. We all want our pet to be loved and cared for after our passing. As a result, if you have a pet, consider listing in your will or trust a provision that states who shall receive the pet upon your passing and also consider gifting this person a lump sum of, let’s say, $5K to compensate them for caring for the pet. While you may create “pet trusts” and other extensive legal structures to outline the care of your pet, like the billionaire Leona Helmsley who left a $12 million dollar trust fund for her dog, such trusts and structures are not necessary to ensure the proper care and ownership of your pet upon your passing.

Consequently, a simple statement in your will or trust as to who you want to receive your pet and a grant of a certain lump sum of money to be given to them from your estate to care for the pet is the proper solution for most of us.

FEDERAL CIRCUIT COURT SAYS NO SALARY FROM IRA/LLC TO IRA OWNER

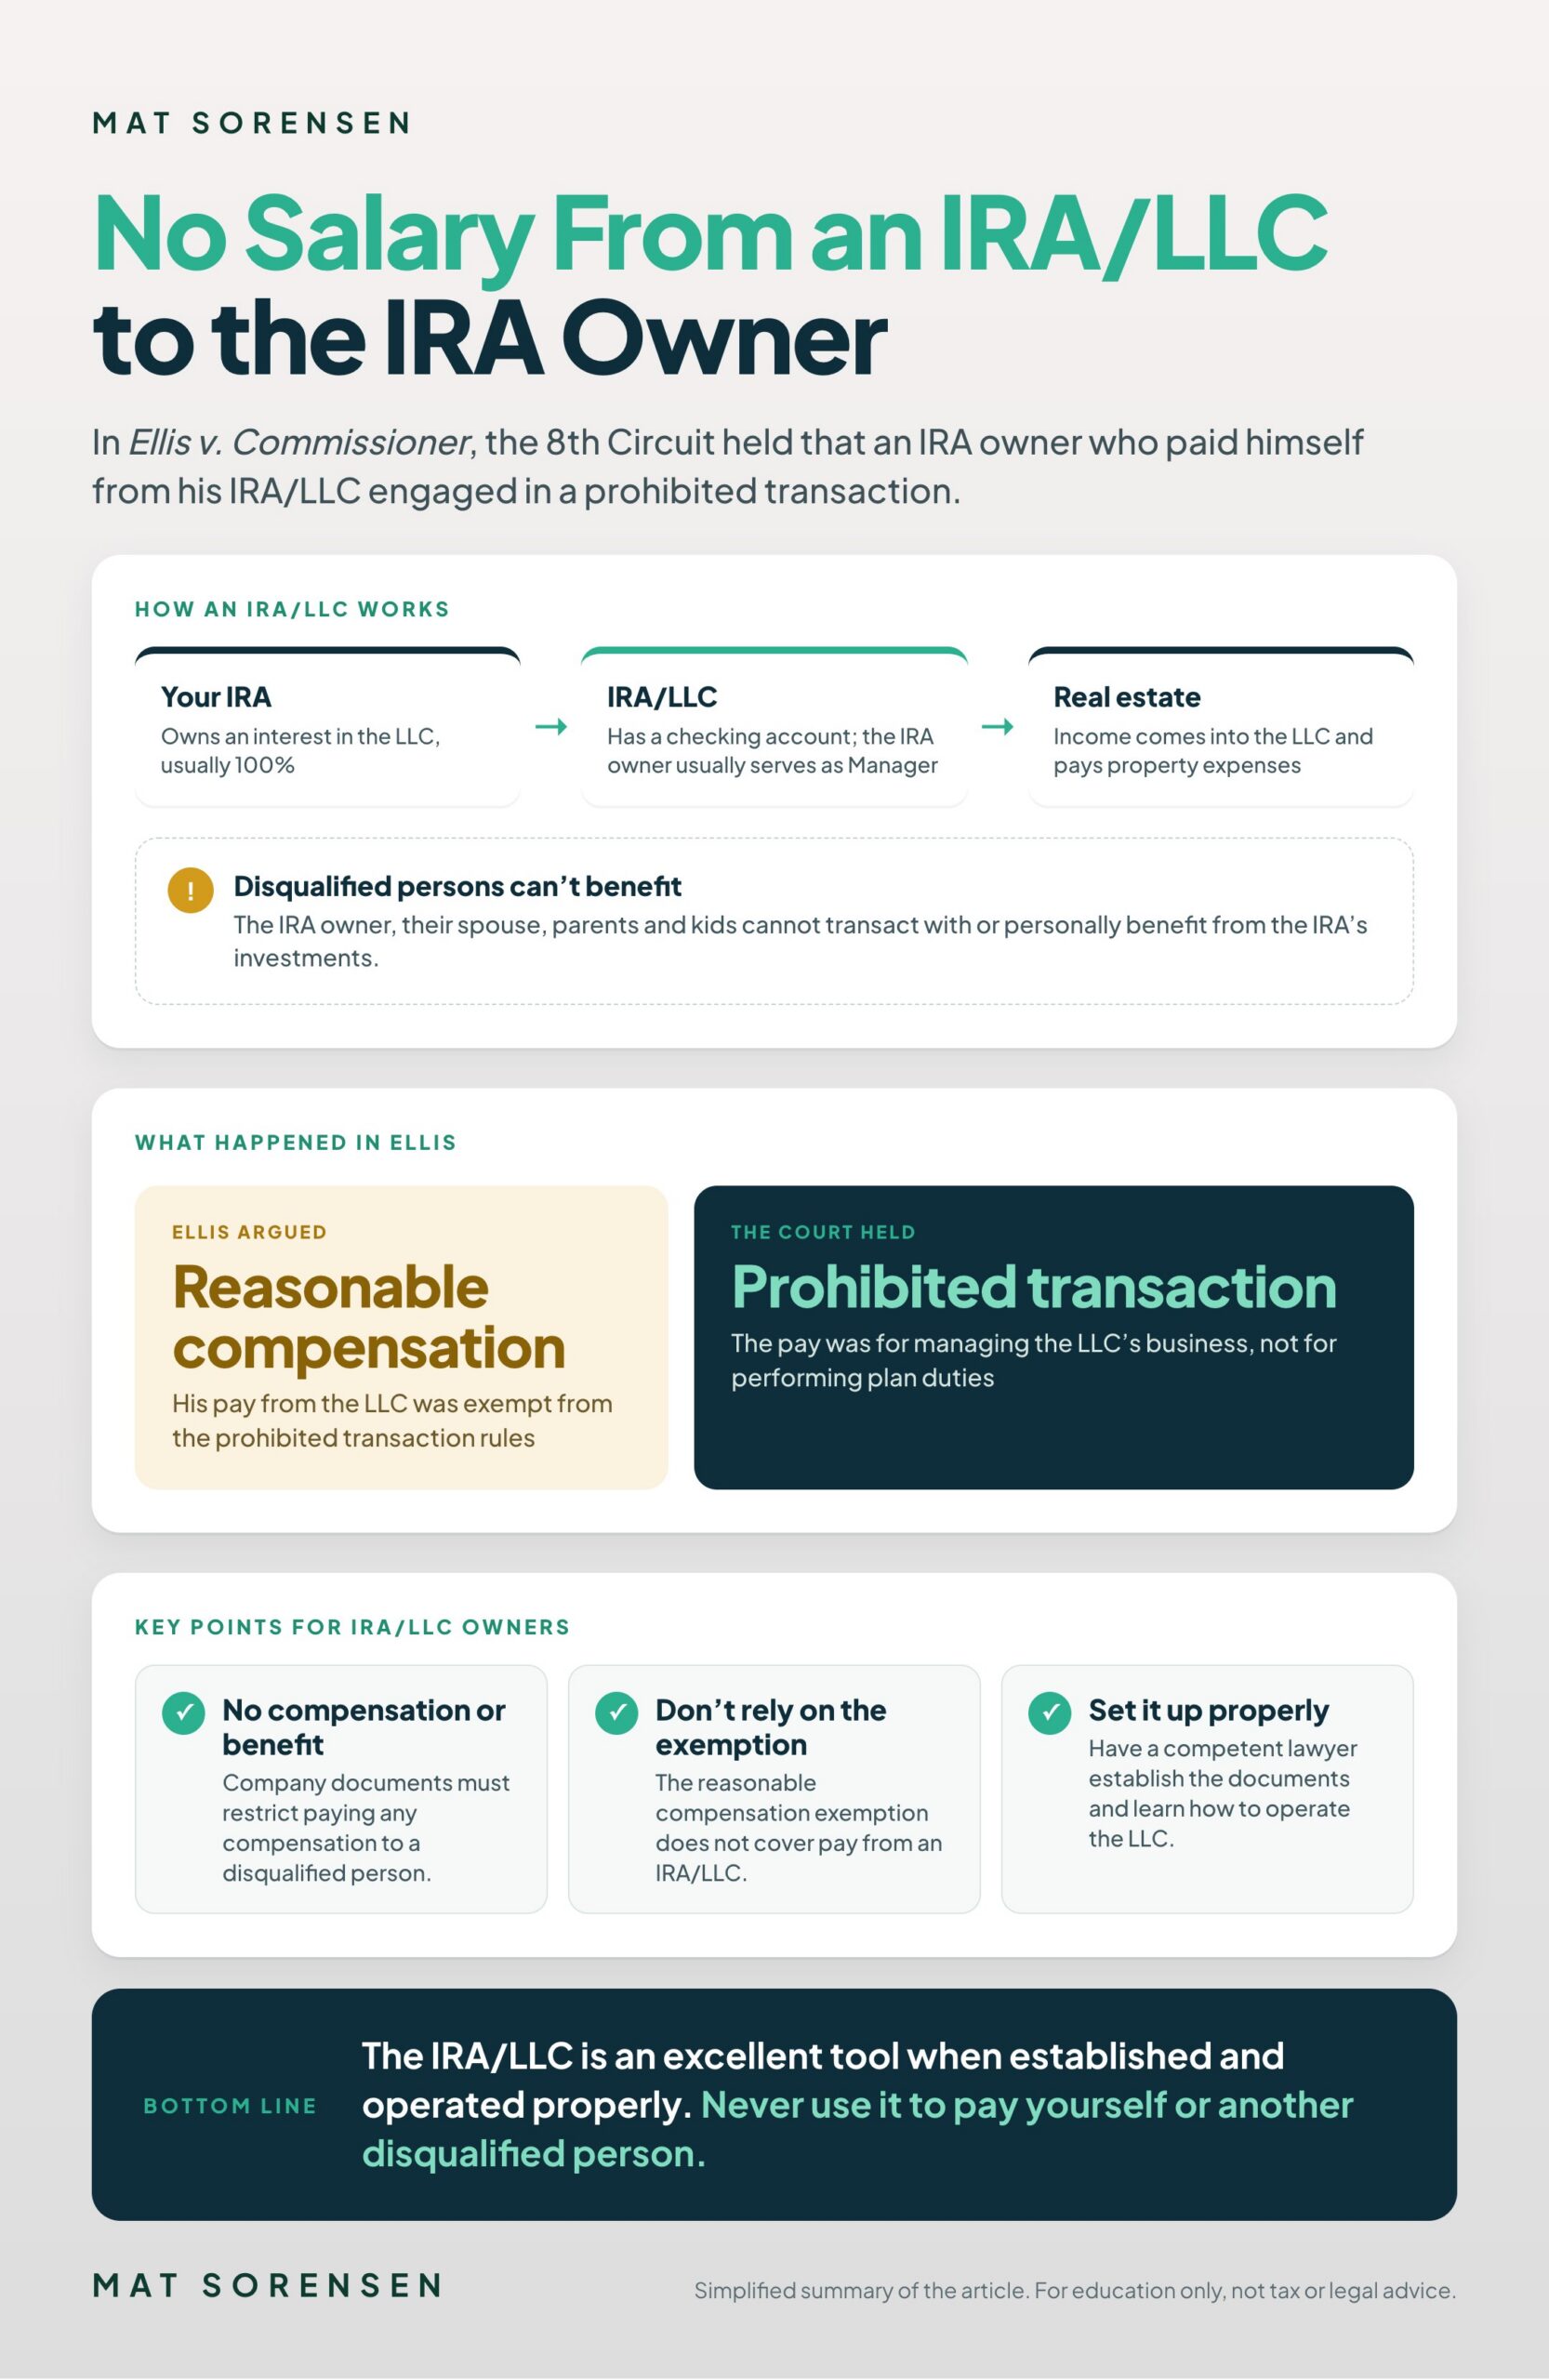
In Ellis v. Commissioner, a Federal Appeals Court recently held that an IRA owner engaged in a prohibited transaction when he paid himself compensation from his IRA/LLC. An IRA/LLC (aka, “checkbook control IRA”), is an LLC owned by an IRA and is used primarily by real estate investors who choose to have their self directed IRAs own an interest in an LLC (usually 100%) and then this IRA/LLC in turn owns the real estate asset. The LLC will typically have a bank checking account and will receive income from the property and will be used to pay property expenses.  The most common IRA/LLC structure is one where the IRA owner serves as the Manager of the IRA/LLC. Most self directed IRA companies and legal professionals will require that the IRA/LLC documents restrict the IRA owner from receiving any compensation from the IRA/LLC for serving as the Manager of the LLC. This restriction is a result of the prohibited transaction rules for IRAs which effectively state that certain persons called “disqualified persons” (e.g. IRA owner, their spouse, parents, kids) cannot transact with or personally benefit from an IRA’s investments or assets. IRC § 4975 (c)(1)(D), (E). For reference to the underlying Tax Court case and additional case facts and issues, please refer to my 2013 blog article on the Tax Court case here.

Infographic: how an IRA/LLC works, what the 8th Circuit held in Ellis v. Commissioner about paying the IRA owner compensation, and three key points for IRA/LLC owners

Key Points From the Ellis Case

As a result of the Ellis case, Self-directed IRA owners should note the following key points from the 8th Circuit Court of Appeals decisions when investing their IRA funds into LLCs or other closely held companies.

  1. 1No Compensation or Benefit. The company documents must restrict the company from paying any compensation to a disqualified person. In essence, the Tax Code restricts an IRA from transacting with so called disqualified persons and these disqualified persons include the IRA owner (as a fiduciary), their spouse, kids, and parents. For more details on who is a disqualified person, please refer to my disqualified person article and diagram here.
  2. 2Don’t Rely on the Reasonable Compensation Exemption for Payments from an IRA/LLC to a Disqualified Person. In the Ellis case, the IRA owner made an argument that the compensation paid from the LLC to the IRA owner was “reasonable compensation” exempt from the prohibited transaction rules. This argument was based on the “reasonable compensation” exemption found in IRC § 4975 (d)(10), which exempts “reasonable compensation” paid from an IRA to a disqualified person in the performance of plan duties. The Court held that the reasonable compensation exemption did not apply to Ellis as his compensation was for managing the LLC’s business activities and not in the performance of plan duties. Further, the Court noted the “in-direct” self dealing prohibited transaction restriction and also relied on DOL Opinion 2006-01A, which restricts an IRA from investing into a company if that company is supposed to then transact with or compensate a disqualified person. In the Ellis case, as would be the case in all IRA/LLC arrangements, compensation paid to an IRA owner would follow this rationale and an in-direct prohibited transaction would arise. Consequently, compensation should never be paid to a disqualified person in an IRA/LLC or other closely held IRA owned company structure.
  3. 3IRA/LLCs Are an Excellent Tool for Many Self Directed IRA Investors When Established and Operated Properly. The Ellis case is an excellent example of someone taking a good idea too far. The IRA/LLC is an excellent tool that provides many benefits to self directed IRA owners and the same structure has been used by pension and profit sharing plans for owning  real estate or other alternative assets for years. That being said, the tax rules applicable to self-directed IRAs can be tricky to understand and investors self directing these accounts for the first time can find themselves in the middle of a prohibited transaction if they don’t seek competent advice before they invest their account. Before investing tens or hundreds of thousands of dollars into an IRA/LLC or checkbook control IRA, make sure that the documents are established properly by a competent lawyer and that the IRA owner properly understands how to operate the LLC following set-up. Self-directed IRA owners should not rely on advice from their IRA custodian or administrator as they make you sign waivers saying you aren’t relying on their advice. Also, don’t rely on someone selling you an investment as they may have mixed motives in completing the transaction. Instead, seek the guidance of a competent attorney in this area and avoid structures where an IRA owner or other disqualified person would be compensated personally as part of the IRA/LLC structure.

Our office has been establishing LLCs for IRAs and other retirement accounts for over ten years. For additional information on IRA/LLCs, please refer to my book The Self Directed IRA Handbook or my website at matsorensen.com.

FREE CHECKBOOK IRA GUIDE

Learn how an IRA-owned LLC gives you checkbook control over your IRA investments.

Get the Free IRA/LLC Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

Who Should I List as Trustee of My Trust?

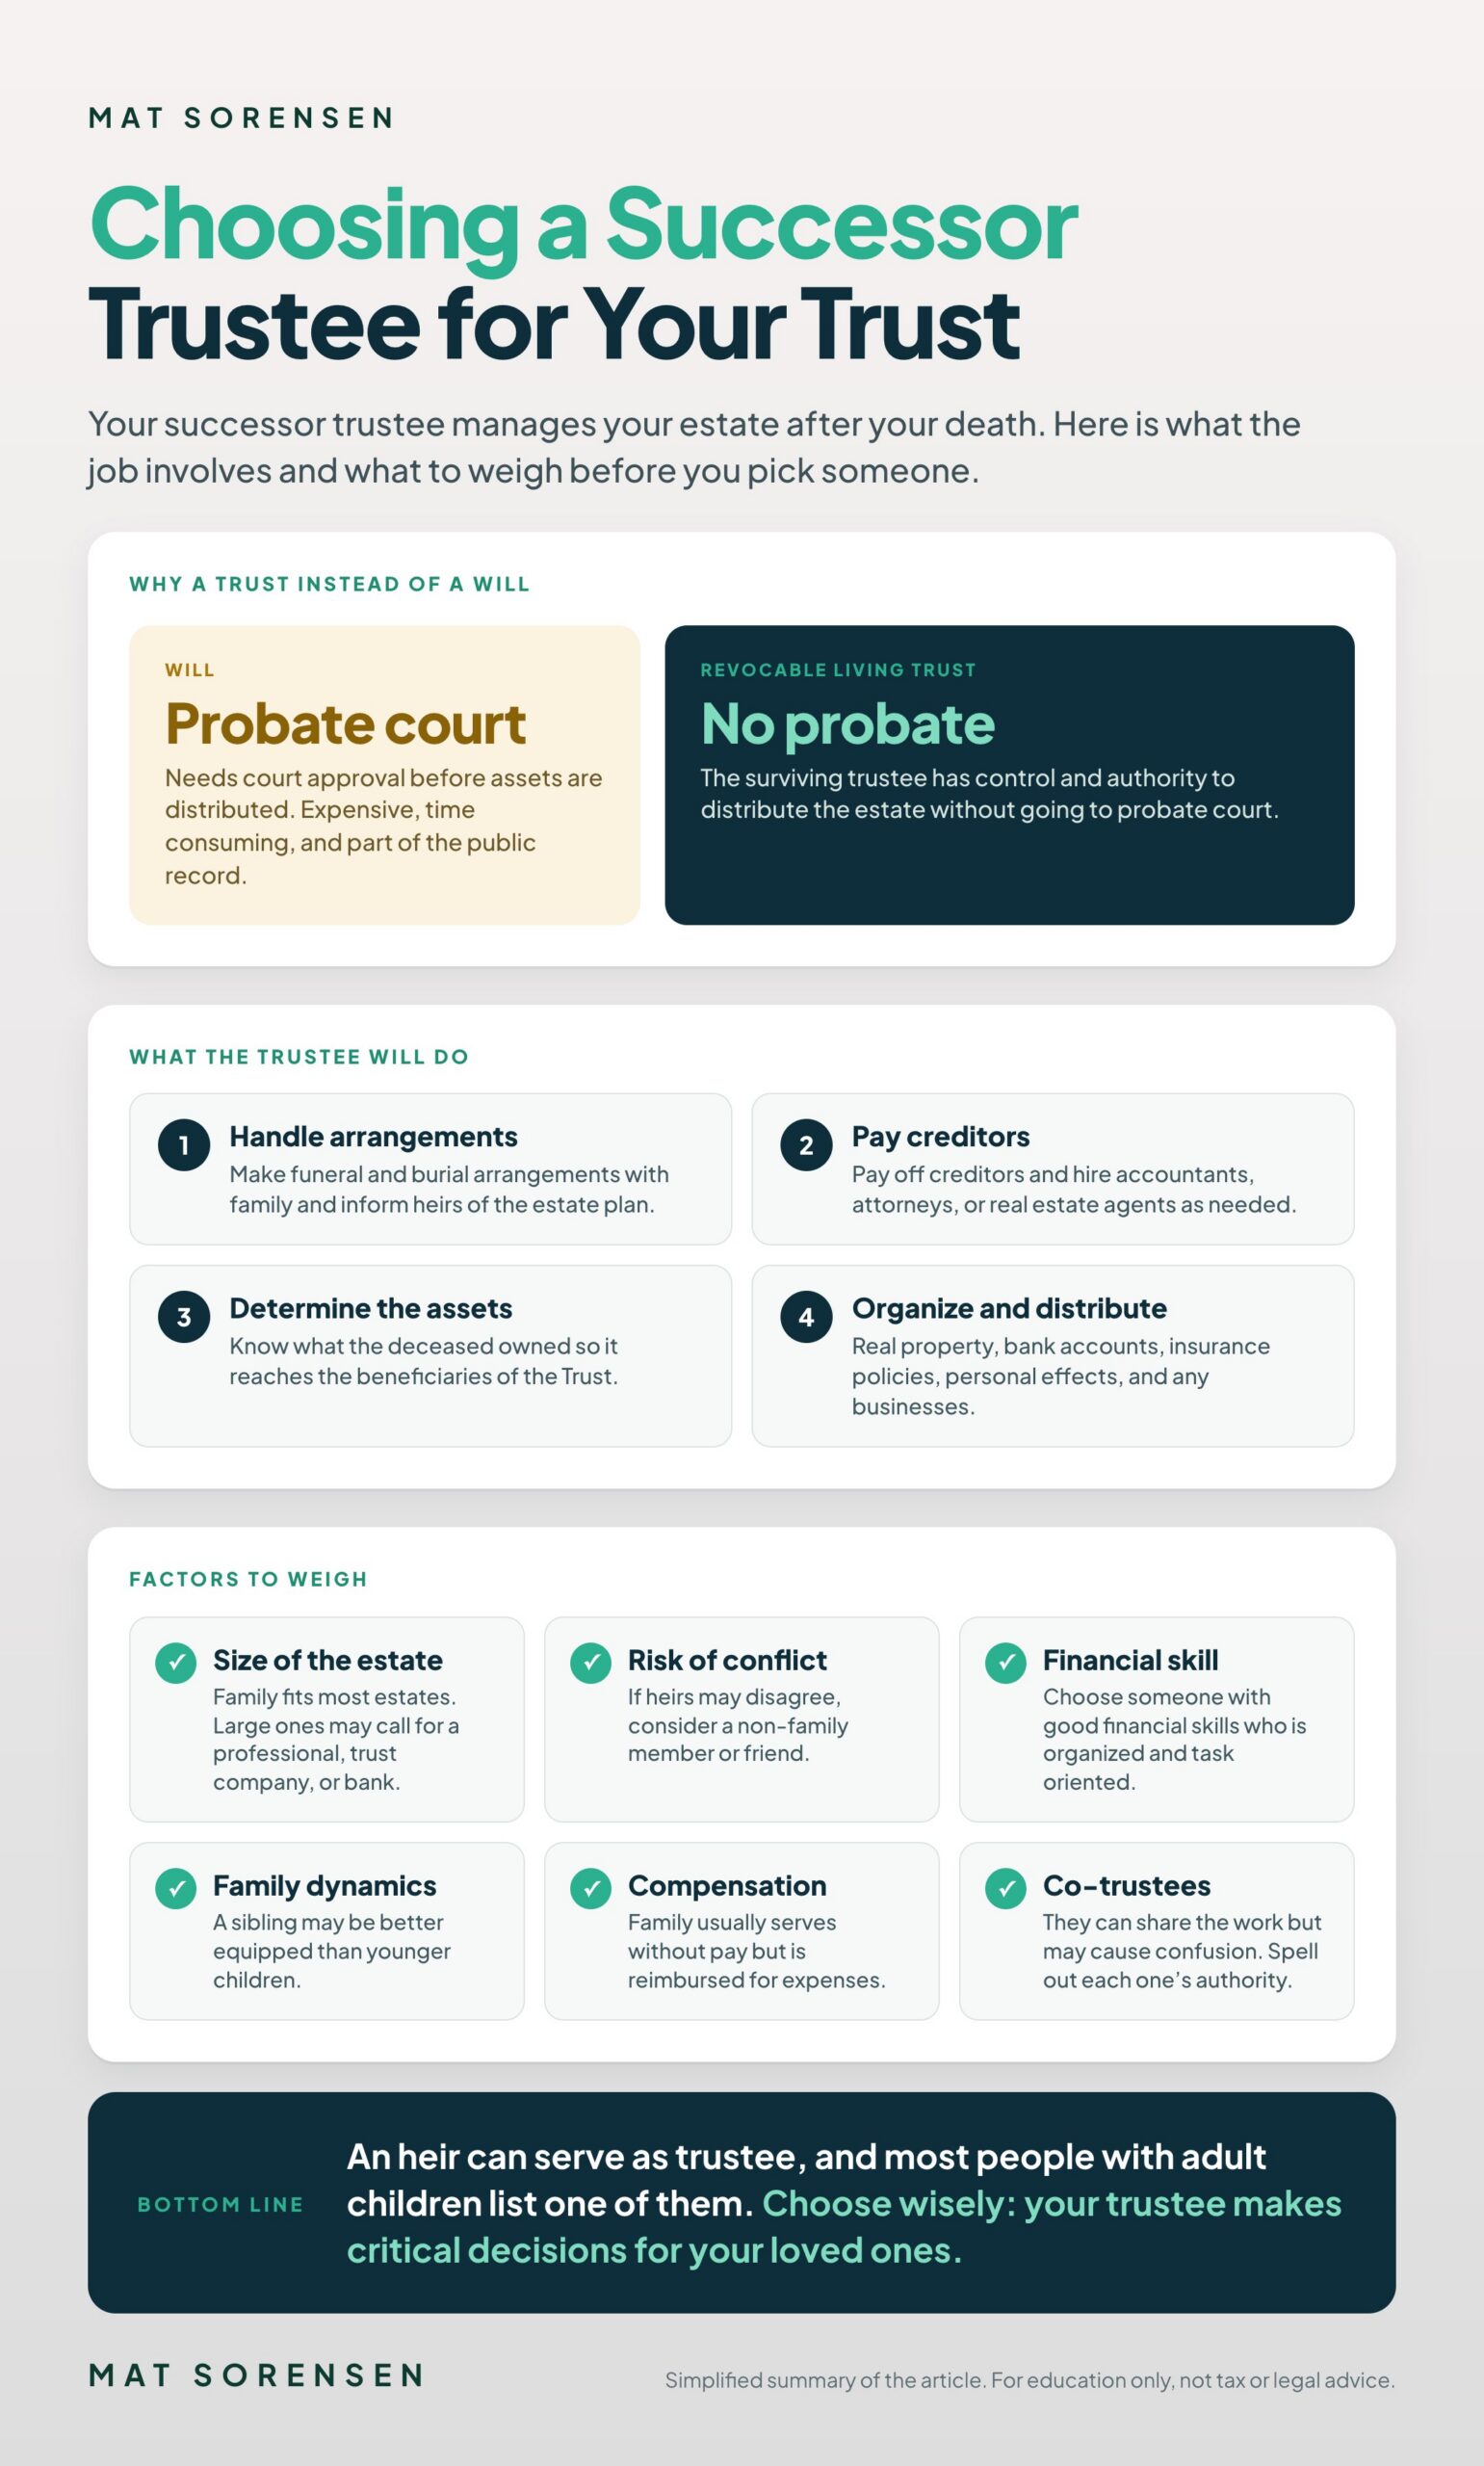
If you are establishing an estate plan, it is likely that you will have a Revocable Living Trust (“Trust”) as the primary document that outlines who will receive your assets upon your death and what conditions, if any, will be placed on those assets. As many persons are aware, a Trust has numerous advantages over a will because upon the death of the owner(s) of the Trust, the surviving trustee of the Trust will have control and authority to distribute the estate of the deceased person without having to go to probate court. A will, by contrast, typically must receive Court approval and distribution of the assets occurs only after going through probate court and getting orders from the Court. The probate process of a will is expensive, time consuming, and is part of the public record.

When establishing a revocable trust you will be outlining your assets and who will receive those assets upon your death. You will also outline certain conditions that may be placed on your assets. For example, you may state that your children will receive an equal share of your estate upon your death and the death of your spouse but your children shall not receive a distribution if they have a drug or alcohol addiction or if they have a creditor who would seize the funds. The trust may also restrict distributions to minor children so that they don’t receive a large inheritance when they are 18.

Infographic: why a trust avoids probate, what a successor trustee does, and the factors to weigh when choosing one

Trustee Selection

One of the most significant decisions you will make when you establish your Trust is who will be the Trustee of your Trust upon your death. In most situations, you will be the trustee during your lifetime and if you have a spouse your spouse will be trustee if they survive you. However, you will need to select a successor Trustee of your Trust who will manage your estate following your death (and the death of your spouse, as applicable). This successor Trustee may be a family member, friend, bank or trust company, or an attorney or other professional. When determining who should be your Trustee, you should consider the following issues and factors.

What Will the Trustee Do?

The Trustee will need to undertake the following tasks.

  1. 1Typically will make funeral and burial arrangements along with family members (generally the Trust pays for these things).
  2. 2Inform family members and heirs of the estate plans of the deceased.
  3. 3Will pay off creditors and hire professionals as needed to assist with the estate (accountants, attorneys, real estate agents, etc.).
  4. 4Determine assets. They will need to know the assets of the deceased in order to ensure that they are distributed to the heirs/beneficiaries of the Trust.
  5. 5Organize assets for distribution. This may include listing and selling real property. It will likely include coordinating the distribution of bank accounts and insurance policies. It will also include organizing and distributing personal effects (e.g. jewelry, furniture, art, personal effects). And finally, it may include the winding down, sale, or transfer of businesses.

Size of the Estate

Most Trusts will list a family member as the Trustee of the estate and for estates of a couple million dollars or less this is generally a good fit. However, for estates over $3M you may want to consider listing a professional (attorney or law firm) as the successor trustee of your estate and for estates over $10M you may want to consider listing a trust company or bank as the trustee of your estate. Large estates can overwhelm a family member who has never handled such matters before and having a professional with experience can go a long way. The Trust will need to pay for these services (generally in the tens of thousands of dollars) so it isn’t typically advisable for smaller estates unless there is no other adequate family member or friend available.

When to List Non-Family?

If you have heirs/beneficiaries who are likely to disagree and cause contention, you may want to list a non-family member or a friend as the Trustee so that a third party can make decisions and so that you can avoid potential contention and litigation over your estate.

Financial Expertise of the Trustee

If you are selecting a family member, choose one who has shown good financial skills over their life. If you’re selecting a child over another, consider their financial expertise, work background, location, and family dynamics in selecting one child as Trustee over another. Also, choose someone who is well organized and who is task oriented. The Trustee will have many things to accomplish and you want someone who will take care and responsibility for these things.

Family Dynamics

All families are different and all situations are unique. As a result, you may select a brother or sister as your successor Trustee instead of choosing a child or other family member. This may be because your children are younger or because a sibling is better equipped to handle the administration of your estate.

Trustee Compensation

If you are listing a family member as Trustee, they typically will serve without compensation but will be reimbursed for any expenses they incur while serving as Trustee. You may compensate them or give them something extra from the estate for taking on the responsibility but generally family members are listed to serve without compensation.

Can an Heir/Beneficiary be a Trustee?

Yes, you may have a beneficiary/heir serve as Trustee and this is very common. In fact, most persons who have adult children will list a child as the successor Trustee and this person will also typically be a beneficiary/heir. While there is some conflict of interest in this arrangement, the Trustee is bound to the terms of the Trust and can’t abuse that discretion for their own personal benefit.

Should I Appoint Co-Trustees?

Some persons will consider listing co-beneficiaries as successor Trustees. Typically, this is done as a way to involve more than one family member in the distribution of the estate so that one person doesn’t feel left out. While there can be some benefits to involving another person as Trustee (e.g. sharing the workload, combining skills of persons listed) it can cause contention and confusion as to who is doing what so be specific about their authority and responsibility if you are listing multiple trustees.

Who is Most Commonly Listed as Trustee?

Most persons with adult children will list one of their children as successor Trustee. Most persons with younger children will list a sibling or close friend as their successor Trustee.

Your Trustee has an important and critical task in managing your estate following your death. Choose wisely as they will need to make critical decisions that will affect your loved ones.

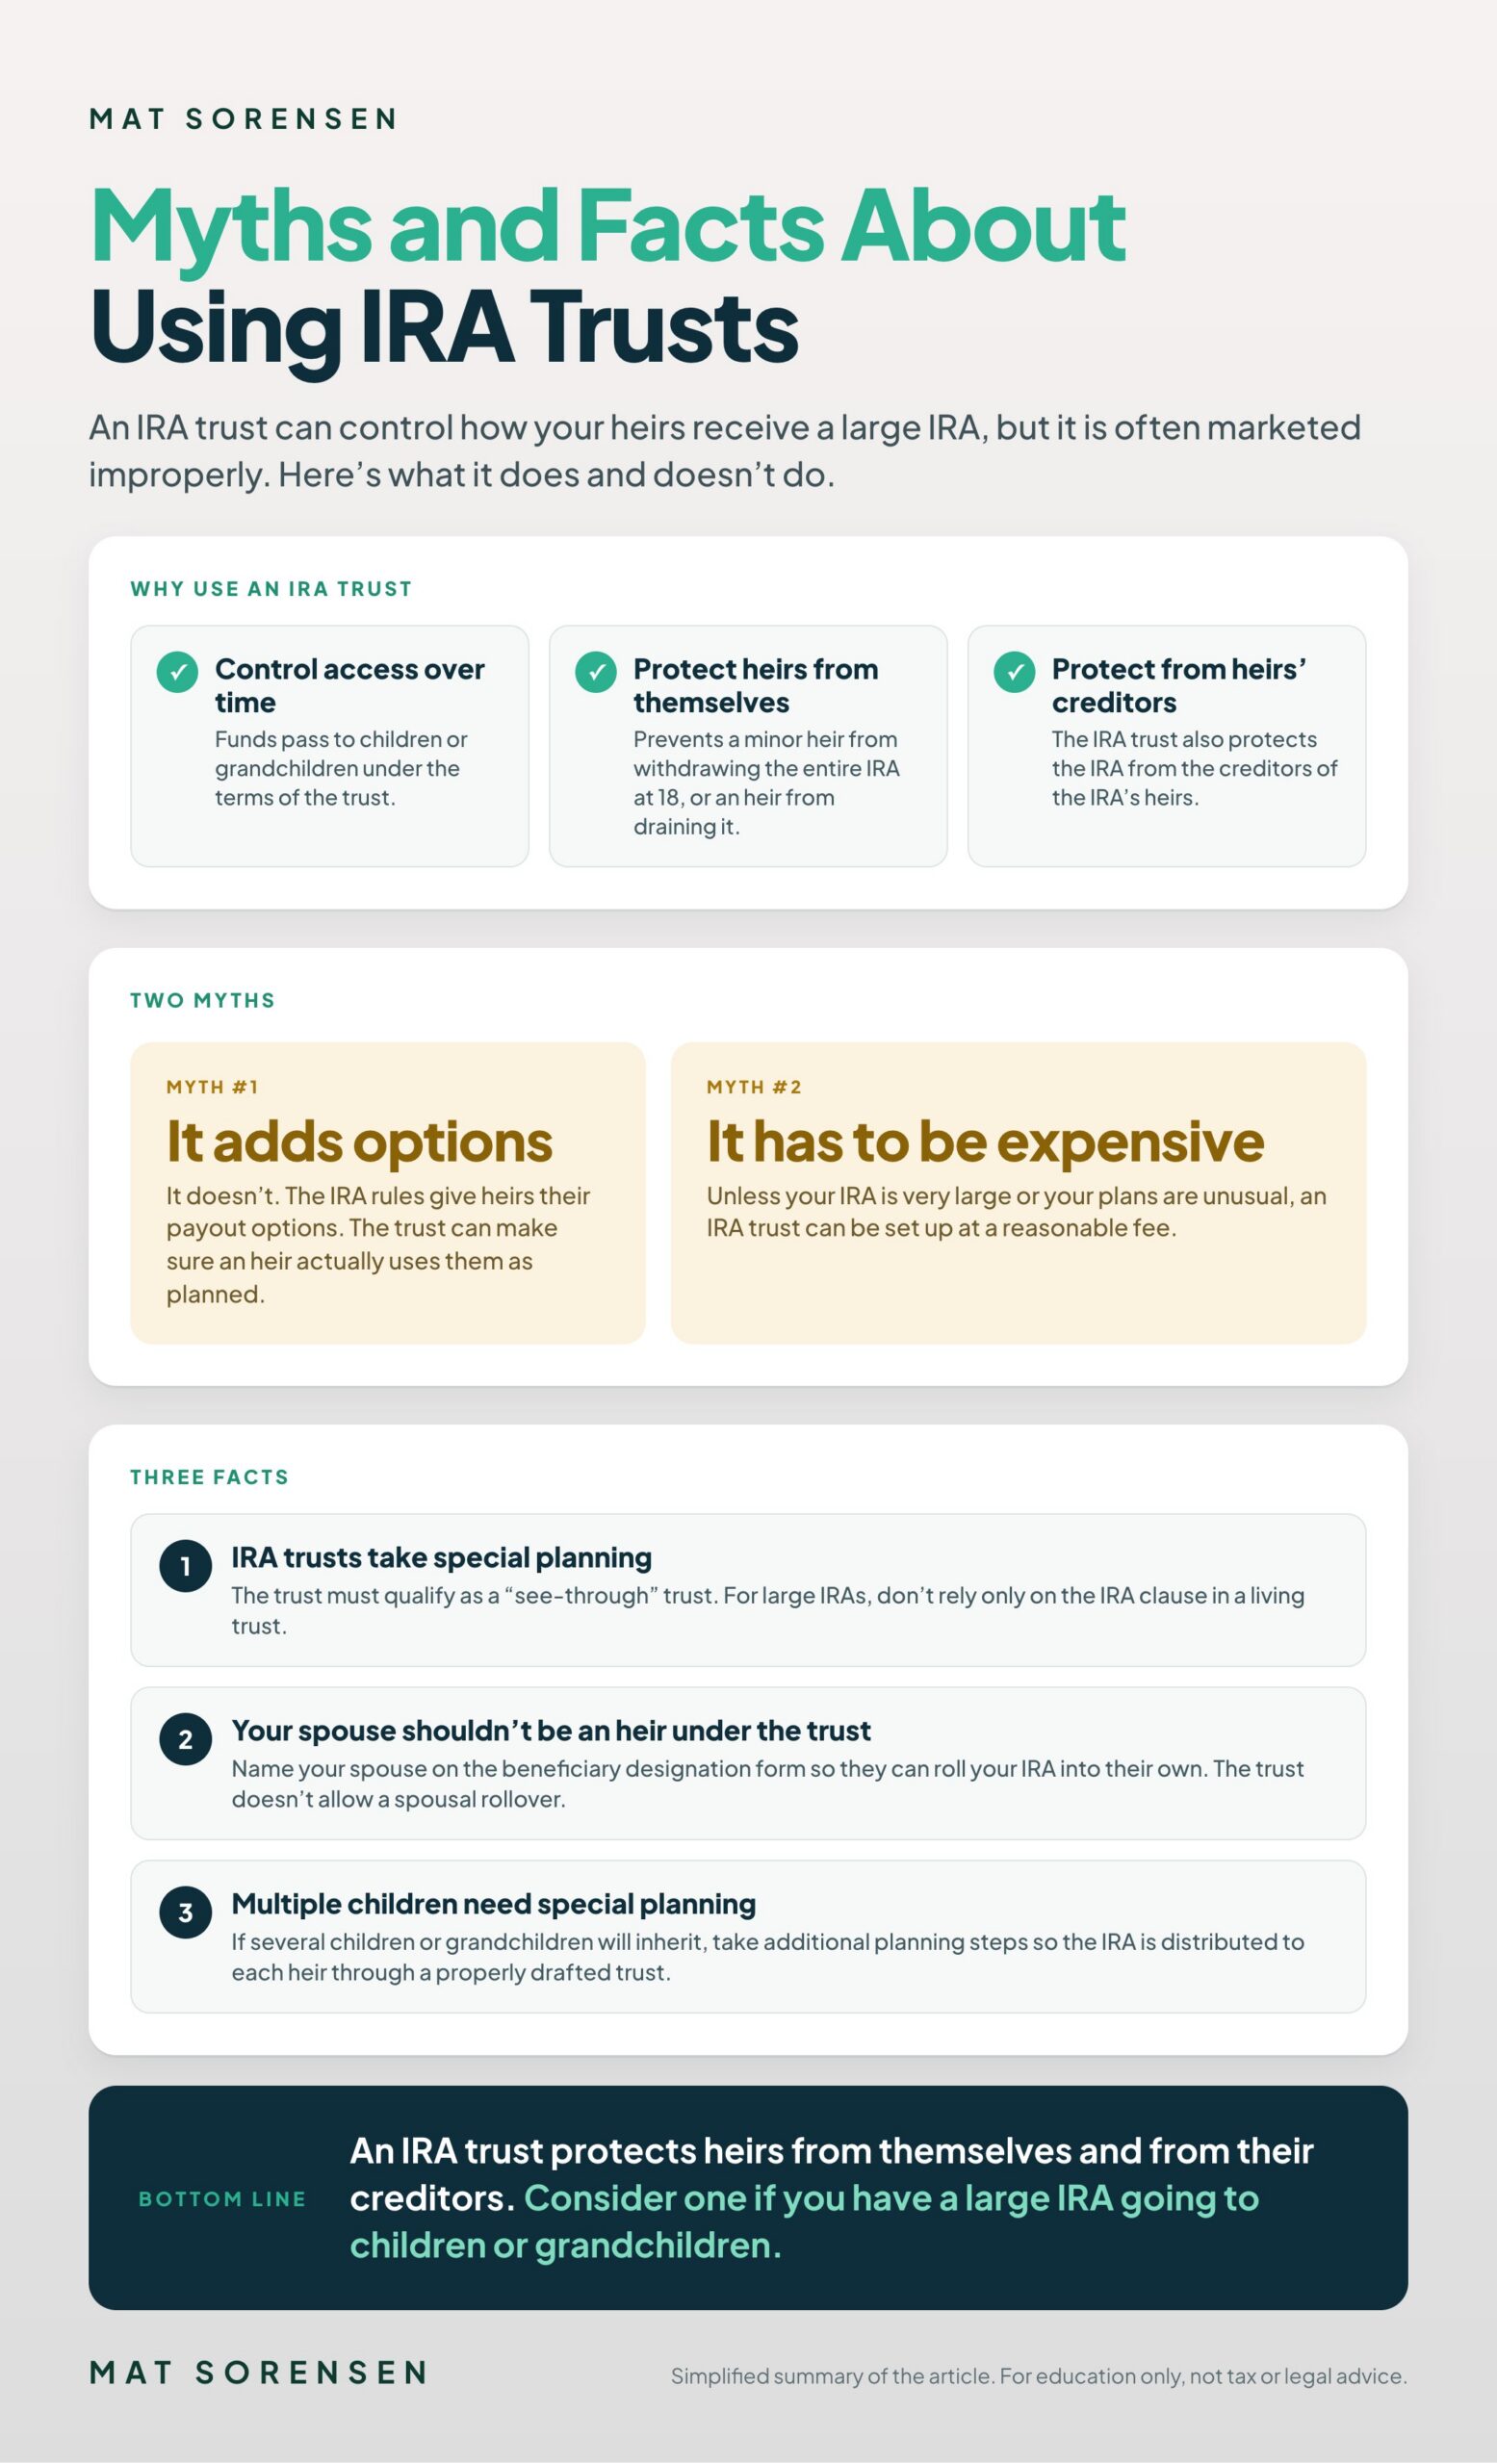
MYTHS AND FACTS ABOUT USING IRA TRUSTS

I’ve had a number of inquiries lately about when to use a separate IRA Trust as the beneficiary of your IRA. IRAs, like bank and savings accounts, are passed on to the heirs of the deceased IRA owner according to the beneficiary designation form that is on file with the IRA custodian. This form will typically list a spouse as beneficiary and then maybe the children of the IRA owner as the contingent beneficiary. In the event that the spouse has already passed away, the IRA would then be inherited by the children listed as contingent beneficiaries. Many individuals with large IRAs would like their IRA accounts to pass on to their children or grandchildren according to the terms of a trust document whereby the funds, and their heirs access to the funds, can be controlled over time.

Infographic: why to use an IRA trust, two common myths about IRA trusts, and three facts about planning one

EXAMPLE

For example, if the IRA owner were to die and pass on the IRA account to a minor beneficiary then that minor could withdraw the entire IRA upon their 18th birthday. Not only is a large sum of money in the hands of a teenager a bad idea, but if the child takes a distribution of the entire sum then it will cause a significant tax liability to the 18 year-old heir that could have otherwise been stretched out over the heir’s lifetime if the IRA has been passed down and distributed over time according to the terms of the IRA Trust. In other words, the legacy left to the child is eaten up by poor tax planning and teenage decision making. 

How Inherited IRAs Are Distributed

UPDATE (NOV 2026)

This article was written in 2015, before the SECURE Act. For owners who died after 2019, the SECURE Act limits the lifetime “stretch” to eligible designated beneficiaries: a surviving spouse, the owner’s minor child (until 21), a disabled or chronically ill beneficiary, or someone not more than 10 years younger than the owner. Most other beneficiaries must empty the account within 10 years, and if the owner had already started RMDs, they also take yearly RMDs during those years (required from 2025). (Source: IRS final regulations, 2024)

When an individual (or properly drafted trust) inherits an IRA, that IRA must be distributed according to the required minimum distribution rules (“RMD”). These rules allow a spouse to roll over the IRA to their own IRA and that is common option for spouses who inherit an IRA. However, children or other beneficiaries who inherit an IRA cannot roll the IRA over to their own IRA but do have the option, if exercised properly, to take the annual RMD over the heirs lifetime. This is a great option for younger heirs (e.g. children or grandchildren) of IRAs as it allows them to keep the IRA in a tax deferred or tax free account for a longer period of time and allows the IRA to continue to stay invested.

That being said, just because an IRA heir is better off taking the IRA and the RMD over their own lives doesn’t mean that they will actually do so as many IRA heirs simply take a lump-sum distribution and subject themselves and their inheritance to significant up-front tax. As a result, many IRAs are better off being distributed over time and an IRA Trust can be used to properly plan and restrict the IRA such that the distributions do occur over time.

Common Myths About IRA Trusts

While the IRA Trust is great for planning the distribution of a large IRA over time, I have seen it marketed improperly to clients and as a result I wanted to clear the air regarding a couple of myths I have seen regarding IRA Trusts.

Myth #1

IRA Trusts do not give an IRA owner the ability to stretch out their IRA any longer than could occur if the IRA named individuals on their IRA beneficiary designation. I recently had a client ask me about an IRA Trust. This client was told that the IRA Trust would allow the IRA owner to pass on their IRA to their children and that the IRA would not need to be distributed within 5 years of the IRA owner’s death but rather could be “stretched-out” and distributed over the lifetime of inheriting child. They were told that the only way to accomplish this “stretch option”, whereby distributions from the IRA occur over the heirs lifetime, was through an IRA Trust. This unfortunately is a half-truth because the IRA Trust is not providing or allowing the “stretch” option. In actuality, the so called stretch option can be achieved simply by naming the younger heirs on the beneficiary designation form. As a result, the IRA Trust should not be set up solely because the IRA owner would like to stretch out the IRA to their heirs. As discussed previously, the IRA Trust can be drafted to ensure that the IRA is actually stretched out and not drained by an heir but it is not the Trust itself that is giving the heir this option. The laws regarding IRAs and RMD already allow the younger heir to inherit the IRA and have it distributed over their lifetime regardless of whether the IRA is inherited via an IRA Trust or not.

Myth #2

IRA Trusts Should Not Cost $5,000. I had a client ask about setting up an IRA Trust and this client was quoted a little over $5,000 by another attorney simply to establish an IRA Trust. While an IRA Trust is its own stand-alone document, it should not cost more than a couple thousand dollars to establish and we can handle them for even less than that. Unless you have a very significant IRA (over a few million dollars) and you have some pretty unusual plans for distributing your IRA, an IRA Trust can be set up at a reasonable fee.

Important Facts About IRA Trusts

Now that we have the myths out of the way, I’d like to make note of three important facts to know about IRA Trust.

Fact #1

IRA Trusts are Unique and Take Special Planning. While an IRA Trust doesn’t need to cost $5,000 to set-up, it also shouldn’t be set up for $99. There are special rules and requirements for IRA Trusts and the Trust needs to be established such that it is a “see-through” trust under law. This requires some special drafting and planning in the estate plan process. While a well drafted revocable living trust should contain a clause regarding IRAs and while it will contain “see-through” trust language for the IRAs, that alone should not be relied on for those persons with large IRAs who would like their IRA to be inherited by younger heirs and distributed over time. As a result, I recommend having a separate IRA Trust to ensure that the IRA is properly distributed and managed upon your death.

Fact #2

Your Spouse Shouldn’t Be an Heir Under an IRA Trust. Spouses should not receive an IRA inheritance through an IRA Trust. Rather, in most situations, they should be listed on the beneficiary designation form of the IRA. The reason for this is simple, spouses can directly inherit an IRA and can roll their deceased spouses IRA over to their own IRA. This spousal rollover isn’t possible with the IRA Trust and in general, the IRA Trust doesn’t need to be used to control distributions of an IRA over time to a spouse in the same way it can be used to distribute an IRA to a child or grandchild.

Fact #3

If Your IRA Is to Be Inherited By Multiple Children Then Special Planning Should be Taken. If you are planning to have your IRA be inherited by multiple children or grandchildren, then special attention must be taken as the rules for Trusts for IRAs states that the RMD rules of the oldest living child listed on the Trust will be used as the RMD for all beneficiaries. This is troublesome for a younger child or grandchild as they could otherwise “stretch-out” their share of IRA distributions over time but if proper planning and drafting doesn’t occur. They may be forced to take distributions from the IRA under a compressed and accelerated RMD schedule based on the oldest living heir that is part of the Trust. Consequently, it is highly recommended that you take additional planning steps to ensure that the IRA is distributed to each child or grandchild through a properly drafted trust so that they can use their own younger life-time in stretching out the IRA and its tax deferred benefits.

In sum, an IRA Trust is a great tool to ensure that assets from an IRA are passed on in the most tax-deferred manner possible. The IRA Trust protects the heirs from themselves, and their potential impulse to drain the IRA, and also protects the IRA from the creditors of the IRA’s heirs. As a result, an IRA Trust should be considered as an additional item for persons with large IRAs who intend to pass on their IRAs or other retirement accounts to children or grandchildren.

INHERITED IRA

Inherited an IRA? Talk with a Directed IRA specialist about your options for self-directing it.

Book a Call with Directed IRA

By: Mat Sorensen, Attorney and Author of The Self Directed IRA Handbook

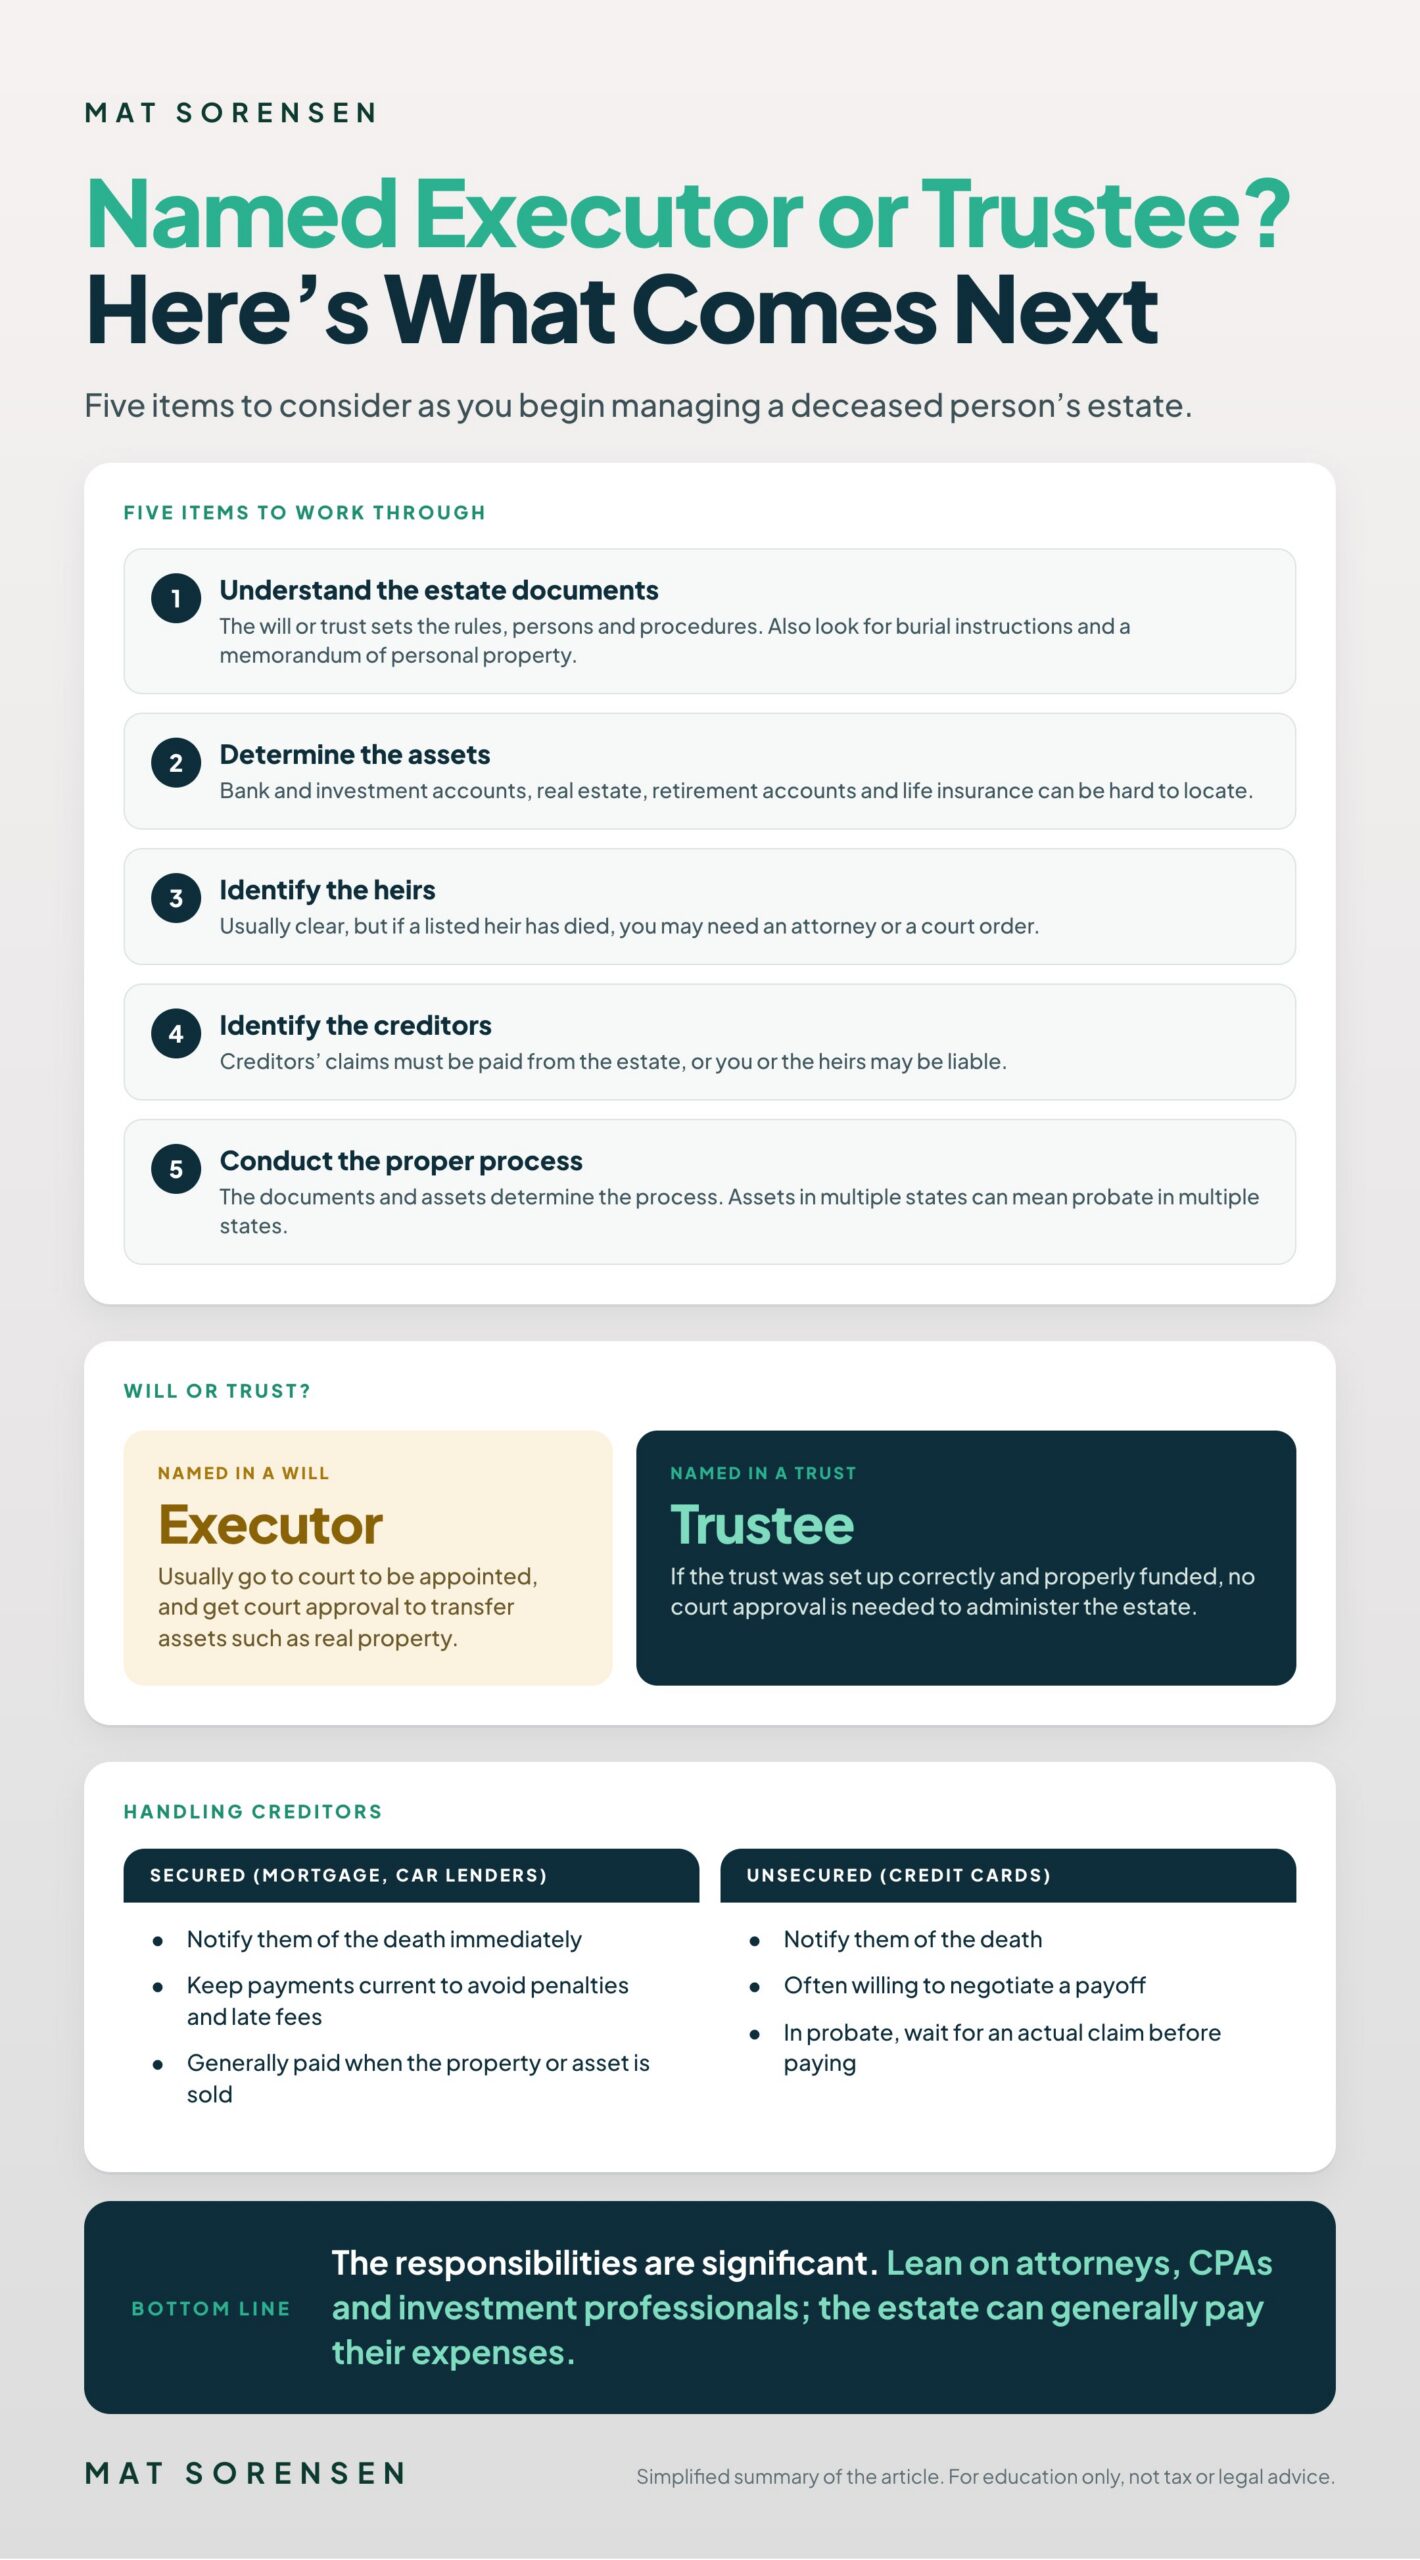
YOU’VE BEEN NAMED AS EXECUTOR OR TRUSTEE TO A DECEASED PERSON’S ESTATE: NOW WHAT?

If you’ve been named as an executor in a will or as a trustee in a trust, you have some important responsibilities and obligations that arise upon the death of a loved one. Here’s a quick list of items to consider as you begin managing a deceased person’s estate.

Infographic: five items to work through as an executor or trustee, will vs. trust, and how to handle secured and unsecured creditors

1. Understand the Estate Documents

The first item to understand is the estate documents. The estate documents will determine the rules, persons, and procedures that will apply to the distribution and management of the estate.

If you were appointed as an executor or personal representative in a will, you will need to understand the terms of the Will and who are the heirs pursuant to the Will. The executor, also known as personal representative, has the authority to administer and distribute the estate. In most situations where only a will is used, you will need to go to court to be appointed as the legal executor of the estate and will need court approval to transfer certain assets such as real property.

If you were appointed as a trustee in a Trust, you will need to understand what assets are owned by the Trust and what assets are owned outside the Trust. In general, a Trust is used by individuals to avoid probate and to provide better direction and control of their estate. If the Trust was established correctly and if it was properly funded (e.g., it owns the assets of the deceased person), then you will not need to go to court to get approval to administer the estate.

In addition to understanding the operative will or trust, you will need to identify other documents that may be included in the estate plan. These documents may include funeral and burial instructions where the deceased person has indicated whether they are to be buried or cremated and what services should accompany their funeral (e.g. church, military). There may also be a memorandum of personal property that outlines how specific items of personal property are to be distributed to heirs. Common items identified and handled on the memorandum of personal property are jewelry, pianos, guns, precious metals, and valuable personal effects.

2. Determine the Assets

You will need to determine what assets are included in the estate. In many instances, this can be difficult to determine, as the deceased person may not have provided complete information as to their bank accounts, investment accounts, real estate, retirement accounts, and life insurance policies. Many children who become executors and trustees have a difficult time locating the assets of their deceased family member despite having an otherwise close relationship.

3. Identify the Heirs

Most estate documents such as a will or a trust will list the heirs to the estate and these heirs (aka, beneficiaries) are whom you are serving for as executor or trustee of the estate. In most instances, the heirs are clearly identified. However, what happens if the will or trust listed one of your siblings as an heir and what if that sibling is no longer living? Does that portion of the estate go to your sibling’s surviving spouse or children or to the other siblings? Ideally, the will or trust will state what shall occur in this instance but in many instances this item can be overlooked and not considered in the estate plan. As a result, as executor or trustee, you are left to determine who shall take the place of your deceased sibling and this decision is subject to the terms of the document and state laws. In general, you will need to seek the guidance of an attorney and those legal expenses shall be paid and/or reimbursed to you by the estate. Depending on the terms of the documents and the heirs involved, you may need to get a court order to identify and determine heirs.

4. Identify the Creditors

Almost every estate has creditors who need to be paid. From credit card companies and other consumer debt to mortgage lenders with liens on real estate owned by the deceased. As executor or trustee of the estate, you have an obligation and responsibility to ensure that all creditors’ claims are paid from the estate.

WATCH OUT

Failure to do so may result in liability to you as the executor or trustee or to the heirs who receive distributions from the estate that should otherwise have been paid to creditors.

Whether you are working with a secured or unsecured creditor, you will need to provide evidence of your position as executor or trustee, which in the case of a Will would include a copy of the Will or in the case of a Trust would include a copy of the certificate of trust.

Secured Creditors

In general, secured creditors such as mortgage lenders or car lenders will be paid upon the sale of the property or asset unless the estate otherwise has cash available and intends to hold these assets. Regardless of whether the asset will be held or sold, you should immediately notify secured creditors of the death of the deceased person. Where possible, you should ensure that payments are made to these creditors so that penalties and late fees do not accrue to the estate. If properties or assets subject to the secured creditor are paid, then the proceeds from the sale will resolve these debts.

Unsecured Creditors

As to unsecured creditors, you should notify them of the passing of your loved one. However, these creditors are not always paid in full. From personal experience in handling estates, I have found that unsecured creditors, such as credit card companies, will generally negotiate amounts owed to close the account. Maybe start with an offer of 1/3 of the amount owed and see if the unsecured creditor will accept that amount as a payoff. While they do have legal recourse against the estate, they do face significant legal fees in probate court to collect on the debt.

If the estate must be probated in court, as will typically occur if there is only a will, then as executor you are required to notify creditors of the probate court action and of the assets of the estate. Un-secured creditors then have a certain amount of time to assert their claim against the estate. I have been surprised at how many unsecured creditors actually follow up and make a claim against the estate despite being given notice of the assets of the estate.

TIP

As a result, look to negotiate with these creditors and if you are in probate already, wait until they actually make a claim in the probate court (following notice of the case and deceased person’s death you will be required to provide) before paying those creditors. You have a good chance that the creditor won’t even make a claim.

5. Conduct the Proper Process

The estate documents and the assets of the deceased will determine the process to administer the estate. Also, if the deceased person had assets in multiple states if they only left a will, you may need to conduct probate in multiple states.

There are a number of common situations where you will need to go to court to obtain court approval in administering the estate.

  • ✓First, in the case of a will, you will typically need to go to probate court to be appointed as executor by the Court and to get court approval to transfer any real estate assets to heirs or in a sale from the estate.
  • ✓Second, if the identity of heirs is in question, you may need to get approval from the court as to the proper heirs to receive proceeds from the estate.
  • ✓And third, you may be required to go to Court if the estate documents leave contradictory, improper, or confusing provisions that cause disagreement amongst heirs. In this situation, obtaining approval from the court is advisable in order to avoid claims against yourself and the estate.

File the Required Tax Returns

As executor or trustee, you must also ensure that appropriate individual income tax returns and estate tax returns are filed. There are important procedures to follow when filing a deceased person’s final tax return. For example, you must write the word DECEASED across the top of the tax return. In addition to a final income tax return, for the deceased, you may be required to file an income tax return for the estate using IRS form 1041. This is required if the estate receives $600 or more in gross income.

Get Help From Professionals

In short, the responsibilities of an executor and trustee to an estate are significant. As an executor or trustee, you should seek out licensed professionals to advise you in the process. Whether these are attorneys, CPAs, or investment professionals, their expertise can aid you in quickly understanding and completing the tasks that are part of your responsibility as an executor or trustee. Keep in mind, the estate can pay the expenses of professionals and if you incur out-of-pocket expenses as executor or trustee then the estate can typically reimburse those expenses. In most situations, you are not paid to serve as executor or trustee, unless the estate docs provide for such compensation.