Roth IRAs: Other Perks on Top of Tax-Free Growth
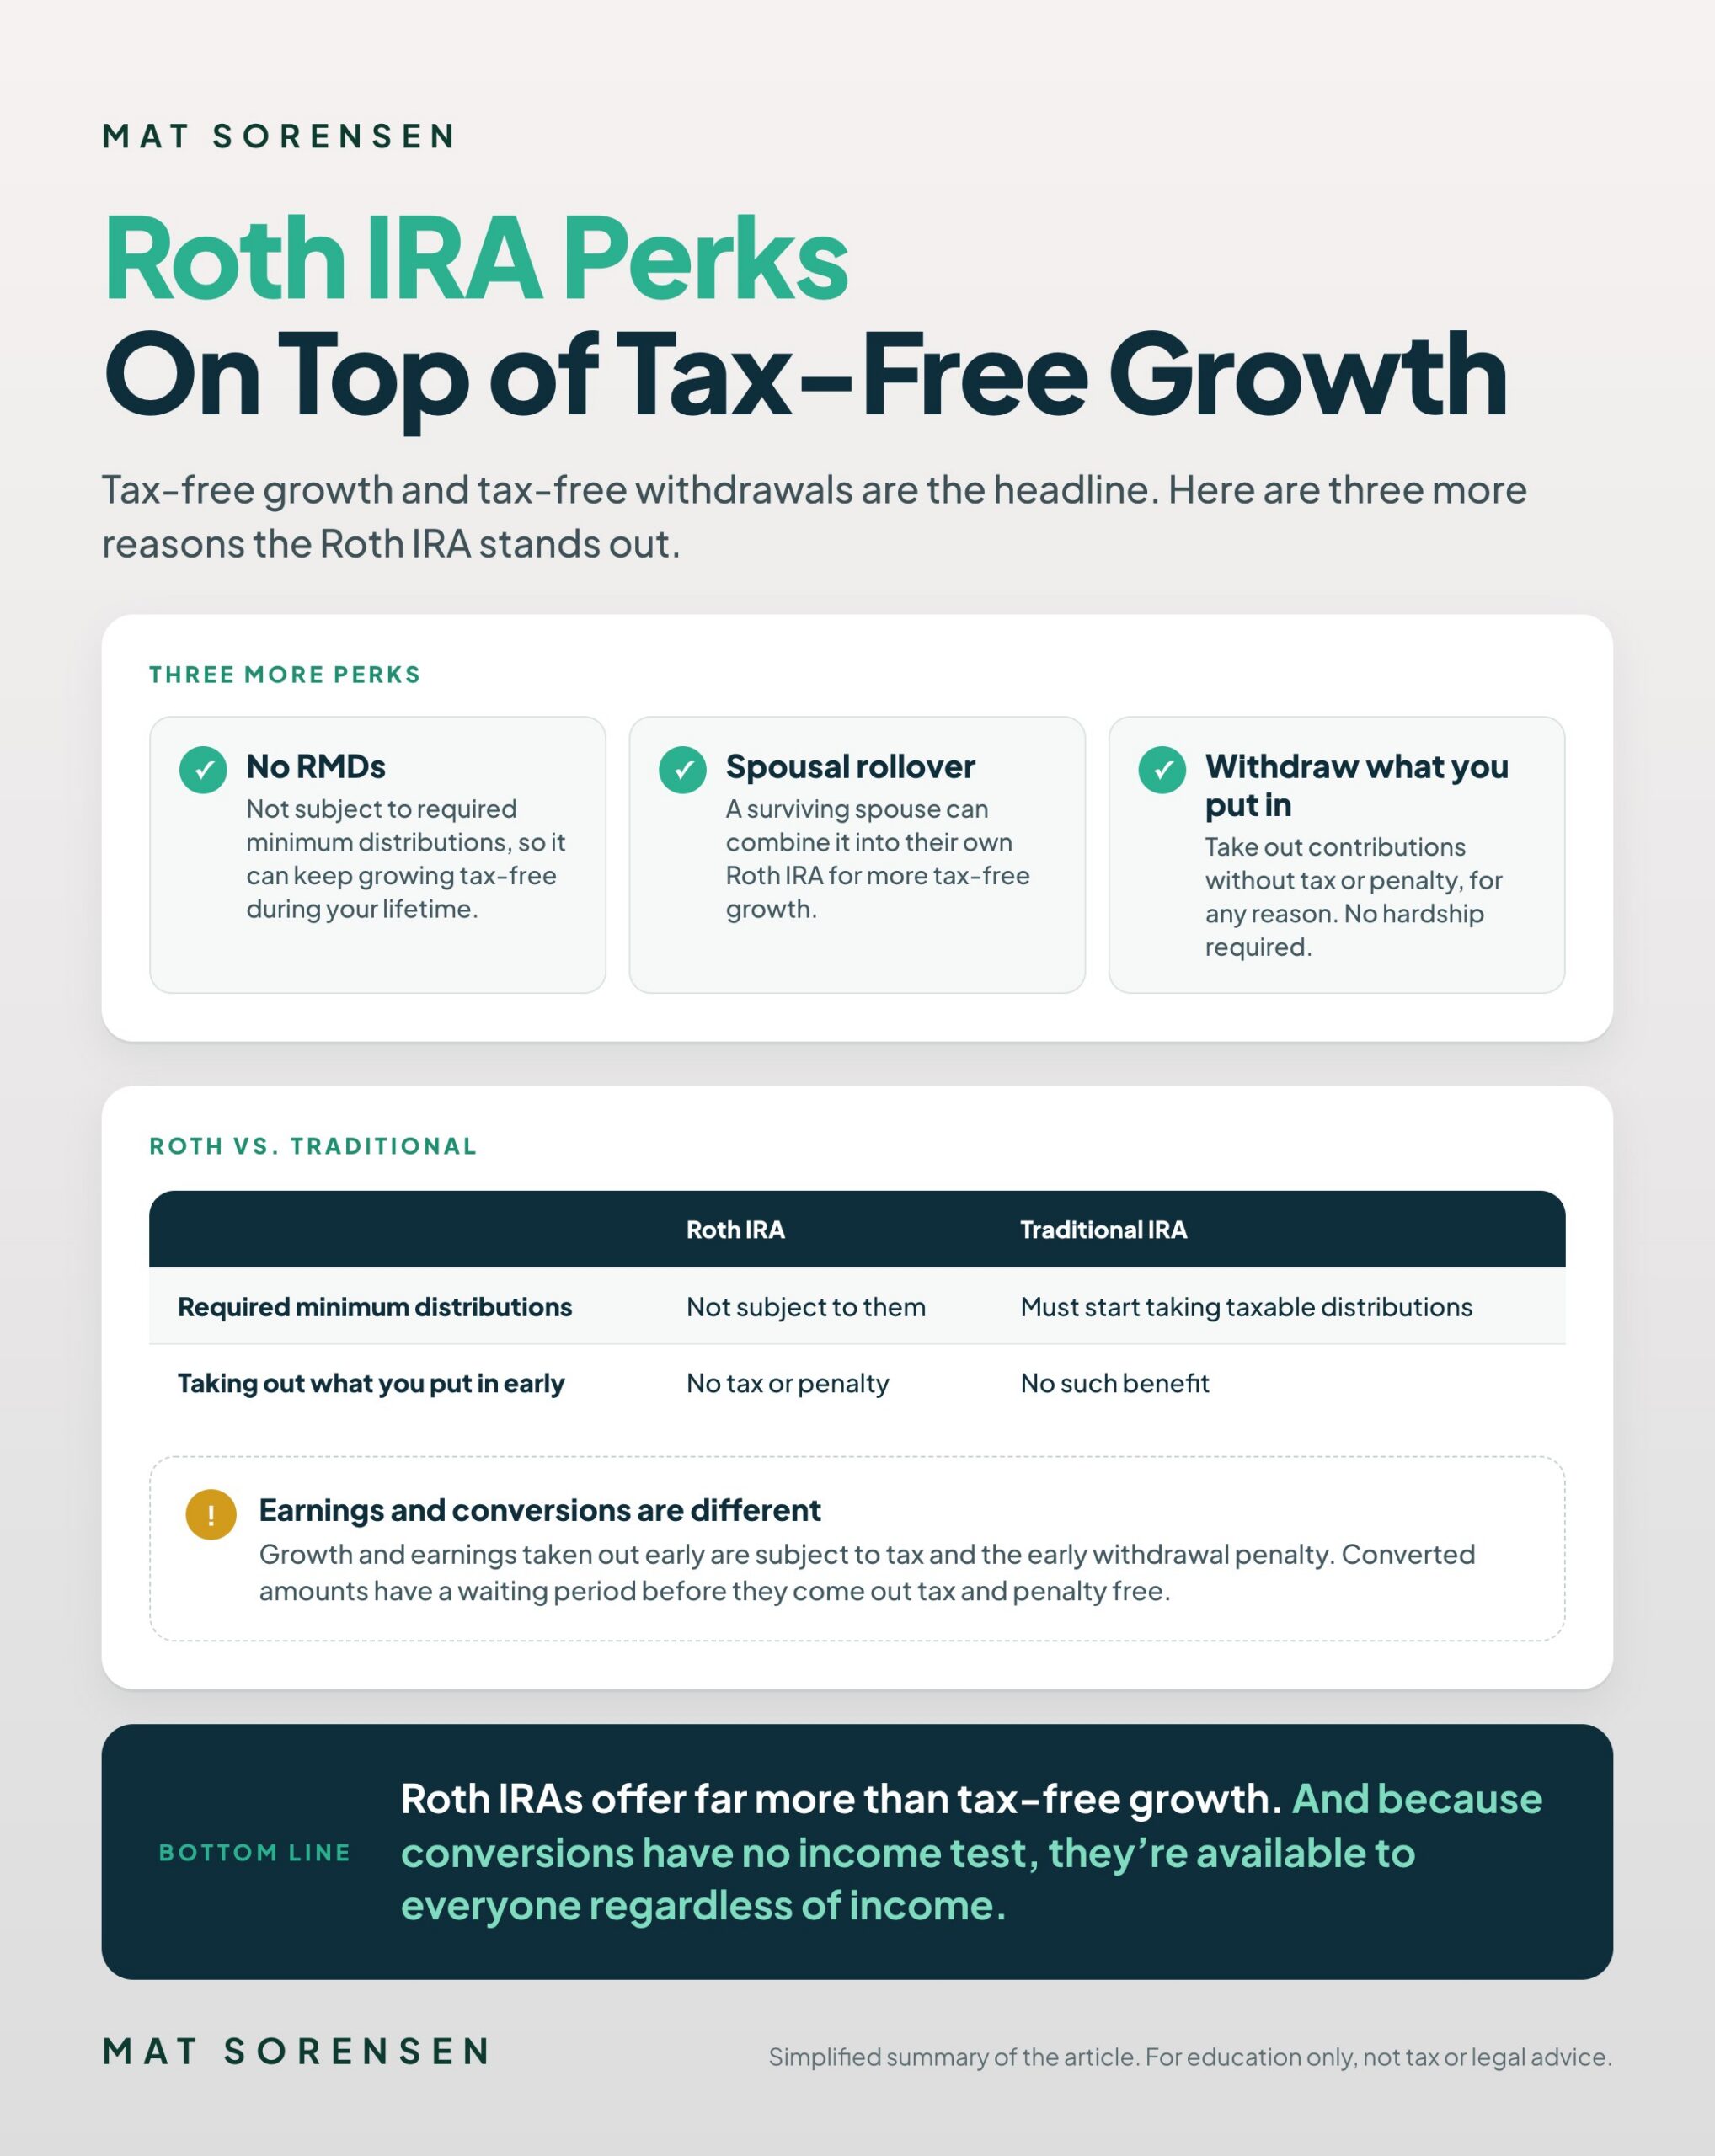
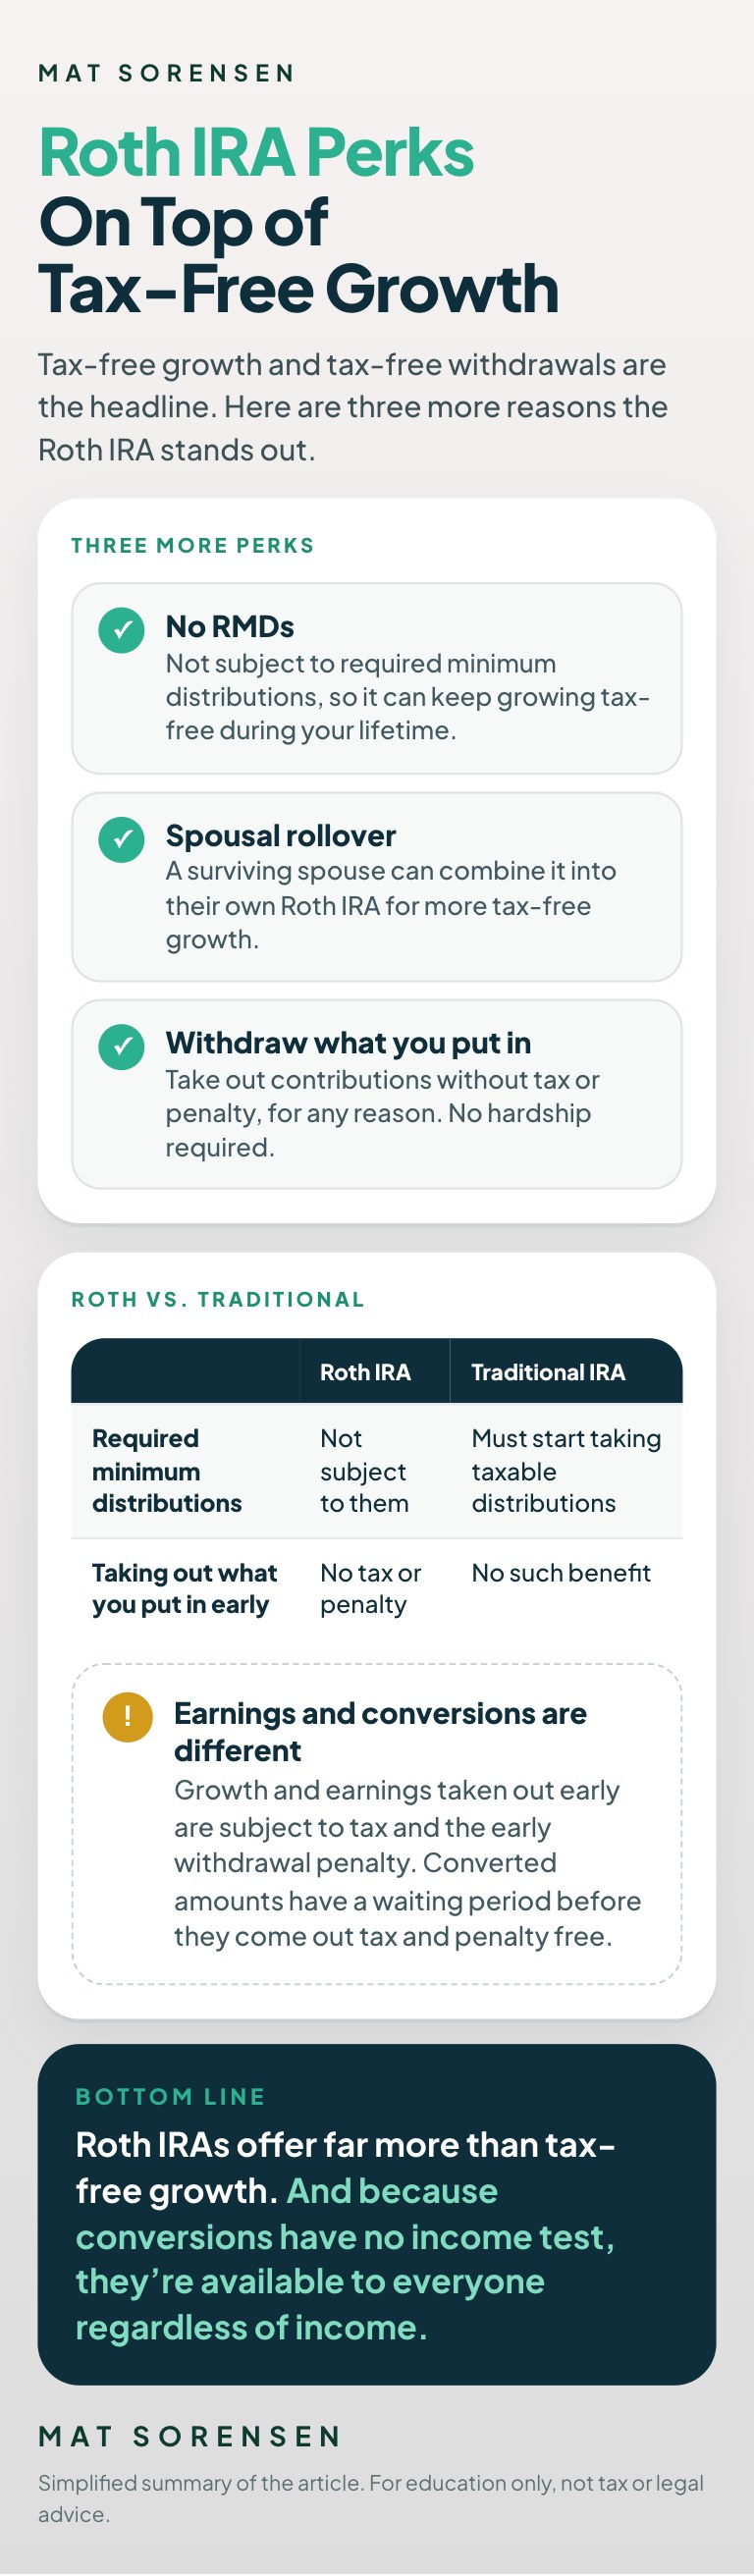
Many investors and financial professionals are familiar with the primary benefits of a Roth IRA: that the plan’s investments grow tax-free and come out tax-free. But if tax-free investing isn’t enough to get you excited, rest assured, there are more benefits to the Roth IRA. I’ll note just three more in this article.
Remember, Roth IRAs are for nearly everyone with earned income. They’re not restricted to high income earners. Check out my prior article here if you’re unfamiliar with the back-door Roth IRA. Okay, now let’s go over the other perks of Roth IRAs.
No Required Minimum Distributions
First, Roth IRAs are not subject to RMD. Traditional retirement plan owners are subject to rules known as Required Minimum Distribution rules which require the account owner to start taking distributions and paying tax on the distributions (since traditional plan) when the account owner reaches the age of 73. Not being subject to RMD rules allows the Roth IRA to keep accumulating tax free income (free of capital gain or other taxes on its investment returns) and allows the account to continue to accumulate tax free income during the account owner’s lifetime. Learn more about the facts and fiction about IRA RMDs here.
Spousal Rollover: The Best Asset to Leave to Your Spouse
Second, a surviving spouse who is the beneficiary of a Roth IRA can continue contributing to that Roth IRA or can combine that Roth IRA into their own Roth IRA. Allowing the spouse beneficiary to take over the account allows additional tax free growth on investments in the Roth IRA account. Non spouse beneficiaries (e.g. children of Roth IRA owner) cannot make additional contributions to the inherited Roth IRA and cannot combine it with their own Roth IRA account. The non-spouse beneficiary becomes subject to required minimum distribution rules but can delay out required distributions up to 5 years from the year of the Roth IRA account owner’s death and is able to continue to keep the tax free return treatment of the retirement account for 5 years after the death of the owner. The second option for non-spouse beneficiaries is to take withdrawals of the account over the lifetime expectancy of the beneficiary (the younger the beneficiary the longer they can delay taking money out of the Roth IRA). The lifetime expectancy option is usually the best option for a non-spouse beneficiary to keep as much money in the Roth IRA for tax free returns and growth.
UPDATE (NOV 2026)
For owners who died after 2019, the SECURE Act limits the lifetime “stretch” to eligible designated beneficiaries: a surviving spouse, the owner’s minor child (until 21), a disabled or chronically ill beneficiary, or someone not more than 10 years younger than the owner. Most other beneficiaries must empty the account within 10 years, and if the owner had already started RMDs, they also take yearly RMDs during those years (required from 2025). (Source: IRS final regulations, 2024)
Tax and Penalty Free Withdrawals Before Age 59 ½ On What You Put In
Third, Roth IRA owners are not subject to the 10% early withdrawal penalty for distributions they take before age 59 ½ on amounts that are comprised of contributions or conversions. Growth and earnings are subject to the early withdrawal penalty and taxes too, but you can always take out the amounts you contributed to your Roth IRA or the amounts that you converted without paying taxes or penalties (note that conversions have a 5 year wait period before you can take out funds penalty and tax free). This makes the Roth IRA the most powerful savings account out there because you can take out what you put in without penalty or tax for whatever reason you may have as hardship is not required. Traditional IRAs have no such benefits.
Roth IRAs are a great tool for many investors. Keep in mind that there are qualification rules to being eligible for a Roth IRA that leave out many high income individuals. However, you can convert your traditional retirement plan dollars to a Roth IRA (sometimes known as a backdoor Roth IRA) as the conversion rules do not have an income qualification level requirement on converted amounts to Roth IRAs. This conversion option has in essence made Roth IRAs available to everyone regardless of income.
FREE SELF-DIRECTED IRA GUIDE
Learn how a self-directed Roth IRA can invest in real estate, private companies, notes, and more, and keep the growth tax-free.
Get the Free Self-Directed IRA Guide
Prefer to talk it through? Book a call with a Directed IRA specialist