How the “Buy, Borrow, Die” Strategy Builds Wealth and Avoids Taxes

What if you could access millions in wealth without selling your assets—or paying a dime in taxes? That’s exactly what the wealthiest Americans have been doing for decades using a strategy called Buy, Borrow, Die.

While it may sound like a clickbait slogan, this approach is a time-tested way to build and preserve wealth. And despite what you may think, it’s not just for billionaires. Everyday investors use the same strategy with brokerage accounts, real estate, and small businesses.

In this article, we’ll break down how Buy, Borrow, Die works, why it’s so effective, and how you can start using it to grow your wealth while minimizing taxes—legally.
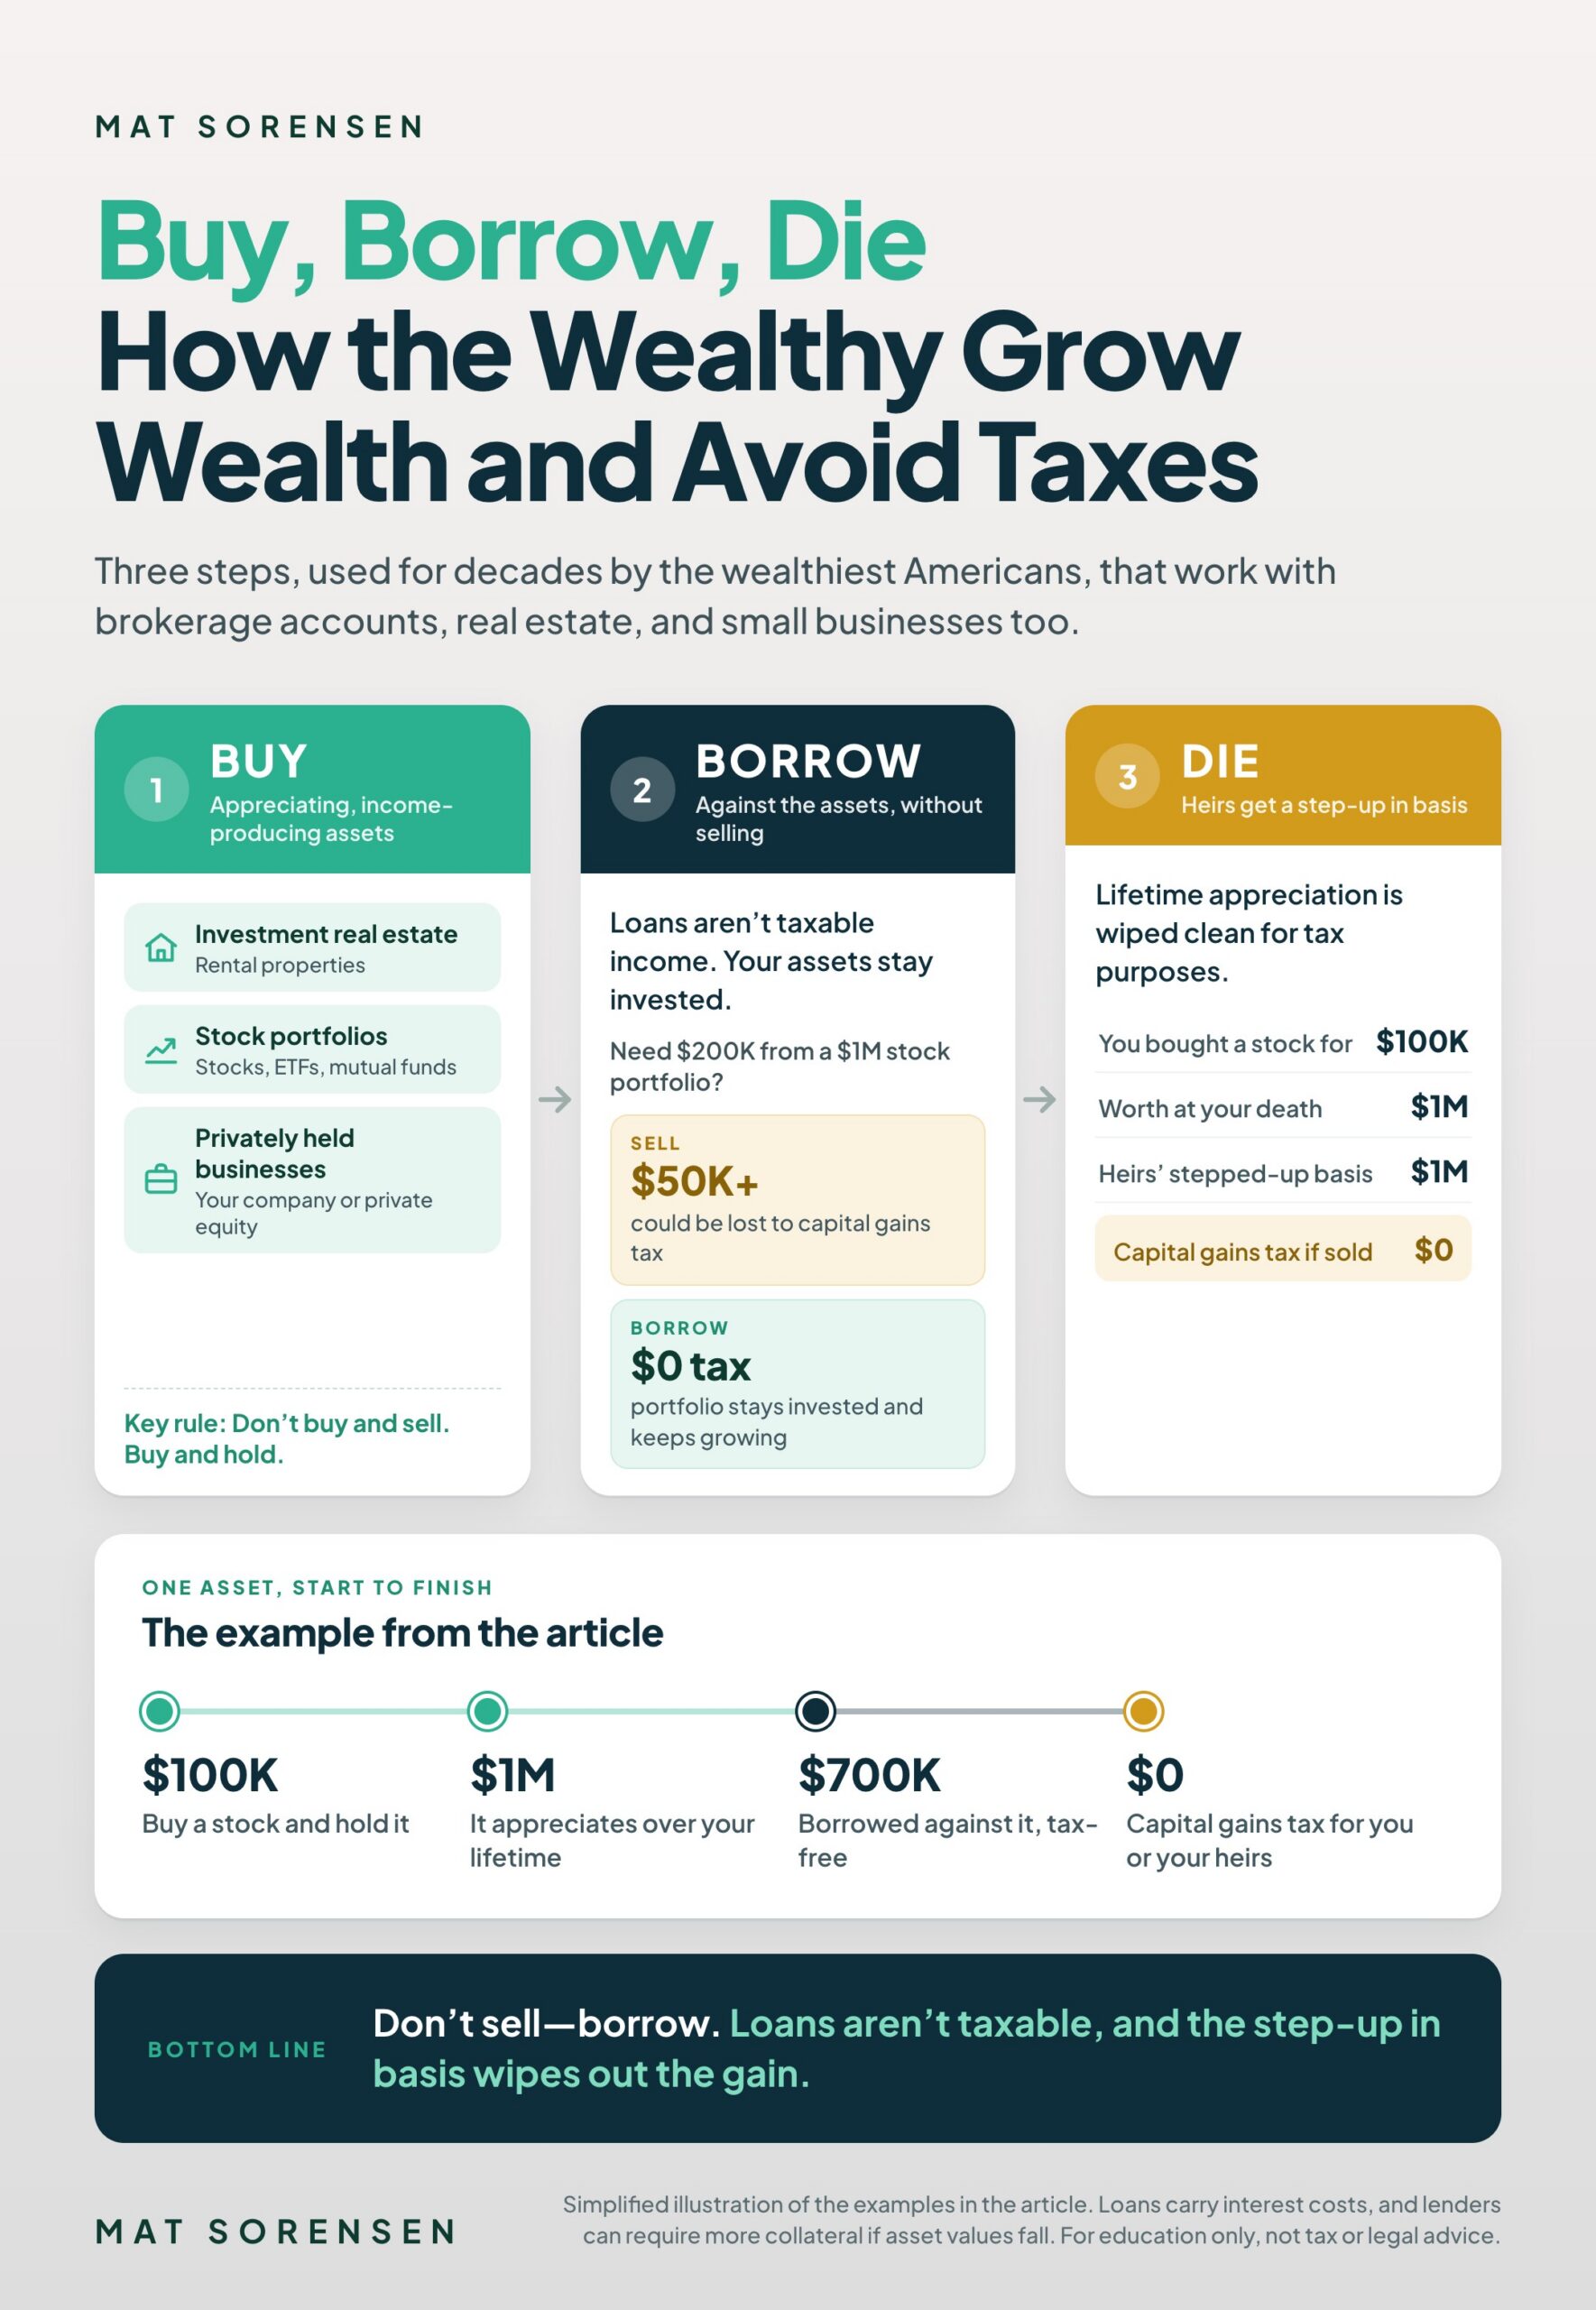
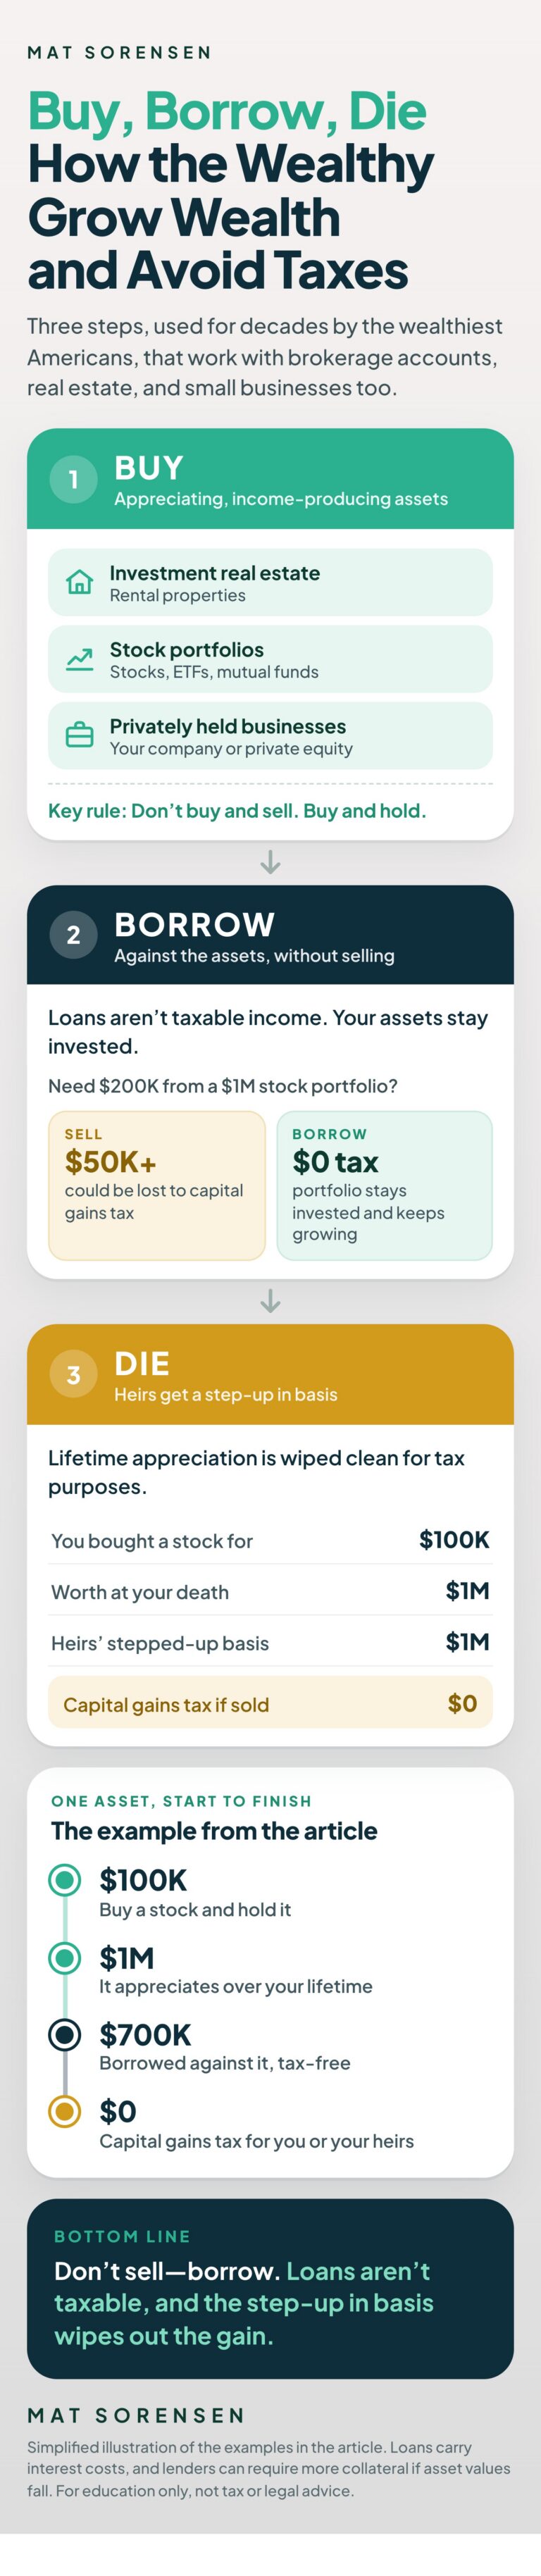
Infographic: the Buy, Borrow, Die strategy in three steps. Buy appreciating assets, borrow against them instead of selling, and heirs receive a step-up in basis

Step 1: Buy Appreciating, Income-Producing Assets

The first step is buying assets you understand—those that generate income and have the potential to appreciate over time.

Think:

Investment real estate (rental properties)

Stock Portfolios (stocks, ETFs, mutual funds)

Privately held businesses (your own company or private equity)

These assets grow over time and, in many cases, generate cash flow along the way via rental income or dividends. That means they not only increase your net worth, they also create ongoing income—which sets the stage for the “borrow” part of the strategy.

Key Rule: Don’t buy and sell. Buy and hold. That’s where real wealth is built.

Step 2: Borrow Against the Assets (Without Selling)

This is where most of the tax planning magic happens.

Rather than selling your appreciated assets—and triggering capital gains tax—you borrow against them. Equity in assets accessed via a loan isn’t taxable income. That means you can unlock your wealth without selling assets or owing the IRS.

Two Common Borrowing Scenarios for Building Wealth

1

Brokerage Account

Let’s say you’ve built a $1M stock portfolio. You need $200K for a large expense—could be taxes, a business opportunity, or even a major life event.

Option A: Sell investments

You trigger capital gains tax. Depending on your bracket and state, you could lose $50K or more just in taxes.

Option B: Borrow against your portfolio

You pay no tax. Your portfolio stays fully invested and continues to grow.

This strategy is called securities-based lending. With a securities-backed line of credit, firms like JP Morgan, Wells Fargo, or your private bank will lend you 70–90% of your portfolio’s value, using your stocks, bonds, or mutual funds as collateral.

  • ✓Stay invested
  • ✓Access low-interest liquidity
  • ✓Avoid triggering capital gains tax

Bottom line: You get the cash you need—without dismantling your long-term investment plan.

Borrowing vs. Liquidating a $10M Portfolio
Client ANot using a line of credit Client BUsing a line of credit
Balanced portfolio $10,000,000 $10,000,000
Liquidation amount $3,000,000 $0
Remaining investment $7,000,000 $10,000,000
Total portfolio return $483,000 $690,000
Total loan cost $0 ($58,500)
Net portfolio return $483,000 $631,500
Value added by using a line of credit — $148,500
Source: J.P. Morgan Private Bank illustration. Rather than liquidating investments, Client B used a line of credit to cover an unexpected liquidity need.

📉 See chart above: Client B uses a line of credit instead of liquidating assets. They keep their portfolio fully invested, pay minimal loan interest, and walk away with $148,500 more in net returns.

2

Investment Real Estate (Cash-Out Refi)

Own a $1M rental property with equity? Use a cash-out refinance to pull $700K without selling. You still own the asset, still collect rent, and you pay no tax on the money you borrowed.

Step 3: Die (and Pass It on Tax-Free)

Let’s be honest—this is the least fun part of the strategy. But it’s one of the most powerful.

When you die, your heirs receive a step-up in basis. That means all of the appreciation during your lifetime—stocks, real estate, businesses—is wiped clean from a tax standpoint.

Let’s say:

You bought a stock for $100K

It’s worth $1M when you pass away

You borrowed $700K against it during your lifetime

Your heirs inherit the asset at a $1M stepped up basis – which means they can sell it the next day for $1M and pay zero capital gains tax. The $700K loan is paid off, and the rest goes to them tax-free. In the end neither you nor your heirs paid capital gains tax.

Why This Strategy Works (Even If You’re Not a Billionaire)

You don’t need a $10M portfolio to use this. In fact, many investors use this strategy with:

$250K brokerage accounts

A single rental property

Business equity

Here’s why it works:

  • ✓Loans are not taxable
  • ✓Assets keep appreciating
  • ✓You avoid selling (and shrinking) your net worth
  • ✓Your heirs benefit from a tax-free step-up in basis

Congress has taken notice and bills have been introduced to limit or eliminate the step-up in basis. There have even been bills intended to tax you when you access equity in an asset via a loan. Those bills have all failed. For now, Buy, Borrow, Die remains one of the most powerful—and legal—wealth-building and tax-saving strategies available.

Key Takeaways

  • ✓Buy assets that appreciate and produce income
  • ✓Don’t sell—borrow
  • ✓Loans are not taxable income
  • ✓Borrowing allows you to enjoy your wealth without shrinking your net worth
  • ✓Your heirs can inherit assets tax-free with a step-up in basis
  • ✓This strategy works for real estate, stock portfolios, and even businesses

Ready to Build Your Wealth—Step by Step?

The Buy, Borrow, Die strategy is just one piece of a bigger picture. If you want to know where to start and what to do next, download Mat’s guide on the Ideal Order of Investing.

Whether you’re just getting started or ready to expand into real estate, Roth IRAs, or alternative assets—this is the roadmap.

Download the Free Guide: The Ideal Order of Investing

Take control of your financial future—one smart move at a time.
What to Do with a 401(k) When You Leave Your Employer

For many Americans, their 401(k) is their largest investment account—and the main source of income they’re counting on for retirement. But when you leave your job, what happens to that money? What’s the best move to keep your savings protected and growing?

The wrong decision could cost you thousands in taxes, penalties, or missed investment opportunities. In this guide, we’ll break down everything you need to know about your 401(k) after leaving an employer—including vesting rules, rollover options, and tax implications—so you can make the best choice for your financial future.

Let’s go over your options, the pros and cons of each, and how to roll over your 401(k) the right way—without triggering unnecessary taxes or penalties.

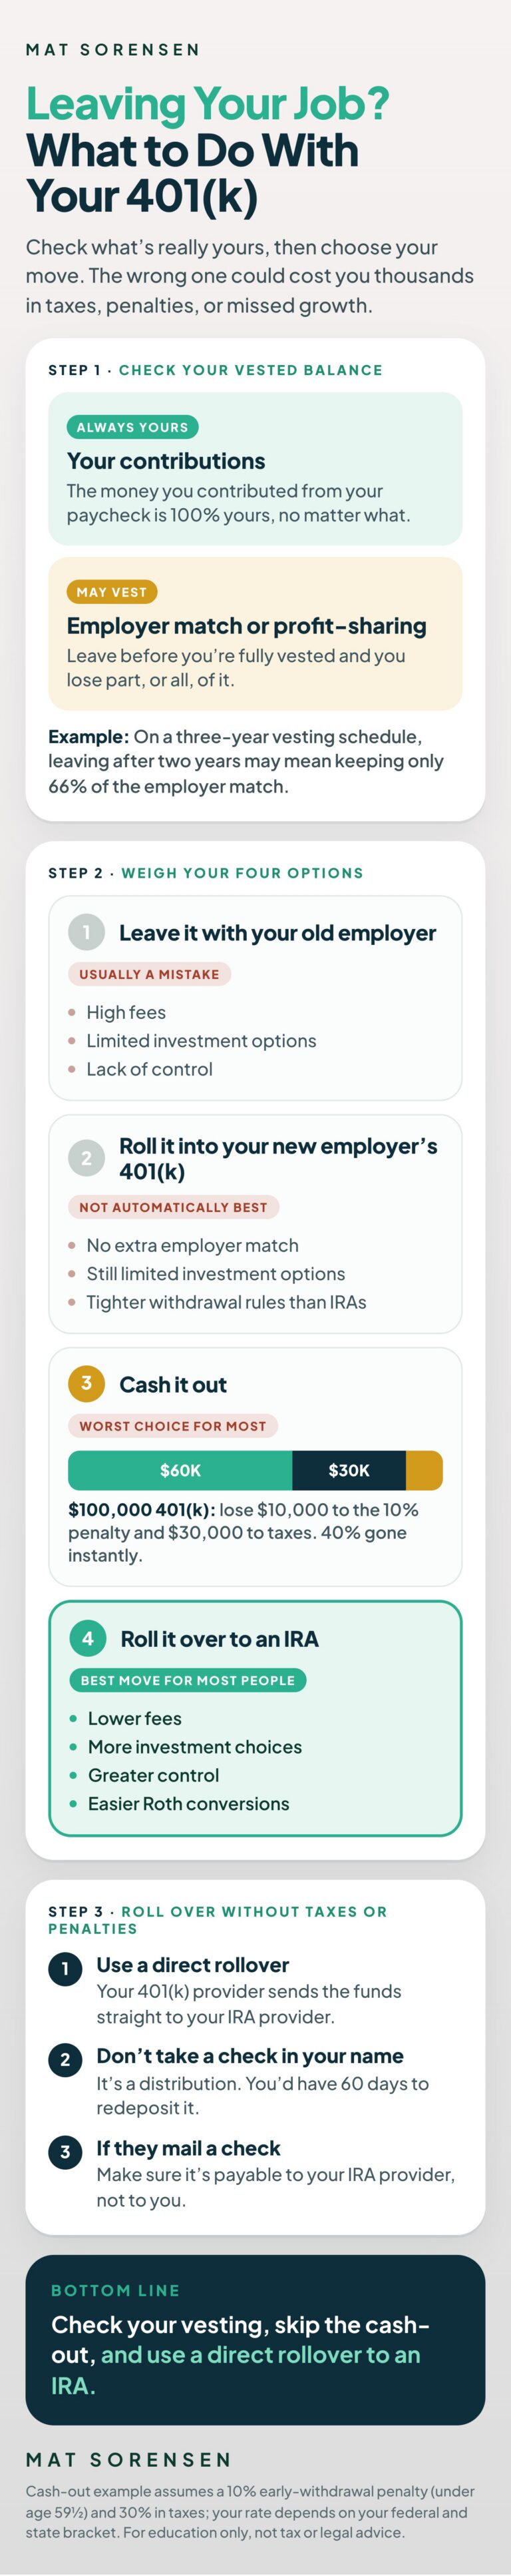
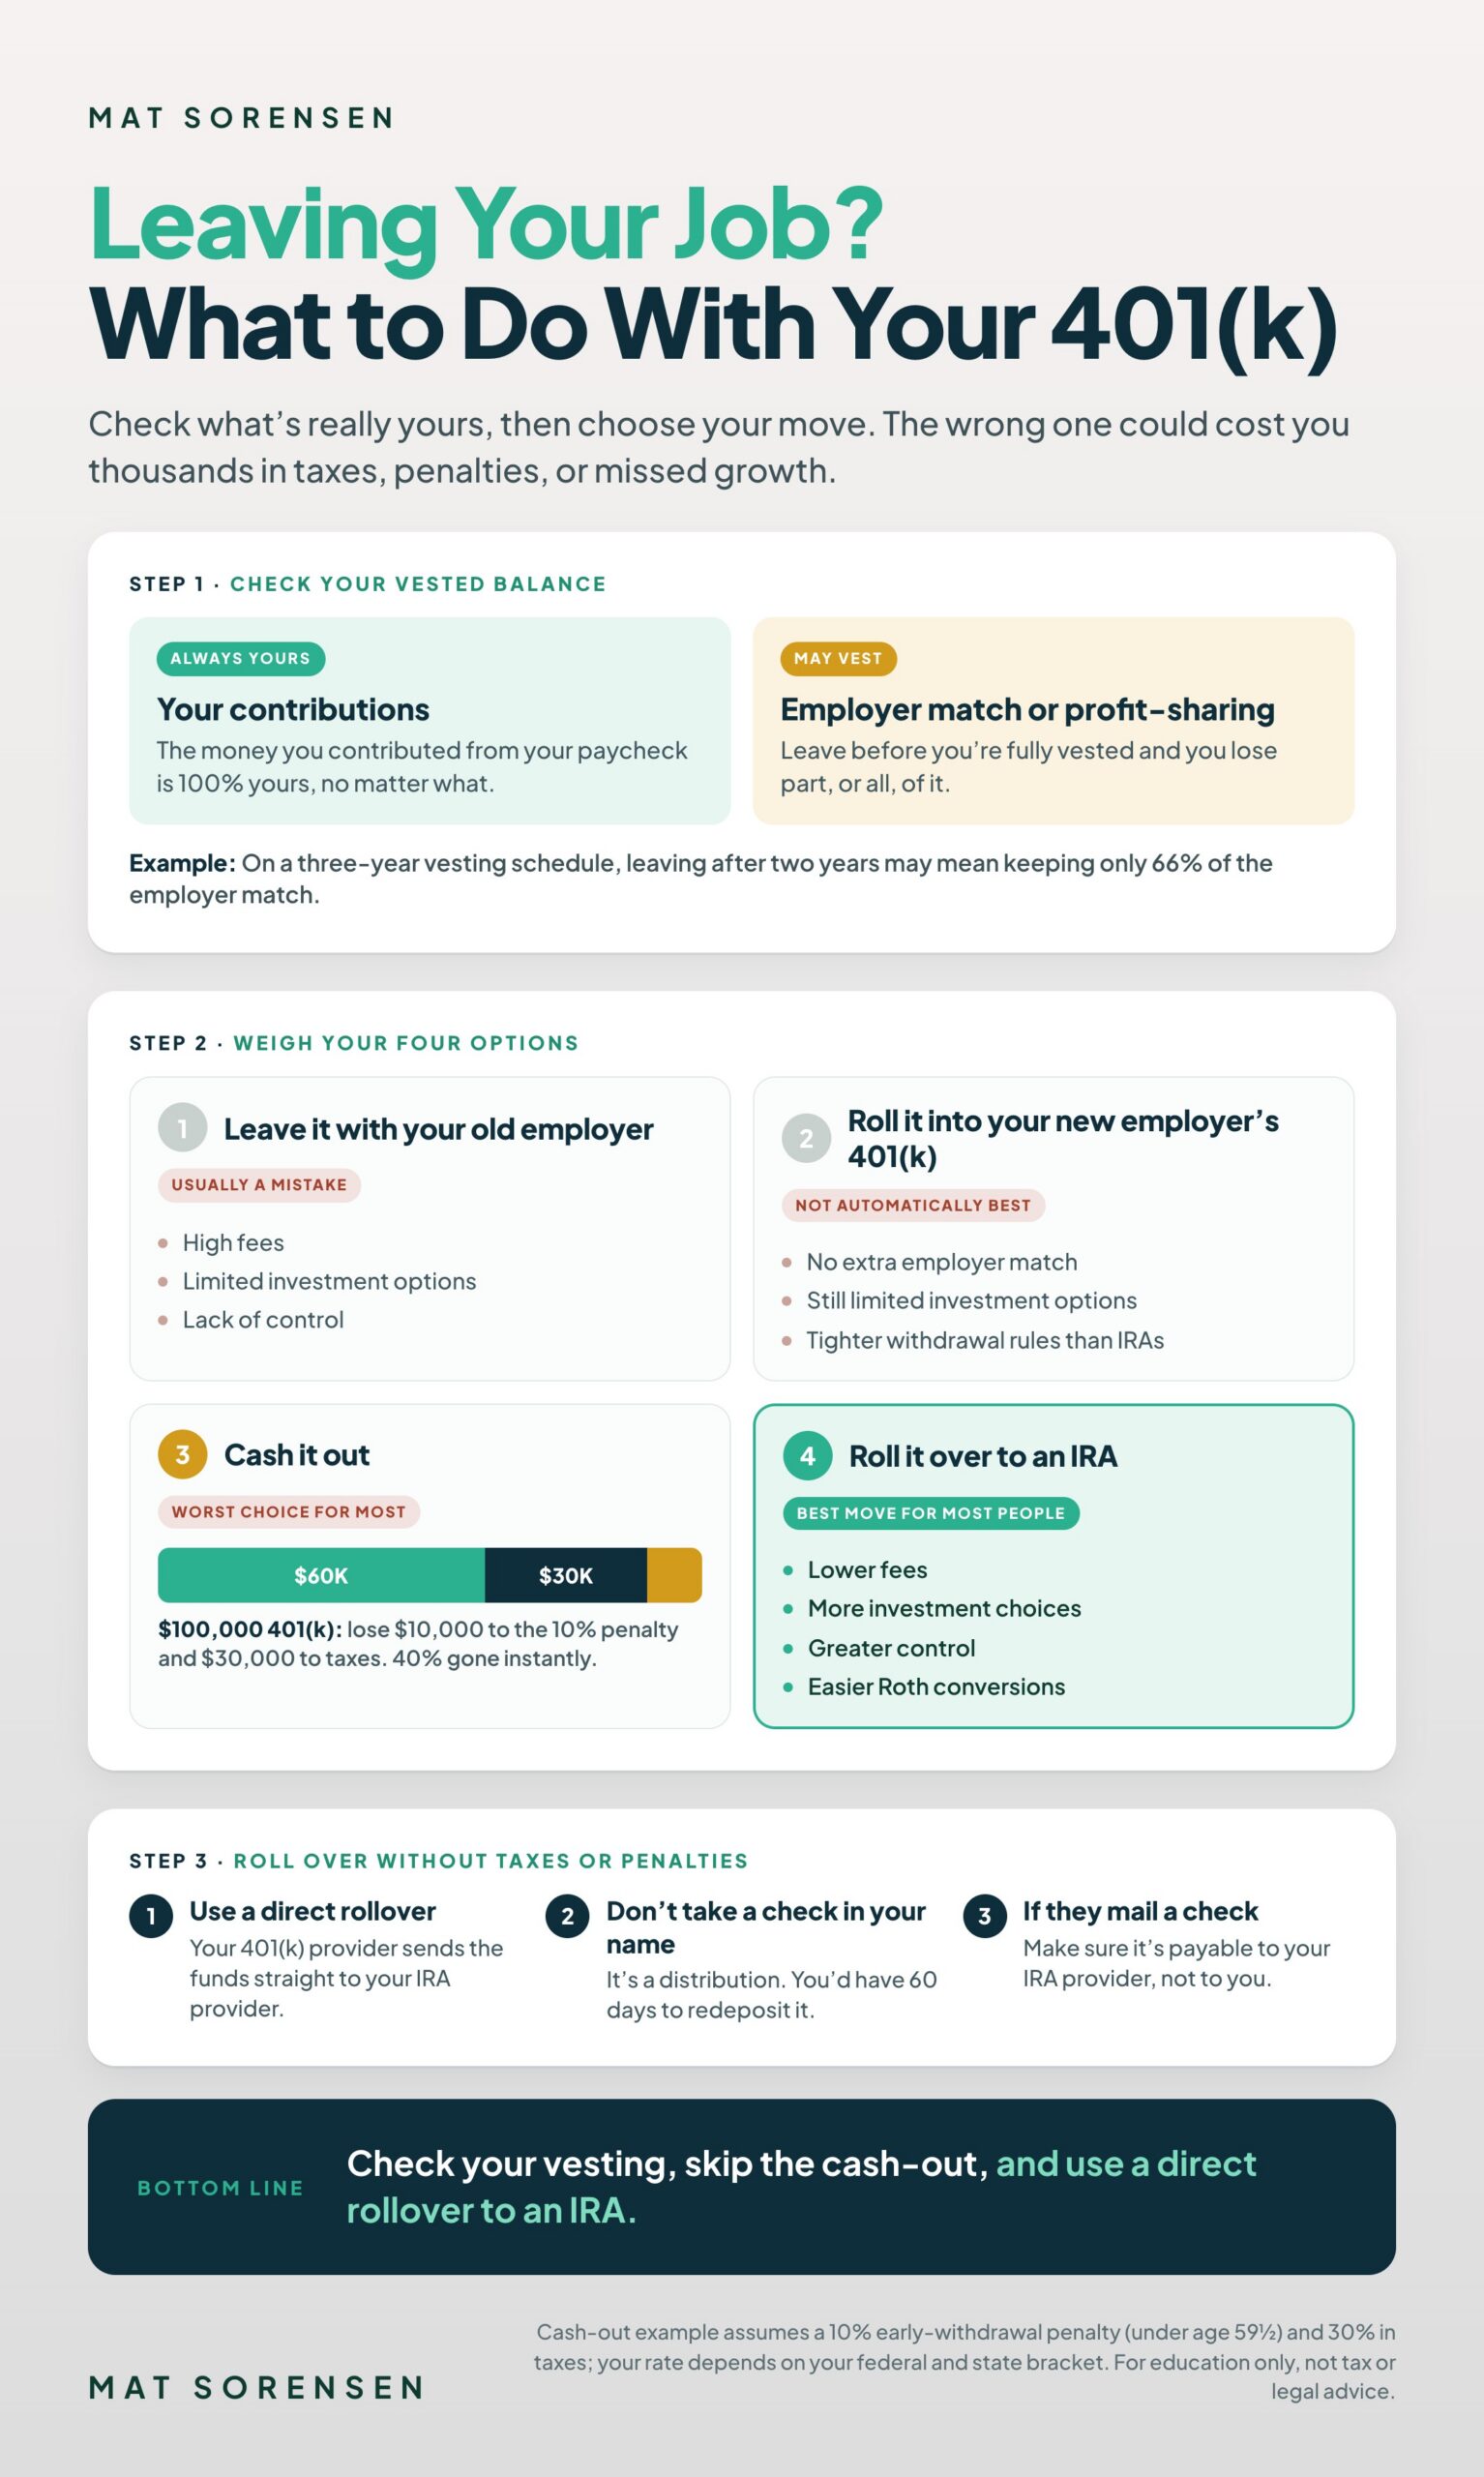
Infographic: what to do with your 401(k) when you leave your job. Check your vested balance, compare four options, and use a direct rollover to an IRA

Step 1: Check Your Vested Balance

Before making a move, the first thing you need to do is determine how much of your 401(k) actually belongs to you.

Understanding Vesting

Your 401(k) balance is split into two parts:

1. Your Contributions

The money you contributed from your paycheck. This is 100% yours, no matter what.

2. Employer Contributions (Match or Profit-Sharing)

This money may be subject to a vesting schedule. If you leave before you’re fully vested, you lose part (or all) of the employer contributions.

How to Check Your Vested Balance:

  • 1Get your latest 401(k) statement – It will show vested vs. unvested balance.
  • 2Review your company’s vesting schedule – This is outlined in your Summary Plan Description (SPD).

Know what you’re walking away with – Unvested employer contributions do NOT transfer when you leave.

Example: If your employer has a three-year vesting schedule and you leave after two years, you may only keep 66% of the employer match. If you leave too soon, you could be walking away from thousands of dollars in unvested money.

Once you know your true balance, you’re ready to decide where to move your funds.

Step 2: Weigh Your 401(k) Rollover Options

When you leave your employer, you have four main choices for handling your 401(k). Let’s go through each one.

Option 1: Leave Your 401(k) with Your Old Employer

Some people leave their 401(k) behind at their old job because it seems like the easiest choice. But in most cases, this is a mistake.

Cons of Keeping Your 401(k) at Your Old Job:

  • ✕High fees – The average small business 401(k) charges 1.5% in fees, which could cost you thousands over time.
  • ✕Limited investment options – Most plans restrict you to mutual funds and target-date funds—often with subpar performance.
  • ✕Lack of control – You can’t make quick investment decisions, and accessing funds requires employer approval.

Bottom Line: If you no longer work there, why should your money stay there?

Option 2: Roll It Into Your New Employer’s 401(k)

If your new job offers a 401(k) plan, you may have the option to roll over your old 401(k) into the new one.

Cons of Moving to a New 401(k):

  • ✕No financial benefit – Rolling over doesn’t give you extra employer matching.
  • ✕Still limited investment options – You’re typically stuck with mutual funds or target-date funds.
  • ✕More restrictive withdrawal rules – 401(k) plans often have tighter restrictions than IRAs.

Key Insight: Just because your new job has a 401(k) does NOT mean you should roll your old one into it.

Option 3: Cash Out Your 401(k)

You can withdraw your 401(k) as a lump sum when you leave—but this is one of the worst financial mistakes you can make.

Why Cashing Out Is a Disaster:

  • ✕10% Early Withdrawal Penalty – If you’re under 59½, you automatically lose 10% to the IRS.
  • ✕Massive Taxes – Your withdrawal is treated as ordinary income, which could push you into a higher tax bracket. For traditional 401(k)s the entire distribution is taxable. For Roth 401(k) balances, only the earnings are taxable if distributed early.

Example: If you cash out a $100,000 401(k):

$60,000
$30,000
10% Penalty -$10,000
30% in Taxes -$30,000 (depends on your state/federal tax bracket)
Final Amount Received $60,000

That’s 40% gone instantly.

When Cashing Out Might Make Sense:

  • ✓You’re 59½ or older and ready for retirement.
  • ✓You have no other financial options in an emergency.

For most people, this is the worst choice.

Option 4: Roll Over to an IRA

Rolling your 401(k) into an IRA gives you more control, lower fees, and better investment choices.

Why an IRA Is the Best Move for Most People:

  • ✓Lower fees – No employer plan fees eating into your returns.
  • ✓More investment choices – Could be a brokerage IRA for stocks/ETFs (like Schwab or Fidelity), or a Self-Directed IRA for real estate, private companies, and funds (like at Directed IRA).
  • ✓Greater control – No employer restrictions.
  • ✓Easier Roth conversions – Convert to a Roth IRA for future tax-free growth.

How to Rollover to an IRA Without Taxes or Penalties:

  • 1Use a direct rollover – This is critical to avoiding taxes. Your 401(k) provider should send the funds directly to your new IRA provider.
  • 2Do NOT take a check in your name – If the check is made out to you, it’s a distribution. You have 60 days to redeposit it into an IRA—or the IRS treats it as taxable income.
  • 3Some providers still mail checks – If they do, make sure it’s made out to your IRA provider, not to you personally.

Example: A 401(k) account owner requested a rollover, but the provider sent the check to the account owner. He didn’t redeposit it into an IRA and is now subject to taxes and penalties—and those funds can’t go back into a tax-advantaged account like an IRA.

Best Practice: Always request a direct rollover to the IRA provider to avoid a distribution, penalties, and taxes.

Key Takeaways

  • ✓Check your vested balance first. Make sure you know how much of your 401(k) you actually own.
  • ✓Leaving your 401(k) at your old employer is usually a bad idea – High fees and limited investment options make it less appealing.
  • ✓Rolling your 401(k) into your new employer’s plan may not be the best move – You’ll still be stuck with high fees and limited investment options.
  • ✓Cashing out your 401(k) is a terrible idea for most people under 59½ – Taxes and penalties could take 40% or more of your money.
  • ✓Rolling over to an IRA is the best option for most people – It gives you lower fees, more investment options, and complete control over your retirement funds.
  • ✓Use a direct rollover to avoid taxes and penalties – Never take a check in your name unless it’s your only option, and if you do, you must redeposit the same amount into an IRA within 60 days.

Are you interested in self-directing your IRA?

Visit DirectedIRA.com and book a call with our team today!

Huge Changes to IRAs and 401(k)s in New Budget Law that Affects Everyone

The Omnibus budget bill signed into law today, December 27, 2022, has significant changes that will affect everyone saving for retirement. From more Roth options, improvements on required minimum distributions, and increases to contribution amounts, IRA and 401(k)s will become even better vehicles to build long-term savings and wealth for retirement. Rules for prohibited transactions remain substantially the same. Prior language which would have fixed the death penalty on prohibited transactions for IRAs did not end up in the final version of the bill. There are some positive developments on fixing IRA mistakes in the final law through the DOL’s EPCRS.

UPDATE (NOV 2026)

The retirement changes in this bill are known as the SECURE 2.0 Act, which was signed into law on December 29, 2022. For 2026, the age 50+ catch-up contribution for 401(k)s is $8,000, and the ages 60–63 catch-up is $11,250 (401(k)) or $5,250 (SIMPLE). (Source: Wikipedia / NAPA; IRS)

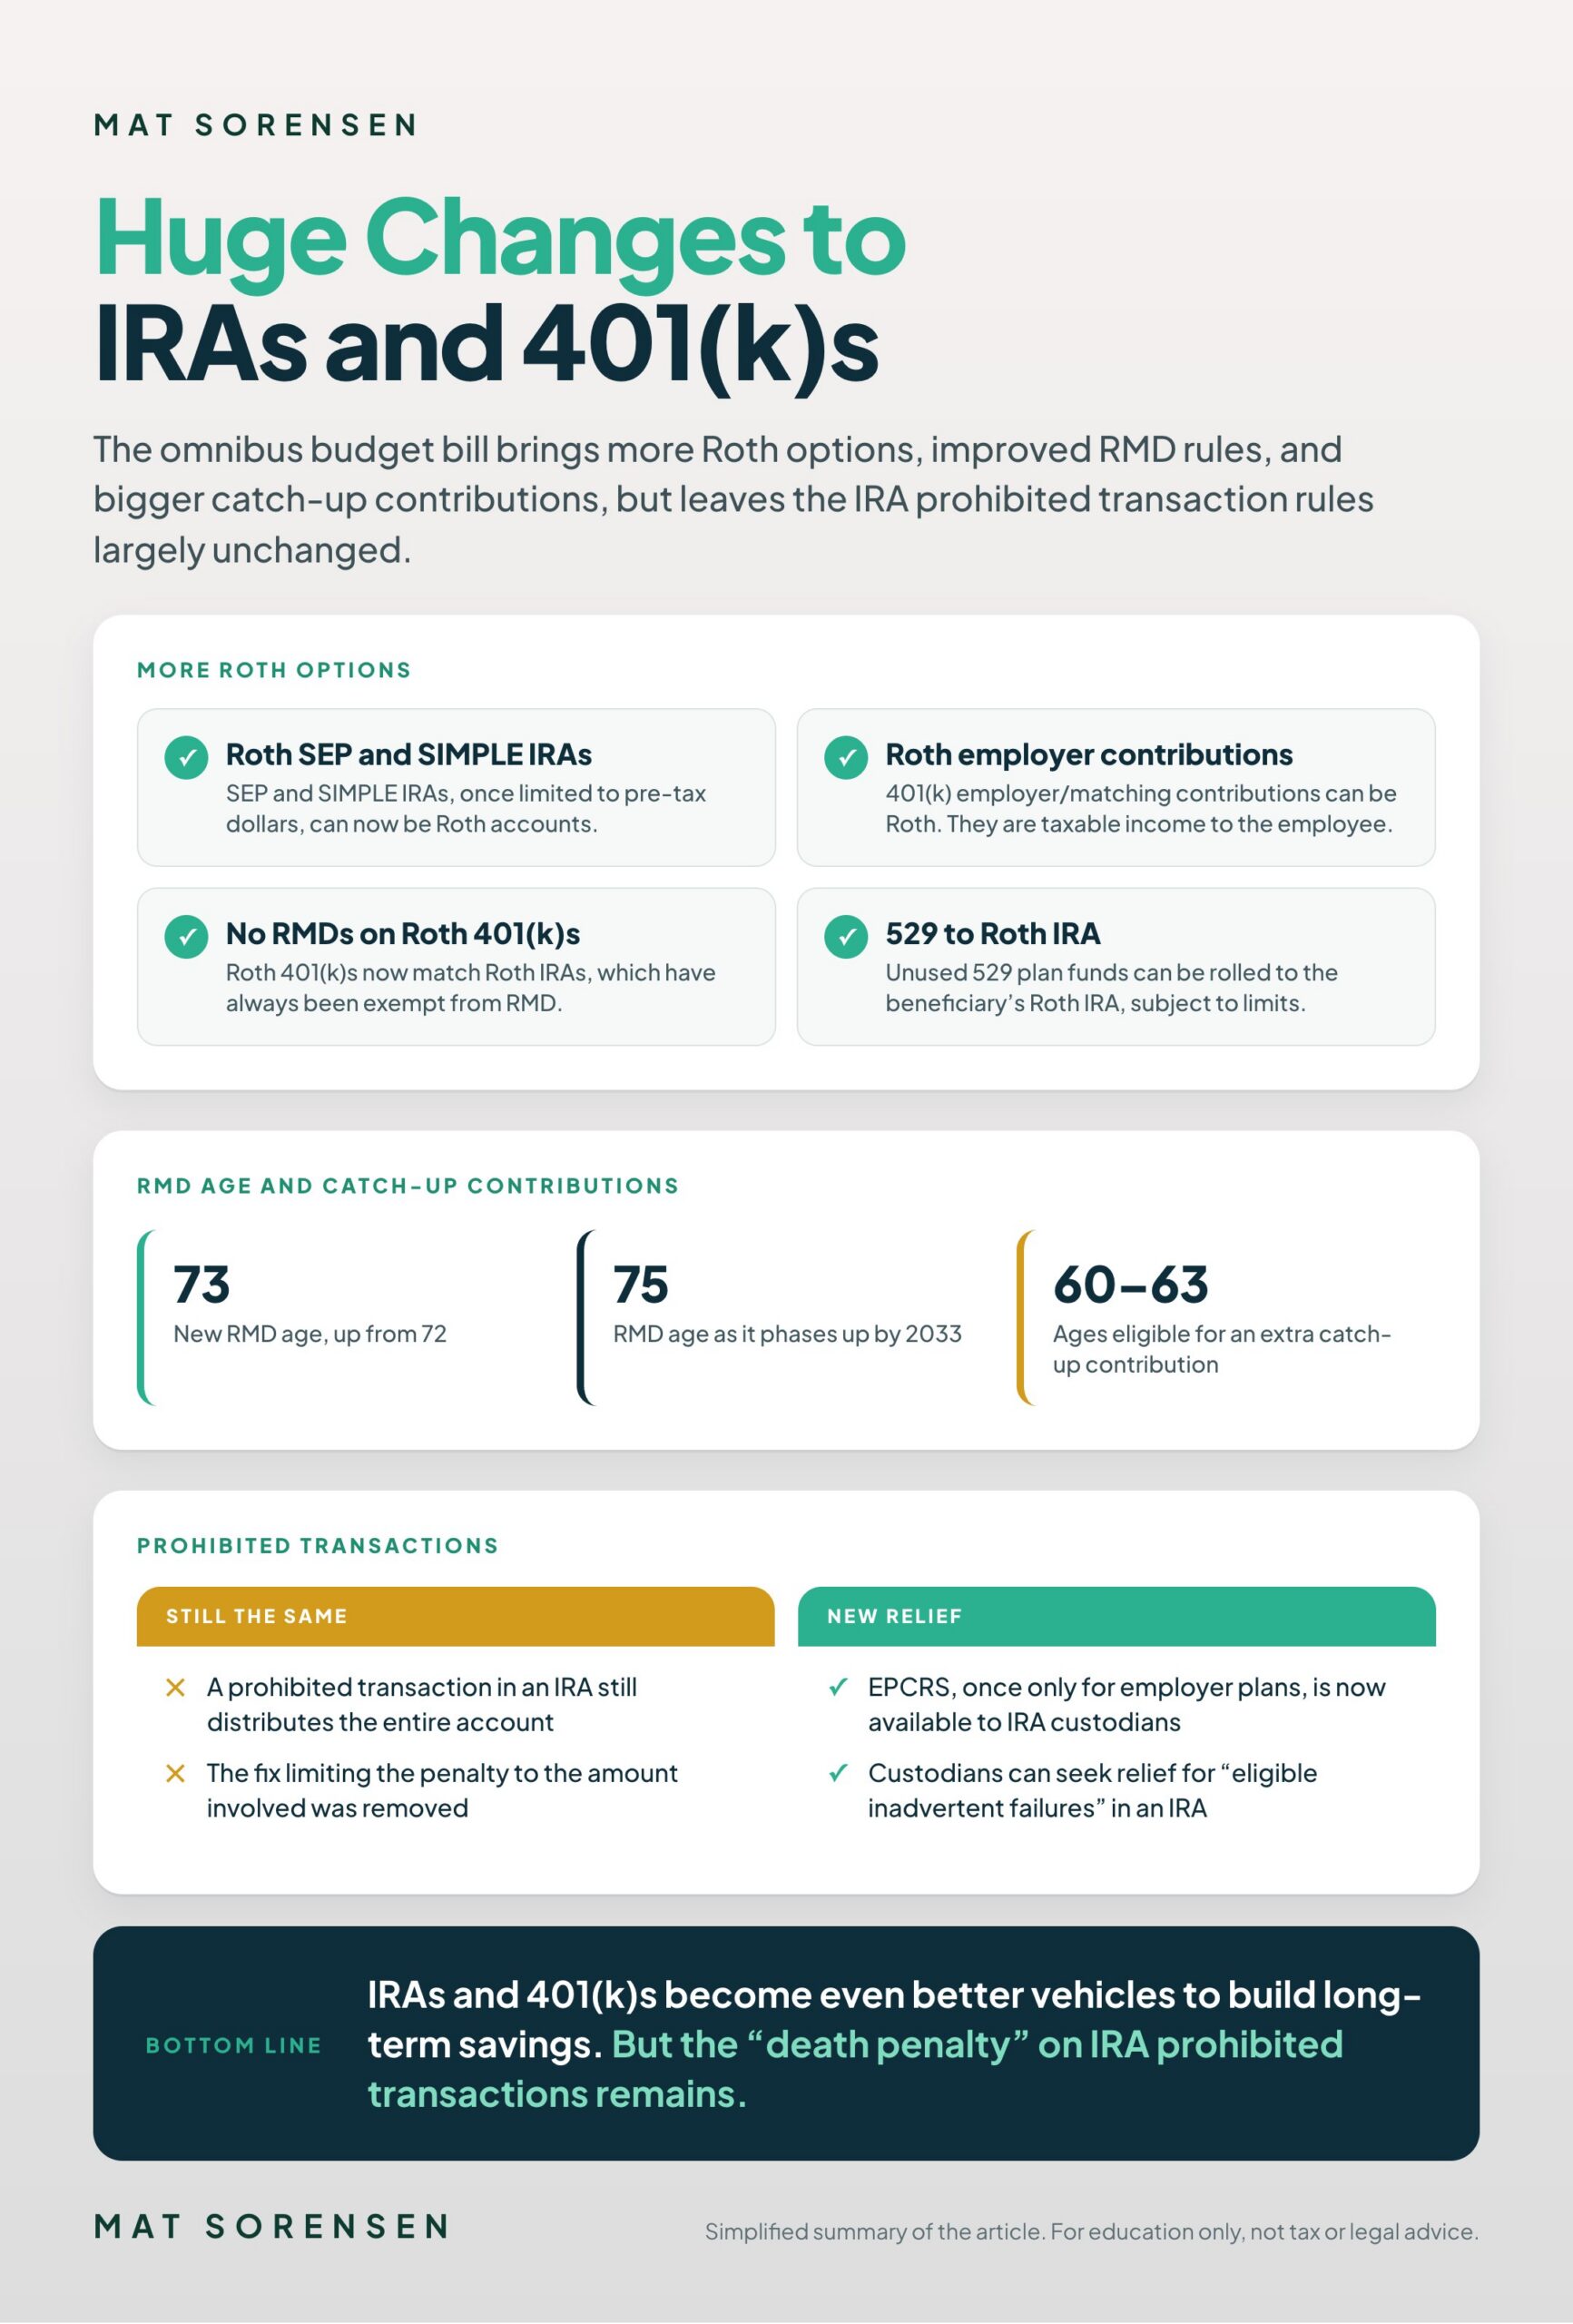
Infographic: new Roth options, RMD age and catch-up changes, and what stayed the same for IRA prohibited transactions under the budget law

More Roth

One major theme in the bill is “rothification”. Congress loves Roth accounts because they don’t give up tax revenue today as there is no tax deduction for contributing to a Roth IRA or Roth 401k. Traditional accounts, on the other hand, result in a tax deduction today (although taxed on the way out) and that reduces taxes paid and the amount of money congress gets to spend. Here are the new Roth account rules that benefit investors.

Simple and SEP Roth IRAs

Under prior laws, SIMPLE and SEP IRAs could only receive traditional (pre-tax) dollars. Under the new law and beginning in tax year 2023, a SIMPLE IRA or SEP IRA can be a Roth account. In other words, you can have a Roth SEP IRA or ROTH SIMPLE IRA. Contributions to these accounts are not deductible but grow and come out tax free like Roth IRAs and Roth 401(k)s. This change is significant as the inability to do Roth dollars in SEP and SIMPLEs was a major disincentive to these account types and why we didn’t see many investors want them or use them at our company, Directed IRA.

401(k) Employer/matching contributions can be Roth

Under prior laws, employer/matching contributions in a 401(k), including solo 401(k)s, must be traditional dollars. Under the new law, effective now, employer/matching contributions can be Roth (or they can be traditional if you want as well). The Roth employer/matching contributions are not deductible, and the amounts contributed by the employer for the employee are taxable income to the employee (likely to be included on W-2, waiting for guidance) but grow and come out tax-free similar to all other Roth accounts. This will likely require a plan amendment before employer Roth contributions are allowed but there may be transitional relief and we’re waiting on guidance from the IRS/DOL.

UPDATE (NOV 2026)

The IRS has since issued guidance (Notice 2024-2). A 401(k) plan can let employees choose Roth treatment for employer matching and profit-sharing contributions if they are fully vested, and those contributions are taxable in the year they’re made. (Source: IRS Notice 2024-2)

No RMD on Roth 401(k)s

Under prior laws, required minimum distributions (RMD) applied to Roth 401(k) accounts. Under the new law, and beginning in tax year 2024, Roth 401(k) accounts (including solo Roth 401ks) will not be subject to RMD rules. This will harmonize the rules between Roth IRAs and Roth 401(k)s as Roth IRA have always been exempt from RMD.

Unused 529 Plan Funds Can Be Rolled to a Roth IRA

Under the law, unused 529 plan funds can be rolled to a Roth IRA of the 529 account beneficiary up to a maximum aggregate of $35k. The 529 plan must have been maintained for 15 years. Also, the amount distributed cannot exceed the aggregate amount contributed.

RMD Age Improvement and More Catch-Up Contributions

RMD goes from 72 to 73 in 2023 and then 75 in 2033

The age of required minimum distributions (RMD) will increase from 72 to 73. The age will then adjust over time up to age 75 by 2033. This will apply to traditional (pre-tax) IRA and traditional 401(k) and other pre-tax retirement accounts. RMD does not apply to Roth IRAs and under the new bill will not apply to Roth 401(k) funds either.

Increased Catch-Up Contribution for those 60-63

Current catch-up contributions are allowed for those 50 or older and are in the amount of $6,500. Under the new law, and effective in 2025, an additional catch-up contribution is allowed between ages 60-63 as the $6,500 is increased in those four years to $10,000. Starting in 2026, catch-up contributions (including this one) must be Roth if the taxpayer’s FICA wages from the employer sponsoring the plan were more than $145k in the prior year (indexed for inflation: $150k of 2025 wages for 2026).

Prohibited Transaction Rules Remain the Same

One significant part of the bill for self-directed investors was regarding the “death penalty” on prohibited transactions. Under the current law, if a prohibited transaction occurs in an IRA, then the entire account is distributed. A prior version of the bill included a fix to this and would have changed a penalty to be only on the amount involved in the prohibited transaction, similar to prohibited transactions on 401(k)s, but this fix was unfortunately removed in the final negotiations. There are changes in the bill to prohibited transactions, but they merely codify existing case law and guidance from the IRS/DOL and do not fix the death penalty on prohibited transactions that occurs if someone makes a prohibited transaction mistake with their IRA.

One positive development is the ability to use the EPCRS for IRA mistakes. EPCRS is the employee plans compliance resolution system and was only allowed for employer-based plans. Under the new law, EPCRS will be available to IRA custodians who can seek relief for IRA account owners for “eligible inadvertent failures” in an IRA.

FREE SELF-DIRECTED IRA GUIDE

Learn how a self-directed Roth IRA can invest in real estate, private companies, notes, and more, and keep the growth tax-free.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

Self-Directed IRA Versus Solo 401(k)

Many self-directed investors have the option of choosing between a self-directed IRA or a self-directed solo 401k. Both accounts can be self-directed so that you can invest in any investment allowed by law such as real estate, LLCs, precious metals, or private company stock. However, depending on your situation, you may choose one account type over the other. What are the differences? When should you choose one over the other?

We’ve been advising clients for over a decade on self-directed IRAs and solo 401(k)s and what we’ve learned is that there is no universal answer to the question. Instead, you need to learn what is best based on your personal situation and investment objectives. Do you even qualify for a solo(k)? What investments do you plan to make and does one account type make a difference for your investments? The good news is that either way you go, we can help with a self-directed IRA at Directed IRA, where we are a licensed trust company and can serve as custodian of your IRA. Or, we can set-up a solo(k) at KKOS Lawyers using our pre-approved plan documents.

Infographic: how a self-directed IRA and a solo 401(k) compare on eligibility, contributions, Roth options, set-up, control, and leveraged real estate

Comparing the Two Accounts

IRA Solo 401K
Qualification Must be an individual with earned income or funds in a retirement account to roll over. Must be self-employed with no other employees besides the business owner and family/partners.
Contribution Max $6,000 max annual contribution. Additional $1,000 if over 50. $61,000 max annual contribution (it takes $140K of wage/se income to max out). Contributions are employee and employer.
Traditional & Roth You can have a Roth IRA and/or a Traditional IRA. The amount you contribute to each is added together in determining total contributions. A solo 401(k) can have a traditional account and a Roth account within the same plan. You can convert traditional sums over to Roth as well.
Cost and Set-Up You will work with a self-directed IRA custodian who will receive the IRA contributions in an SDIRA account. You must use an IRS pre-approved document when establishing a solo 401k. This adds additional cost over an IRA.
Custodian Requirement An IRA must have a third-party custodian involved in the account (e.g. bank, credit union, trust company) who is the trustee of the IRA. Of course we recommend our company, www.directedira.com. A 401(k) can be self-trustee’d, meaning the business owner can be the trustee of the 401(k). This provides for greater control but also greater responsibility.
Investment Details A self-directed IRA is invested through the self-directed IRA custodian. A self-directed IRA can be subject to a tax called UDFI/UBIT on income from debt leveraged real estate. A Solo 401(k) is invested by the trustee of the 401(k) which could be the business owner. A solo 401(k) is exempt from UDFI/UBIT on income from debt leveraged real estate.

UPDATE (NOV 2026)

This table uses 2022 limits. For 2026, the IRA limit is $7,500, plus $1,100 if you’re 50 or older, and the Solo 401(k) total limit is $72,000, plus catch-up contributions ($8,000 at age 50+). (Source: IRS)

Keep in mind that the solo 401(k) is only available to self-employed persons while the self-directed IRA is available to everyone who has earned income or who has funds in an existing retirement account that can be rolled over to an IRA.

Conclusion

Based on the differences outlined above, a solo 401(k) is generally a better option for someone who is self-employed and is still trying to maximize contributions as the solo 401(k) has much higher contribution amounts. On the other hand, a self-directed IRA is a better option for someone who has already saved for retirement and who has enough funds in their retirement accounts that can be rolled over and invested via a self-directed IRA as the self-directed IRA is easier and cheaper to establish.

Another major consideration in deciding between a solo 401(k) and a self-directed IRA is whether there will be debt on real estate investments. If there is debt and if the account owner is self-employed, they are much better off choosing a solo 401(k) over an IRA as solo 401(k)s are exempt from UDFI tax on leveraged real estate.

Choosing between a self-directed IRA and a solo 401(k) is a critical decision when you start self-directing your retirement. Make sure you consider all of the differences before you establish your new account.

FREE SOLO 401(K) GUIDE

Self-employed? Learn how a self-directed Solo 401(k) works and how much you can contribute.

Get the Free Solo 401(k) Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

Mat Sorensen

Mat has been at the forefront of the self-directed IRA industry since 2006. He is the CEO of Directed IRA & Directed Trust Company where they handle all types of self-directed accounts (IRAs, Roth IRAs, HSAs, Coverdell ESA, Solo Ks, and Custodial Accounts) which are typically invested into real estate, private company/private equity, IRA/LLCs, notes, precious metals, and cryptocurrency. Mat is also a partner at KKOS Lawyers and serves clients nationwide from its Phoenix, AZ office.

He is published regularly on retirement, tax, and business topics, and is a VIP Contributor at Entrepreneur.com. Mat is the best-selling author of the most widely used book in the self-directed IRA industry, The Self-Directed IRA Handbook: An Authoritative Guide for Self-Directed Retirement Plan Investors and Their Advisors.

Stuck With a 401K Loan and Leaving Your Job

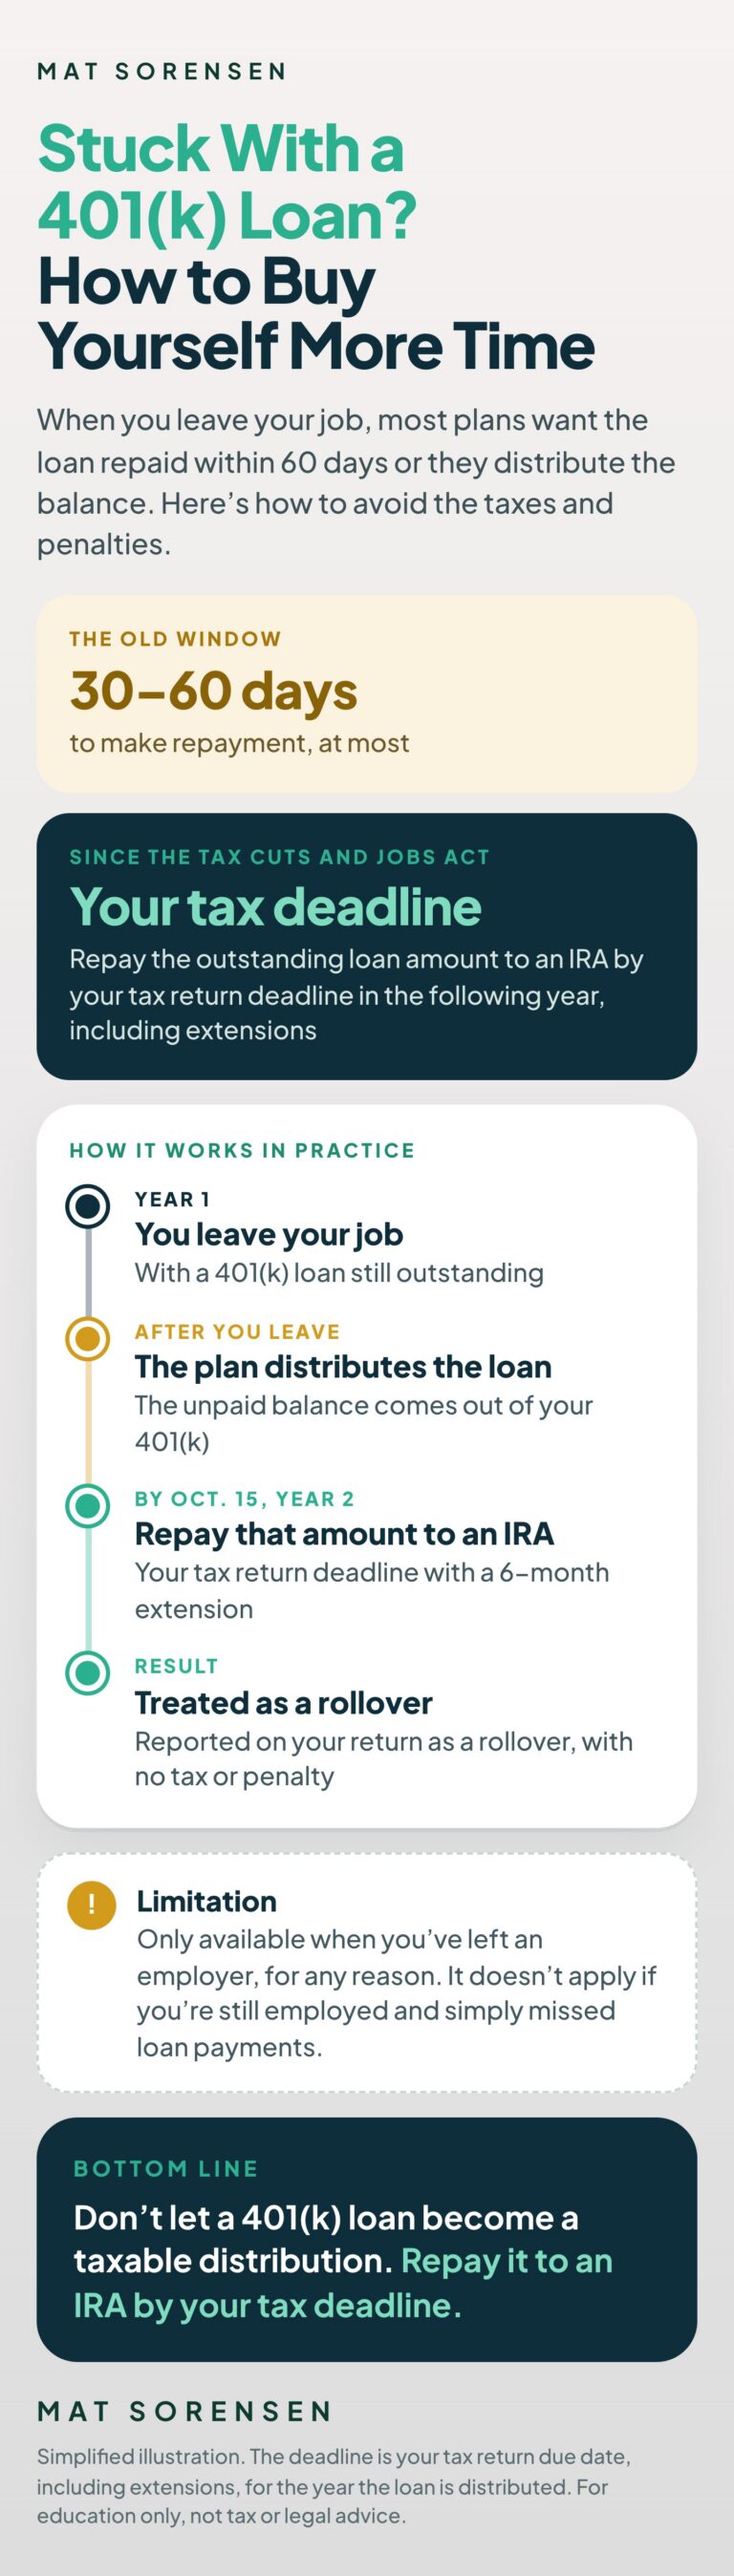
Have you taken a loan from your employer 401(k) plan and plan on leaving? Unfortunately, most company plans will require you to repay the loan within 60 days, or they will distribute the amount outstanding on the loan from your 401(k) account. It’s one of the ways they try to keep their employees from leaving. “Don’t leave or we’ll distribute your 401(k) loan that you took from your money in your 401(k) account.”

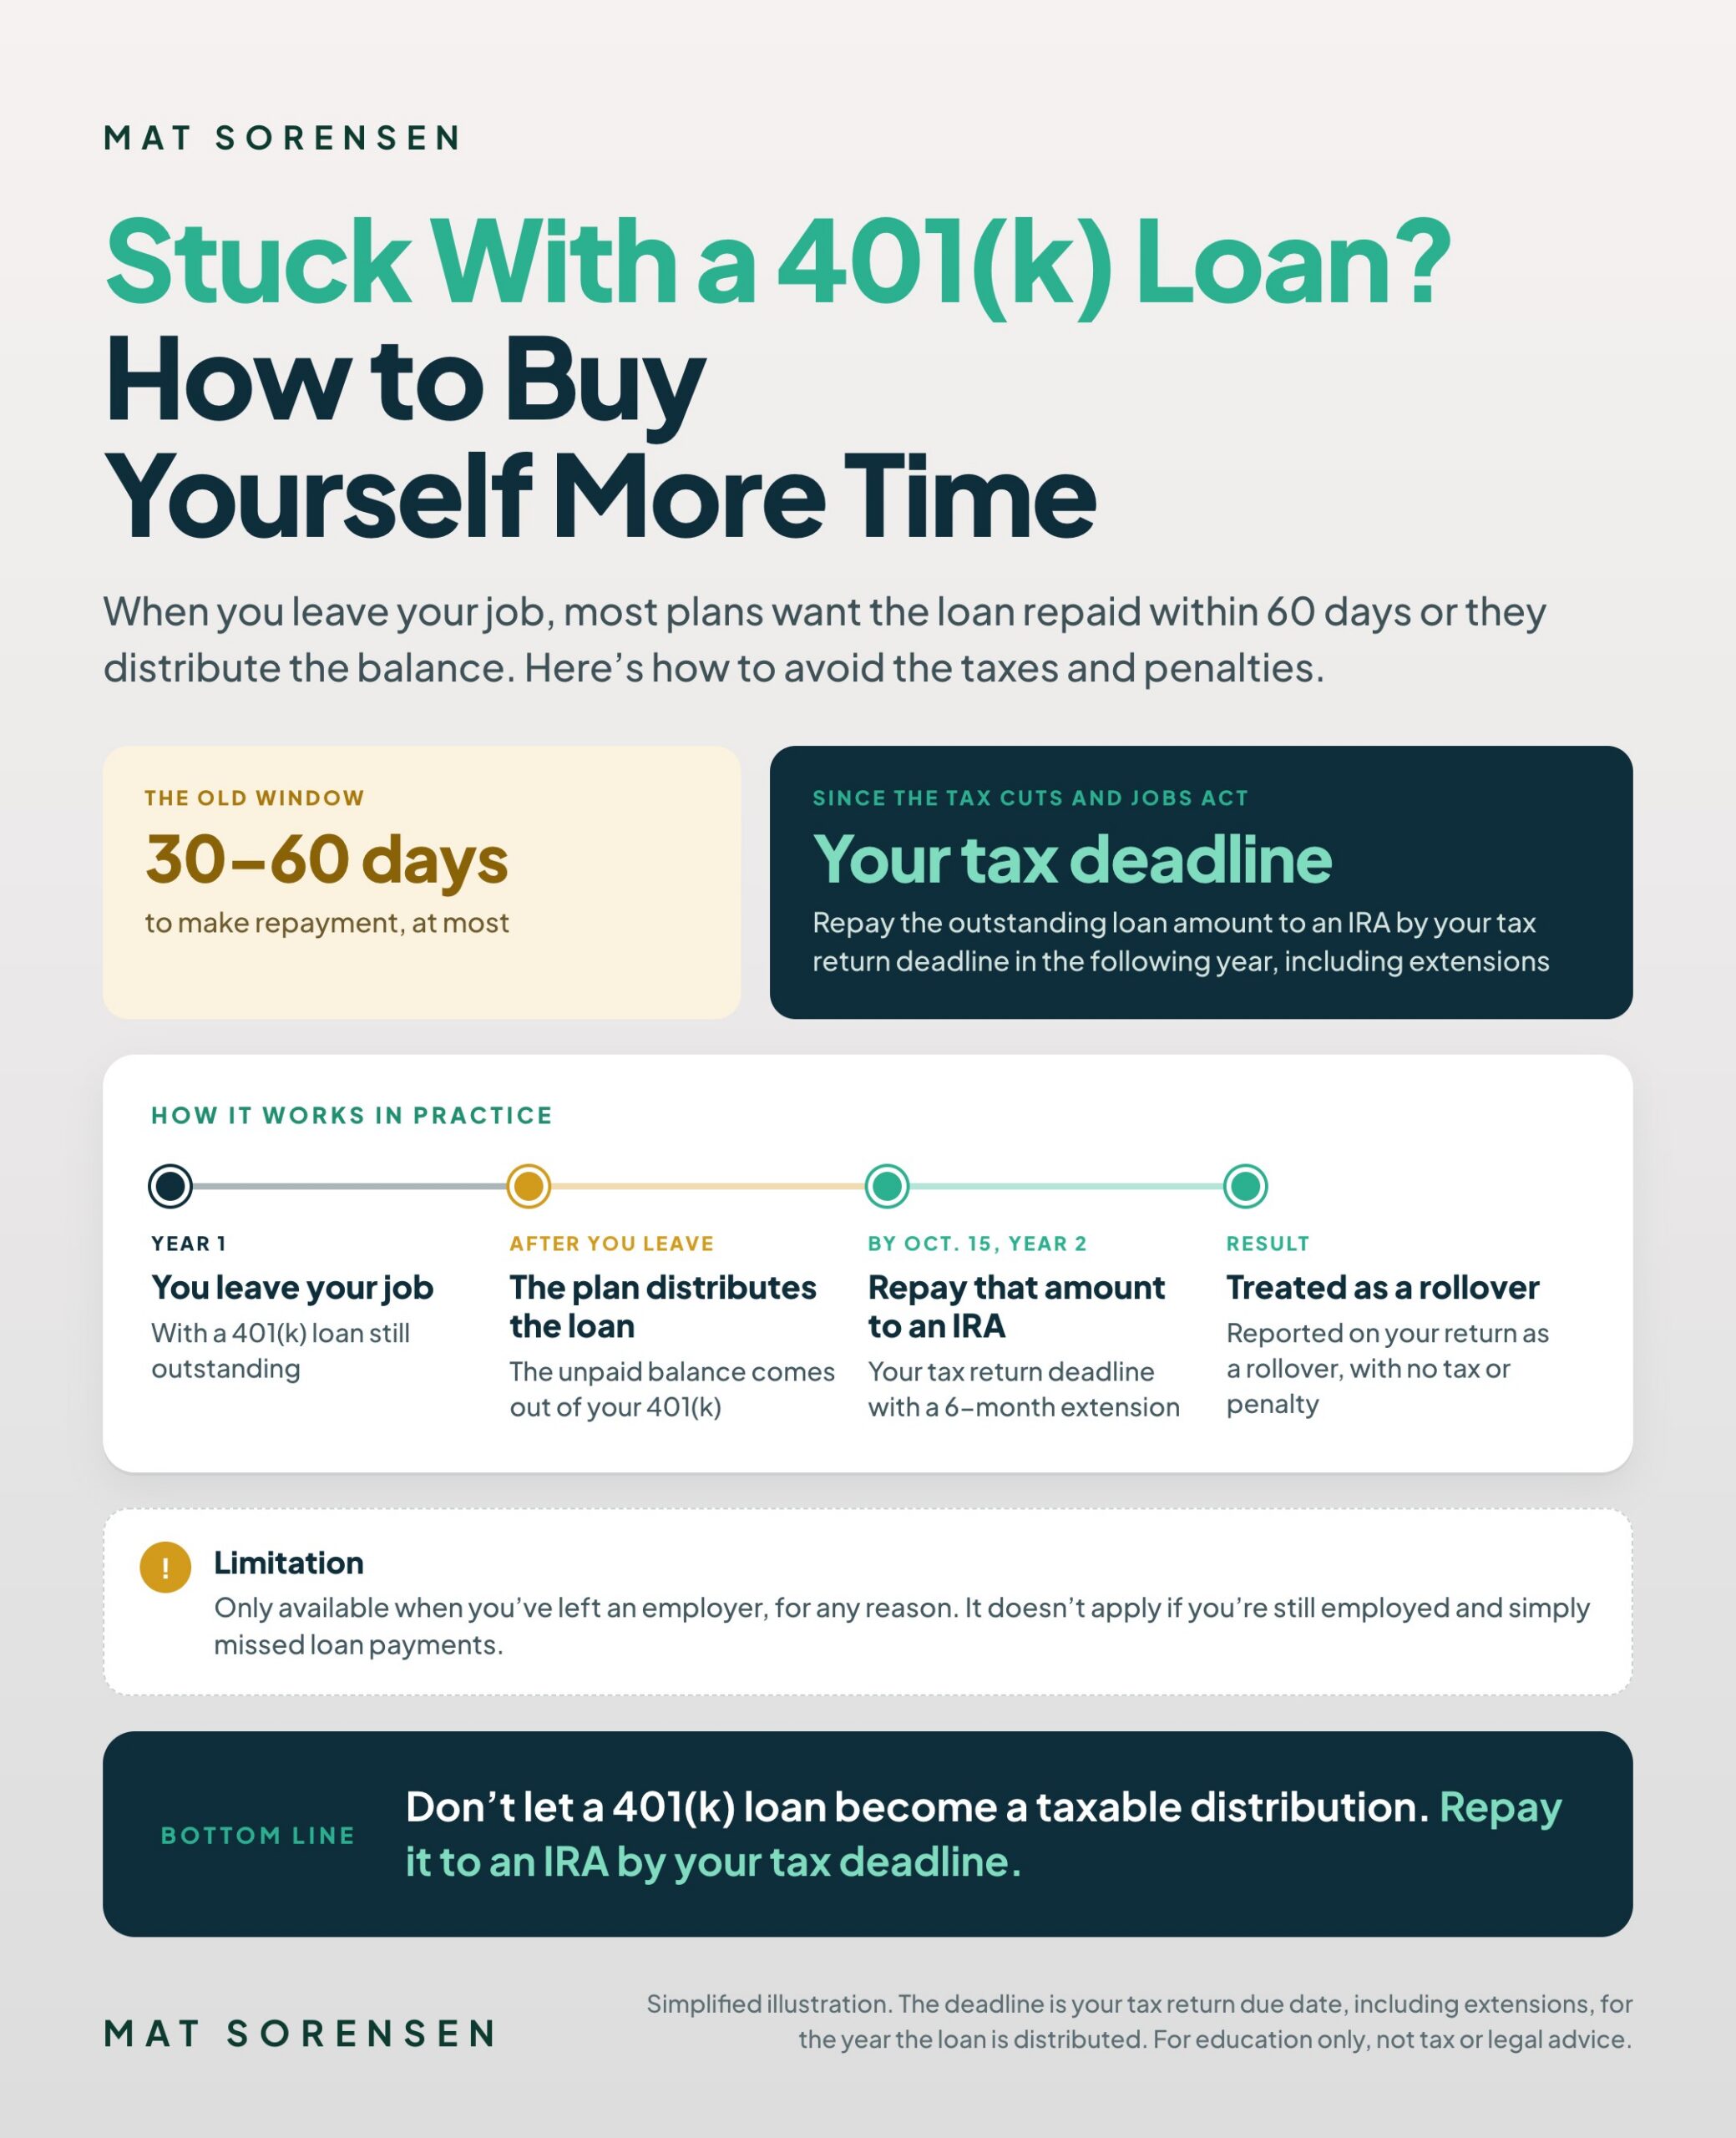
Infographic: leaving your job with a 401(k) loan. Repay the outstanding loan amount to an IRA by your tax return deadline, including extensions, to avoid taxes and penalties

How to Buy Yourself More Time & Avoid the Distribution

The good news is that following the Tax Cuts and Jobs Act (TCJA) you now have the option to re-pay the loan to an IRA to avoid the distribution and you have until your personal tax return deadline of the following year (including extensions) to contribute that re-payment amount to an IRA. By re-paying the amount outstanding on the loan to an IRA, you will avoid taxes and penalties that would otherwise arise from distribution of a participant 401(k) loan.

How It Works In Practice

EXAMPLE

Let’s say you left employment from your employer in February 2026 and that you had a 401(k) loan that was distributed by your employer’s plan following your termination of employment. You will have until October 15th of 2027 (if you extend your personal return, 6 month extension from April 15th) to make re-payment of the amount that was outstanding on the loan to an IRA. These funds are then treated as a rollover to your IRA from the 401(k) plan and your distribution and 1099-R will be reported on your federal tax return as a rollover and will not be subject to tax and penalty. While it’s not perfect it’s far greater time than was previously allowed. Traditionally, you had 30 or 60 days at most to make re-payment.

Limitations

The ability to rollover an outstanding 401(k) loan amount to an IRA is only available when you have left an employer (for any reason). It does not apply in instances where you are still employed and have simply failed to re-pay the loan or to make timely payments.

FREE ROLLOVER GUIDE

Learn how to move an old 401(k) or IRA into a self-directed IRA, tax-free.

Get the Free Transfers & Rollovers Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

Mat Sorensen

Mat has been at the forefront of the self-directed IRA industry since 2006. He is the CEO of Directed IRA & Directed Trust Company where they handle all types of self-directed accounts (IRAs, Roth IRAs, HSAs, Coverdell ESA, Solo Ks, and Custodial Accounts) which are typically invested into real estate, private company/private equity, IRA/LLCs, notes, precious metals, and cryptocurrency. Mat is also a partner at KKOS Lawyers and serves clients nationwide from its Phoenix, AZ office.

He is published regularly on retirement, tax, and business topics, and is a VIP Contributor at Entrepreneur.com. Mat is the best-selling author of the most widely used book in the self-directed IRA industry, The Self-Directed IRA Handbook: An Authoritative Guide for Self-Directed Retirement Plan Investors and Their Advisors.