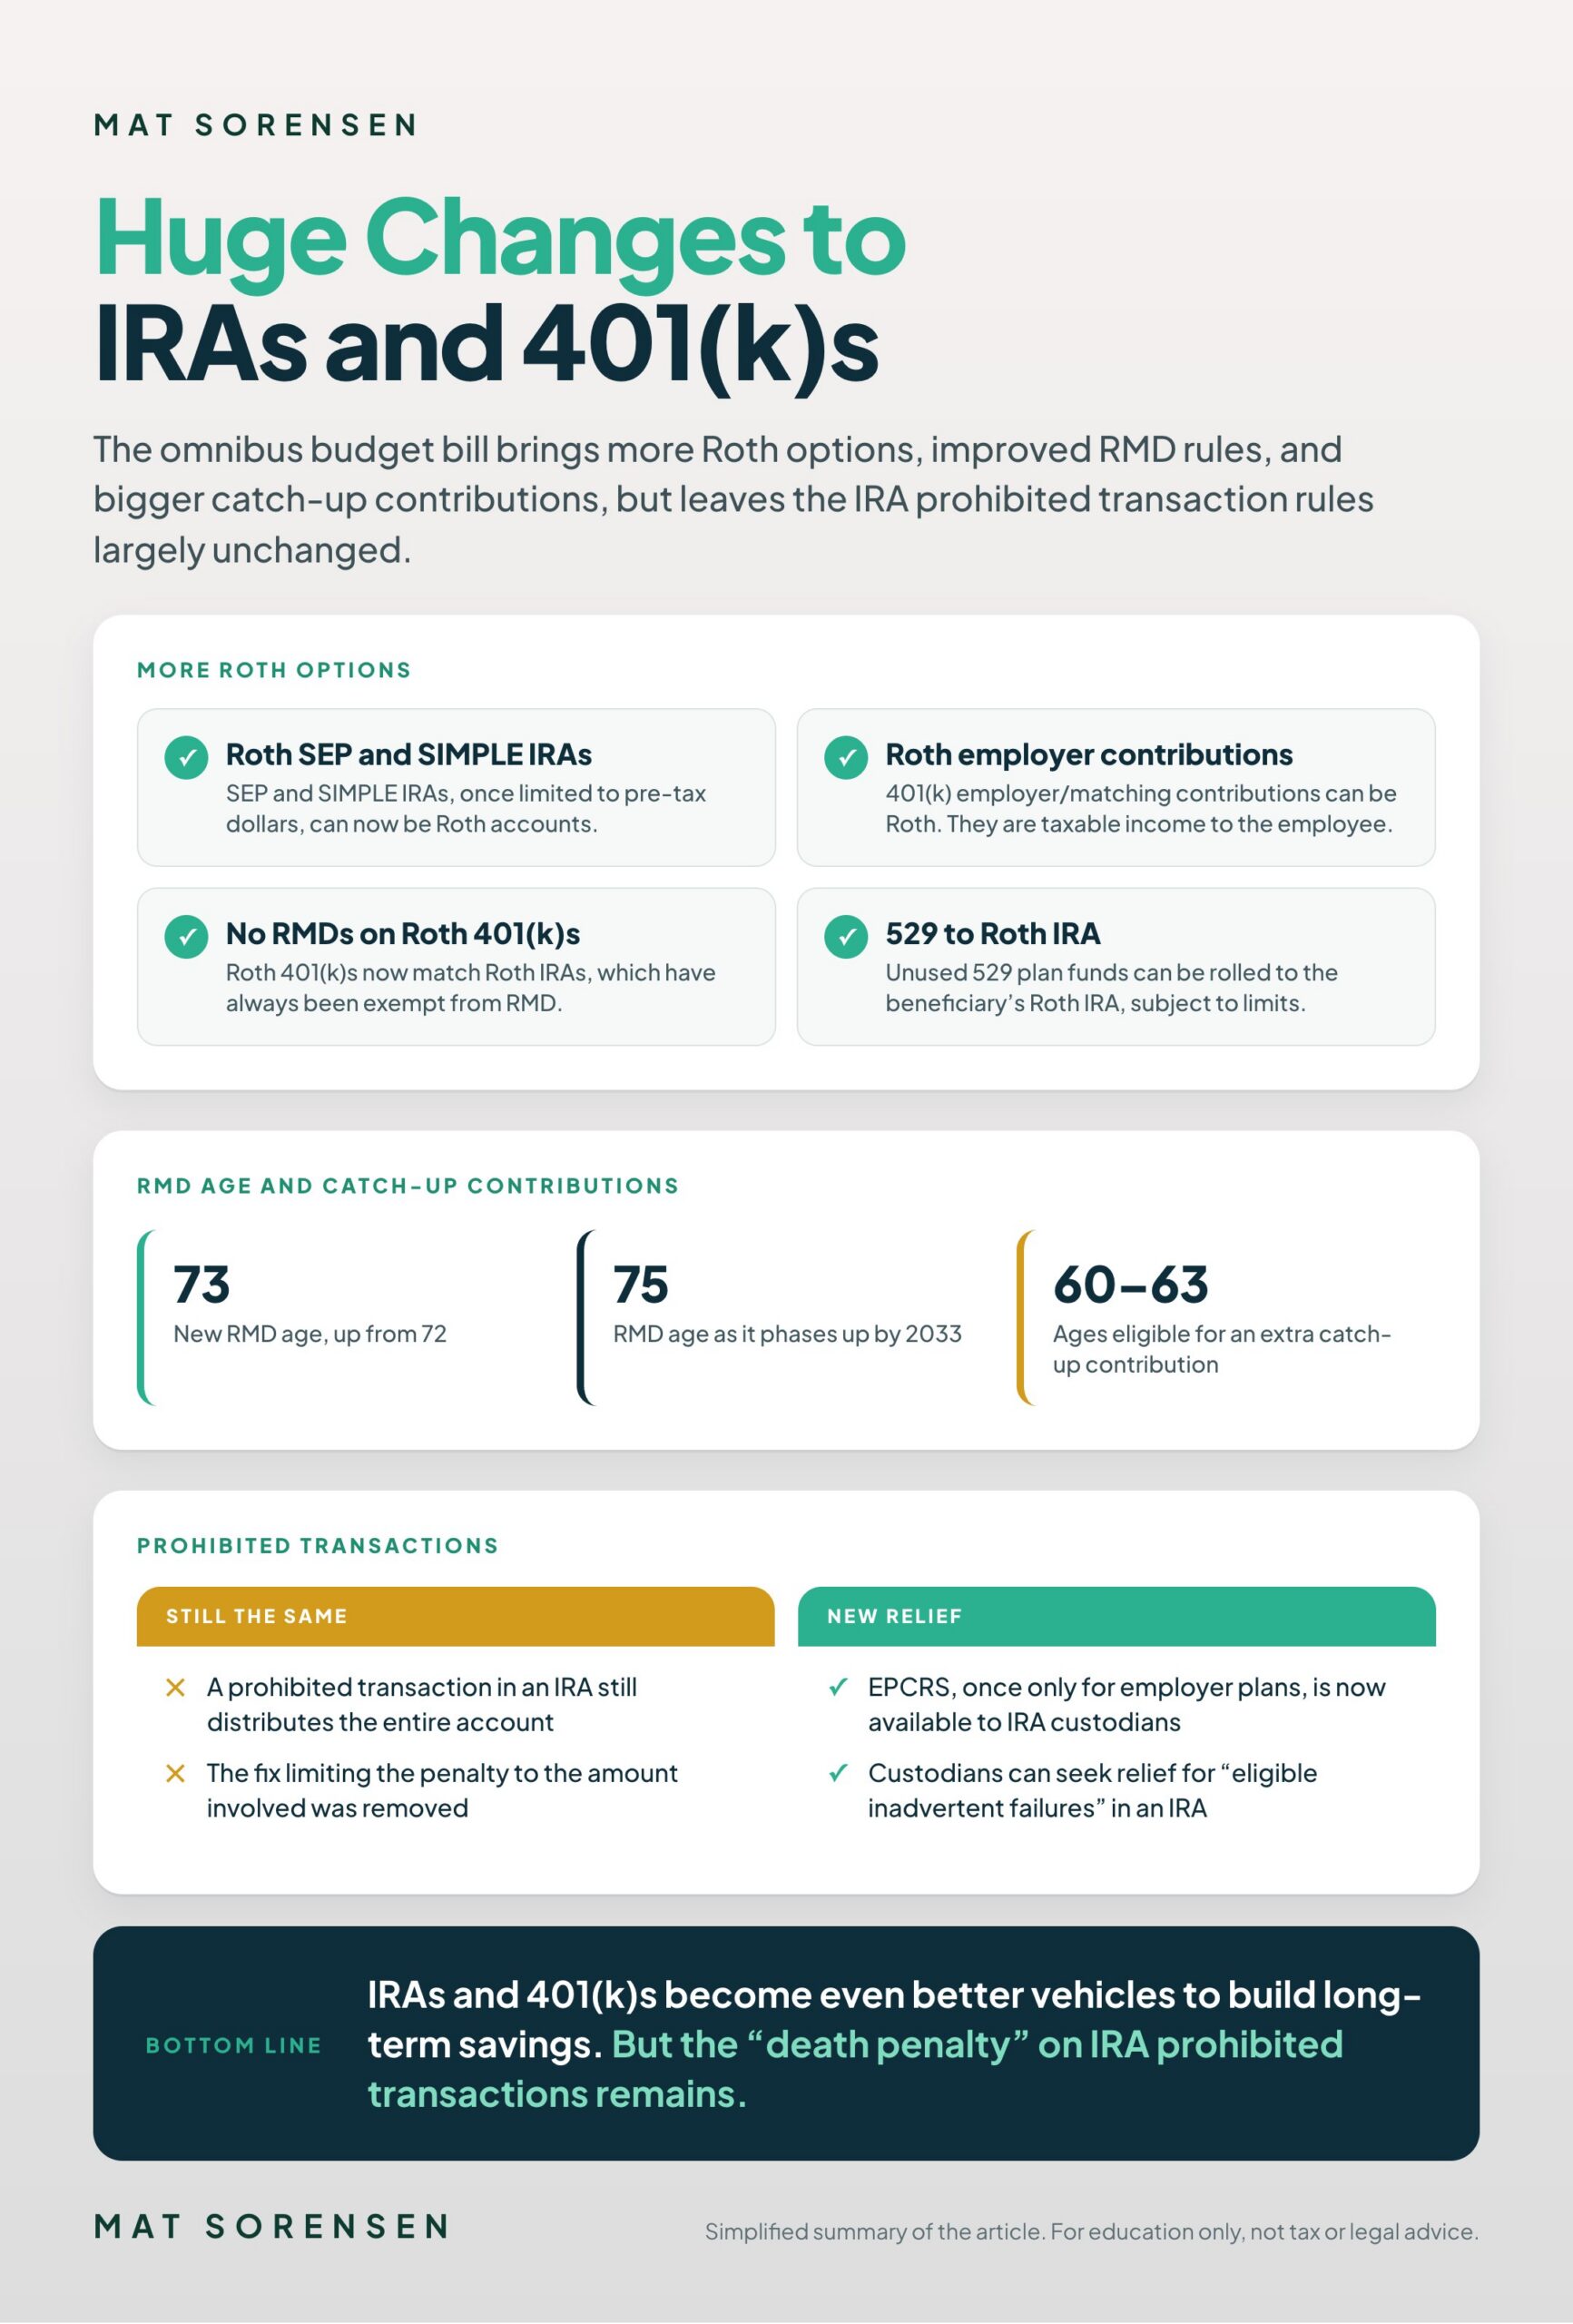
The Omnibus budget bill signed into law today, December 27, 2022, has significant changes that will affect everyone saving for retirement. From more Roth options, improvements on required minimum distributions, and increases to contribution amounts, IRA and 401(k)s will become even better vehicles to build long-term savings and wealth for retirement. Rules for prohibited transactions remain substantially the same. Prior language which would have fixed the death penalty on prohibited transactions for IRAs did not end up in the final version of the bill. There are some positive developments on fixing IRA mistakes in the final law through the DOL’s EPCRS.
UPDATE (NOV 2026)
The retirement changes in this bill are known as the SECURE 2.0 Act, which was signed into law on December 29, 2022. For 2026, the age 50+ catch-up contribution for 401(k)s is $8,000, and the ages 60–63 catch-up is $11,250 (401(k)) or $5,250 (SIMPLE). (Source: Wikipedia / NAPA; IRS)
More Roth
One major theme in the bill is “rothification”. Congress loves Roth accounts because they don’t give up tax revenue today as there is no tax deduction for contributing to a Roth IRA or Roth 401k. Traditional accounts, on the other hand, result in a tax deduction today (although taxed on the way out) and that reduces taxes paid and the amount of money congress gets to spend. Here are the new Roth account rules that benefit investors.
Simple and SEP Roth IRAs
Under prior laws, SIMPLE and SEP IRAs could only receive traditional (pre-tax) dollars. Under the new law and beginning in tax year 2023, a SIMPLE IRA or SEP IRA can be a Roth account. In other words, you can have a Roth SEP IRA or ROTH SIMPLE IRA. Contributions to these accounts are not deductible but grow and come out tax free like Roth IRAs and Roth 401(k)s. This change is significant as the inability to do Roth dollars in SEP and SIMPLEs was a major disincentive to these account types and why we didn’t see many investors want them or use them at our company, Directed IRA.
401(k) Employer/matching contributions can be Roth
Under prior laws, employer/matching contributions in a 401(k), including solo 401(k)s, must be traditional dollars. Under the new law, effective now, employer/matching contributions can be Roth (or they can be traditional if you want as well). The Roth employer/matching contributions are not deductible, and the amounts contributed by the employer for the employee are taxable income to the employee (likely to be included on W-2, waiting for guidance) but grow and come out tax-free similar to all other Roth accounts. This will likely require a plan amendment before employer Roth contributions are allowed but there may be transitional relief and we’re waiting on guidance from the IRS/DOL.
UPDATE (NOV 2026)
The IRS has since issued guidance (Notice 2024-2). A 401(k) plan can let employees choose Roth treatment for employer matching and profit-sharing contributions if they are fully vested, and those contributions are taxable in the year they’re made. (Source: IRS Notice 2024-2)
No RMD on Roth 401(k)s
Under prior laws, required minimum distributions (RMD) applied to Roth 401(k) accounts. Under the new law, and beginning in tax year 2024, Roth 401(k) accounts (including solo Roth 401ks) will not be subject to RMD rules. This will harmonize the rules between Roth IRAs and Roth 401(k)s as Roth IRA have always been exempt from RMD.
Unused 529 Plan Funds Can Be Rolled to a Roth IRA
Under the law, unused 529 plan funds can be rolled to a Roth IRA of the 529 account beneficiary up to a maximum aggregate of $35k. The 529 plan must have been maintained for 15 years. Also, the amount distributed cannot exceed the aggregate amount contributed.
RMD Age Improvement and More Catch-Up Contributions
RMD goes from 72 to 73 in 2023 and then 75 in 2033
The age of required minimum distributions (RMD) will increase from 72 to 73. The age will then adjust over time up to age 75 by 2033. This will apply to traditional (pre-tax) IRA and traditional 401(k) and other pre-tax retirement accounts. RMD does not apply to Roth IRAs and under the new bill will not apply to Roth 401(k) funds either.
Increased Catch-Up Contribution for those 60-63
Current catch-up contributions are allowed for those 50 or older and are in the amount of $6,500. Under the new law, and effective in 2025, an additional catch-up contribution is allowed between ages 60-63 as the $6,500 is increased in those four years to $10,000. Starting in 2026, catch-up contributions (including this one) must be Roth if the taxpayer’s FICA wages from the employer sponsoring the plan were more than $145k in the prior year (indexed for inflation: $150k of 2025 wages for 2026).
Prohibited Transaction Rules Remain the Same
One significant part of the bill for self-directed investors was regarding the “death penalty” on prohibited transactions. Under the current law, if a prohibited transaction occurs in an IRA, then the entire account is distributed. A prior version of the bill included a fix to this and would have changed a penalty to be only on the amount involved in the prohibited transaction, similar to prohibited transactions on 401(k)s, but this fix was unfortunately removed in the final negotiations. There are changes in the bill to prohibited transactions, but they merely codify existing case law and guidance from the IRS/DOL and do not fix the death penalty on prohibited transactions that occurs if someone makes a prohibited transaction mistake with their IRA.
One positive development is the ability to use the EPCRS for IRA mistakes. EPCRS is the employee plans compliance resolution system and was only allowed for employer-based plans. Under the new law, EPCRS will be available to IRA custodians who can seek relief for IRA account owners for “eligible inadvertent failures” in an IRA.
FREE SELF-DIRECTED IRA GUIDE
Learn how a self-directed Roth IRA can invest in real estate, private companies, notes, and more, and keep the growth tax-free.
Get the Free Self-Directed IRA Guide
Prefer to talk it through? Book a call with a Directed IRA specialist