Solo K 5500-EZ Requirement and Failure to File Penalty Relief

Up close photo of an egg-shaped egg timer.Do you have a Solo 401(k)? Have you been filing form 5500-EZ each year for the Solo 401(k)? Are you aware that there is a penalty up to $150,000 per year for failure to file? While some Solo 401(k)s are exempt from the 5500-EZ filing requirement, we have run across many Solo 401(k) owners who should have filed, but have failed to do so.

The return a Solo 401(k) files is called a 5500-EZ, and it is due annually on July 31st for the prior year. If you have a Solo 401(k) and you have no idea what I’m talking about, stay calm, but read on.
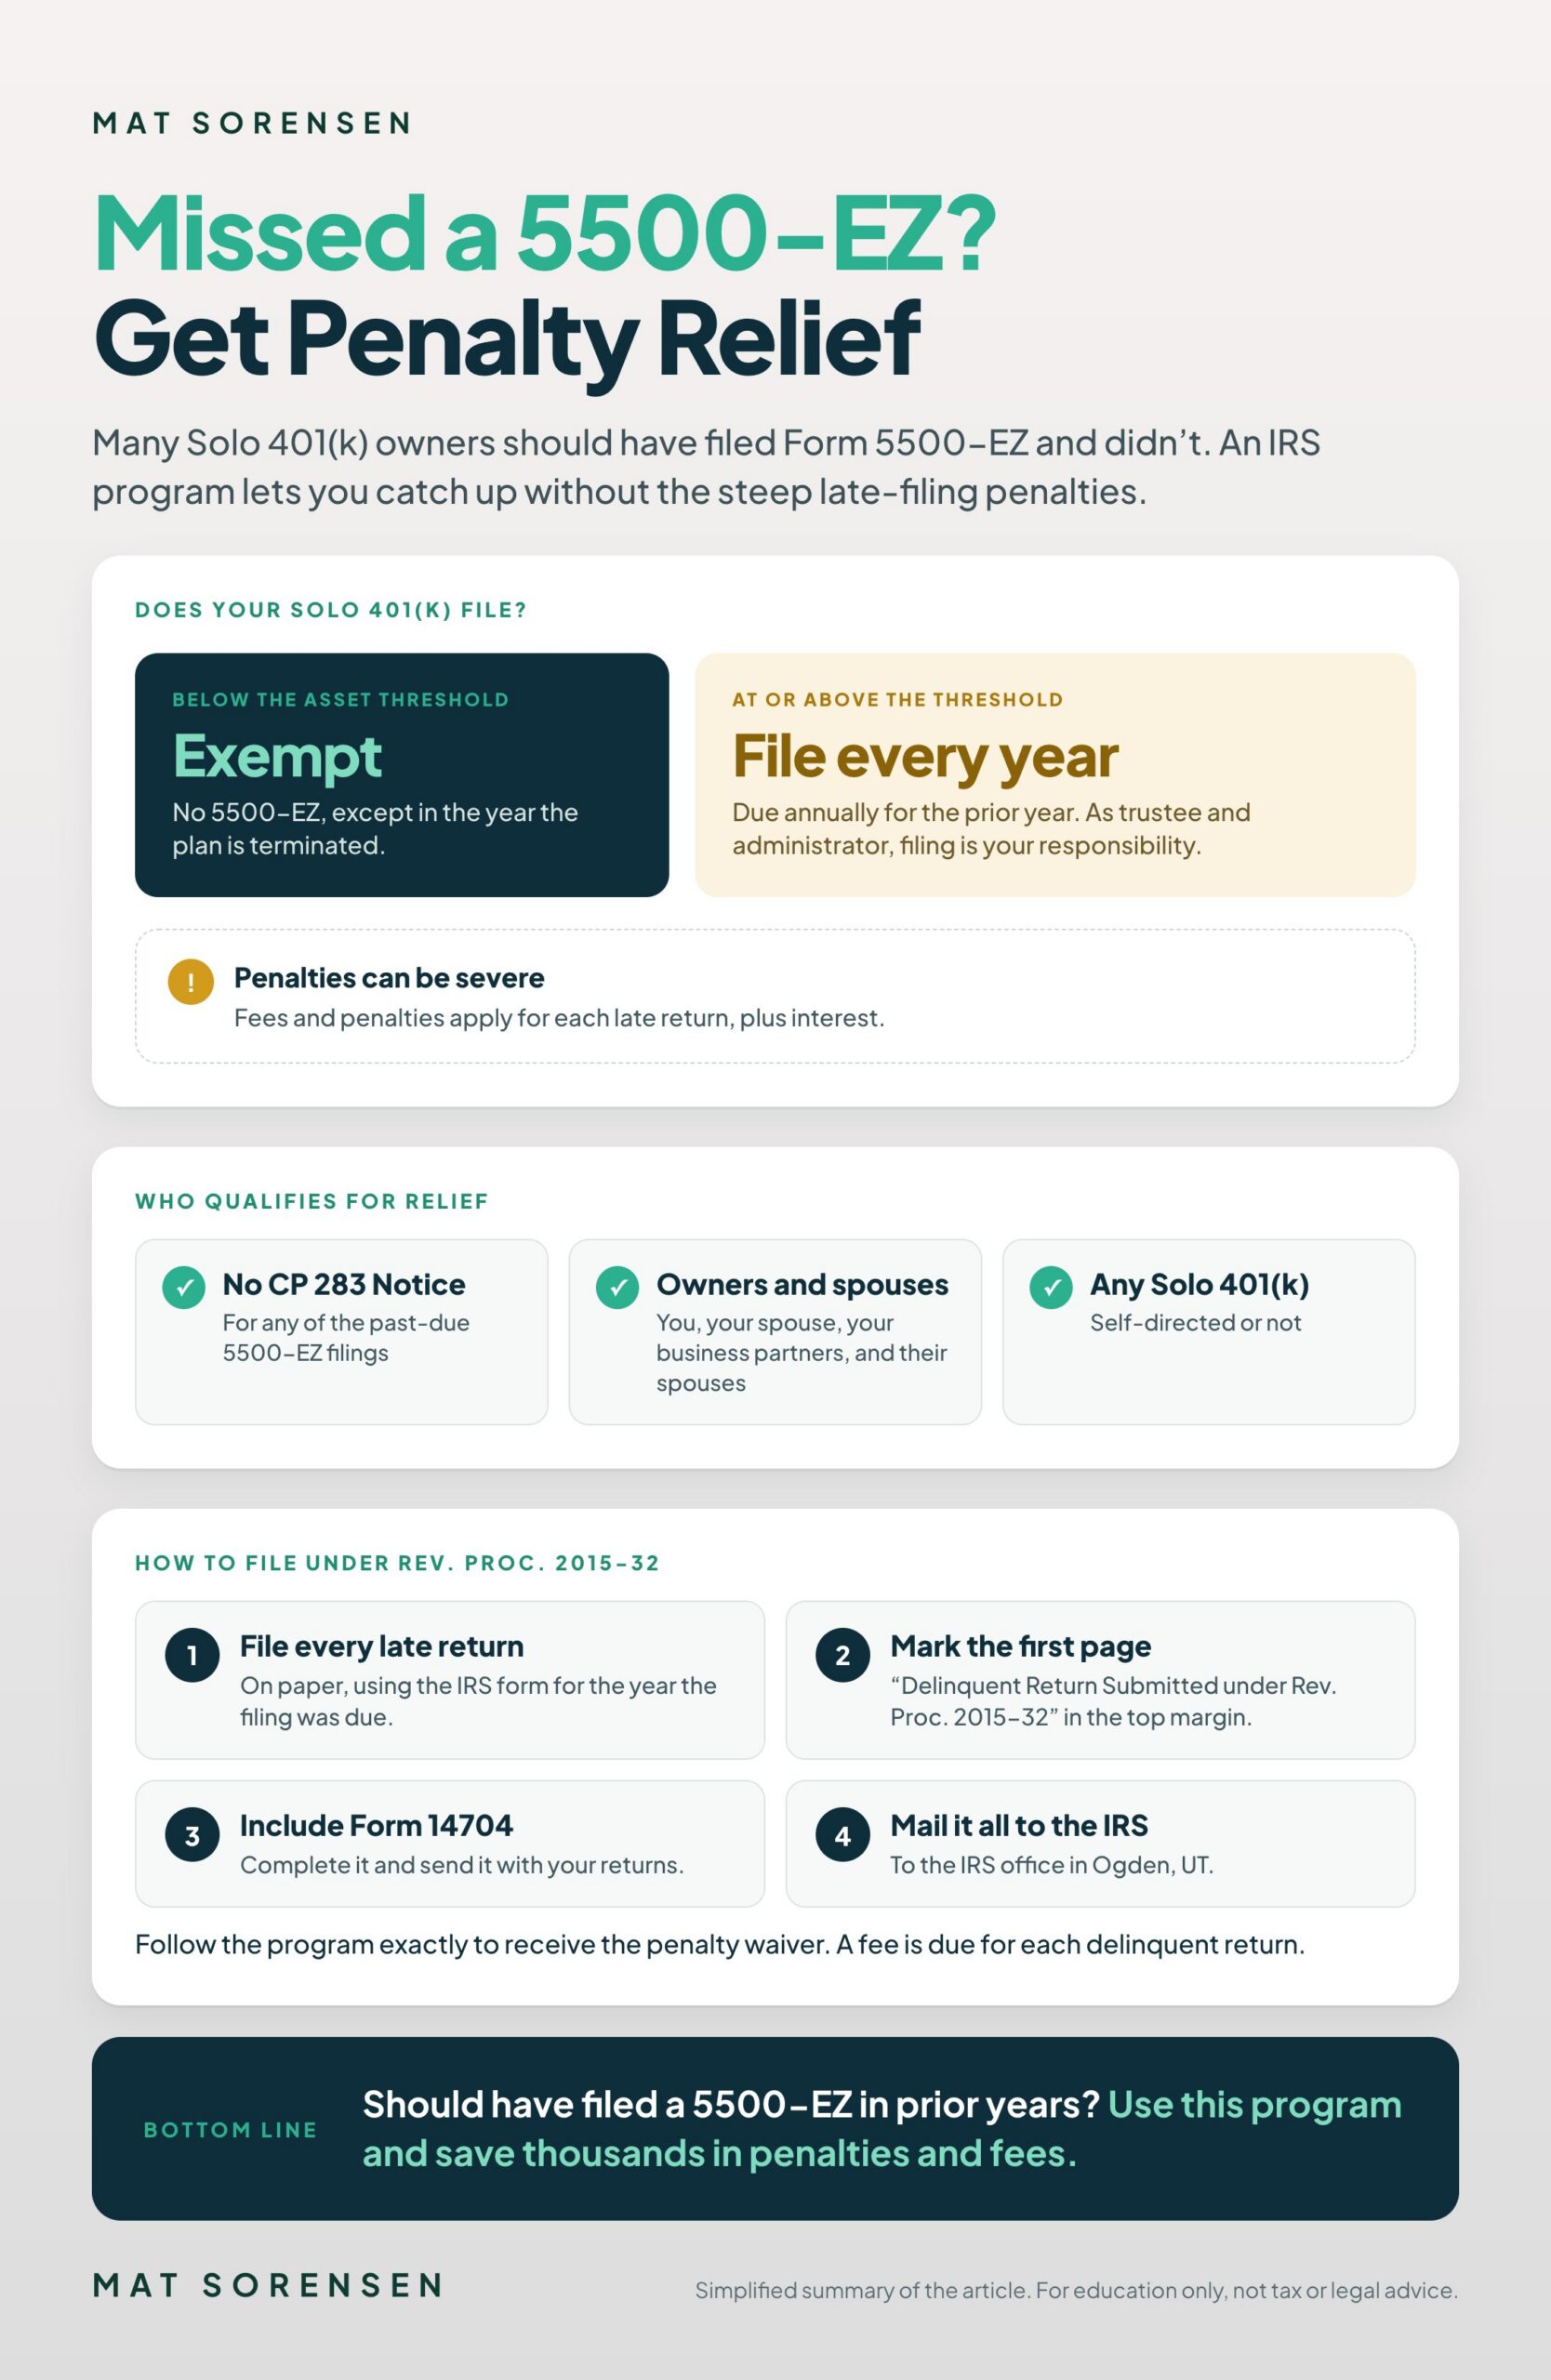
Infographic: when a Solo 401(k) must file Form 5500-EZ, who qualifies for the IRS late-filing penalty relief program, and the four steps to file under Rev. Proc. 2015-32

Benefits of Solo 401(k)s

One of the benefits of a Solo 401(k) is the ease of administration and control, because you can be the 401(k) trustee and administrator. However, as the 401(k) administrator and trustee, it is your own responsibility to make the appropriate tax filings. This would include filing any required tax returns for the 401(k).  Solo 401(k)s with less than $250,000 in assets are exempt and do not need to file a 5500-EZ. All plans with assets valued at $250,000 or greater must file a form 5500-EZ annually. A tax return is also required for a Solo 401(k) when the plan is terminated, even if the plan assets are below $250,000.

Recently, more and more Solo 401(k) owners have contacted us because they set up their Solo 401(k) online or with some other company, and were never made aware that they are supposed to file a 5500-EZ when their plan assets exceed $250,000.  Some of these individuals have multiple years in which they should have filed the 5500-EZ, but failed to do so. The penalties for failing to file a 5500-EZ when it is required can be quite severe, with fees and penalties as high as $150,000 for each late return plus interest.

Failure to File Relief

Fortunately, the IRS has a temporary pilot program that provides automatic relief from IRS Late filing penalties on past due 5500-EZ filings.  The penalty relief began as a temporary program in 2014 and was made permanent via Rev Proc 2015-32.

In order to qualify for this program, your Solo 401(k) plan must not have received a CP 283 Notice for any past due 5500-EZ filings, and the only participants of your Solo 401(k) plan can be you and your spouse, and your business partner(s) and their spouse. There is a $500 fee due for each delinquent return up to a total of $1,500 or three years.  This program is available to all Solo 401(k) plans, regardless of whether it is a self-directed plan.

The IRS has provided details via Rev Proc 15-32. In order to qualify and receive a waiver of penalties under the program, you must follow the program exactly.  In short, you must do all of the following:

  1. 1File all delinquent returns using the IRS form in the year the filing was due. This must be via paper form.
  2. 2Mark on the top margin of the first page, “Delinquent Return Submitted under Rev. Proc. 2015-32.”
  3. 3Complete and include IRS Form 14704.
  4. 4Mail all documents to the IRS, Ogden, UT office.

In sum, if you have a Solo 401(k) plan that should have filed a 5500-EZ for prior years, then you should take advantage of this program, which will save you thousands of dollars in penalties and fees.  If you have any questions about this program or would like assistance with submitting your late 5500-EZ filings under this program, please contact our law firm as we are assisting clients with current and past due 5500-EZ filings for their Solo 401(k)s.

FREE SOLO 401(K) GUIDE

Self-employed? Learn how a self-directed Solo 401(k) works and how much you can contribute.

Get the Free Solo 401(k) Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

Maxed Out Your 401(k), What’s Next?

Photo of graffiti on the ground reading as "What's Next?"For most American workers and business owners, the first vehicle to save and invest in is your 401(k). The tax benefits and the typical company matching that offers free company money make a 401(k) a great place to save and invest for the long-haul. But what if you’ve maxed out your 401(k) contributions? What else can you do?

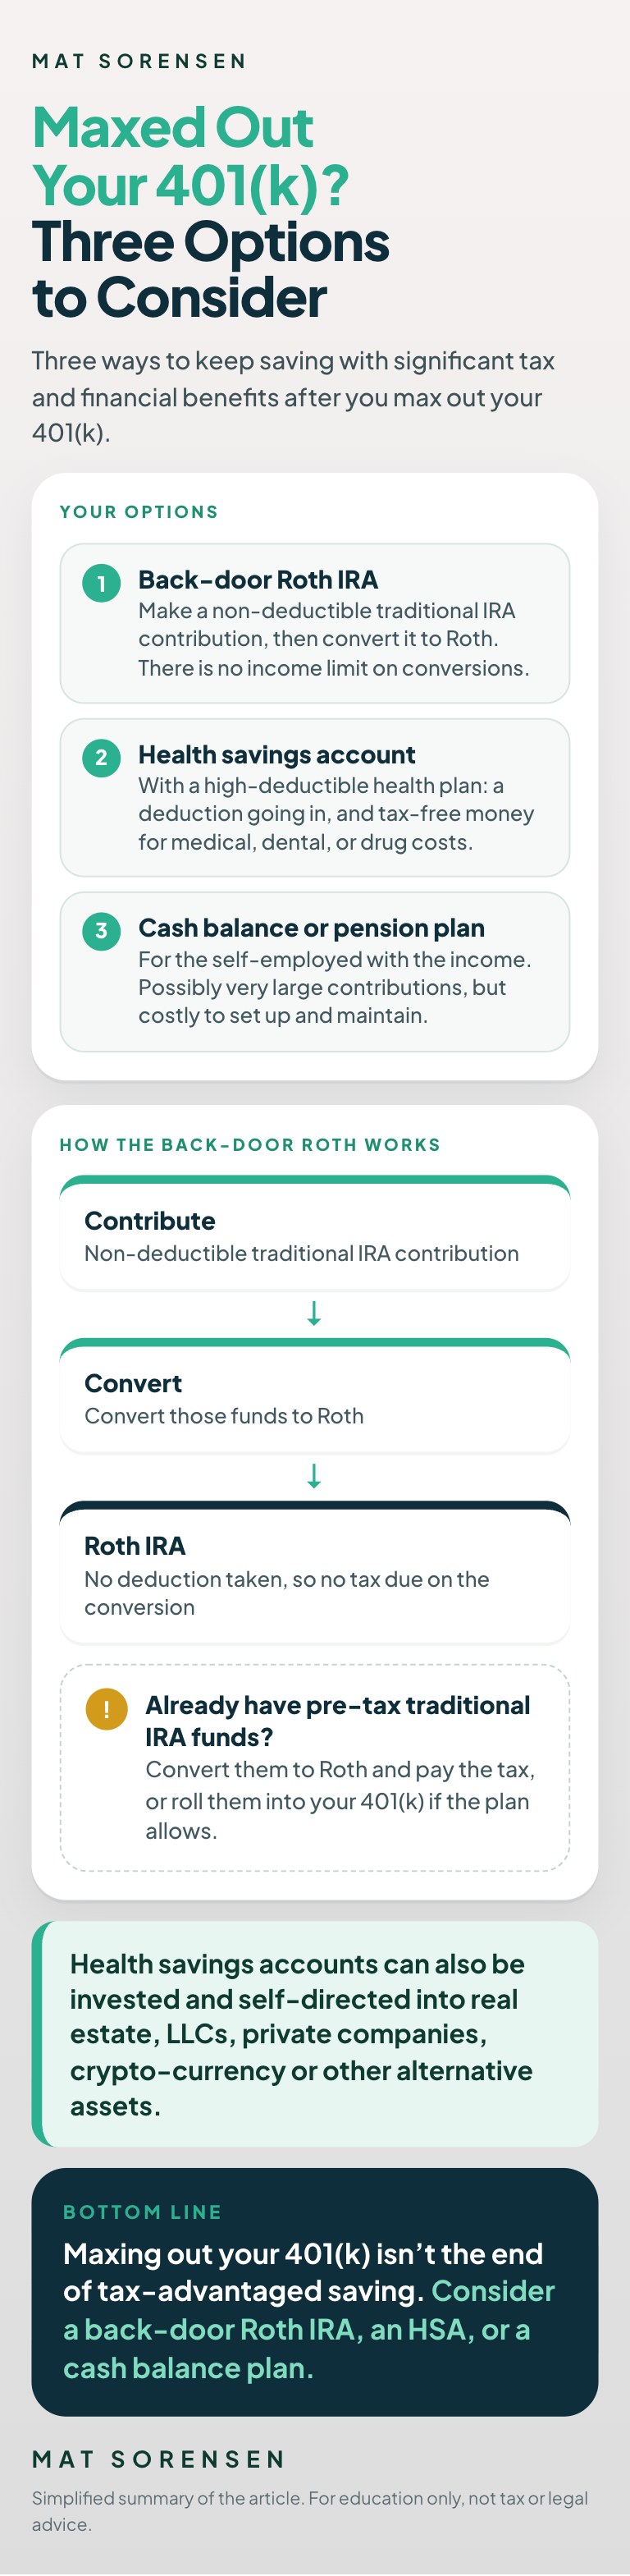
Here are the three options you should consider that provide significant tax and financial benefits:

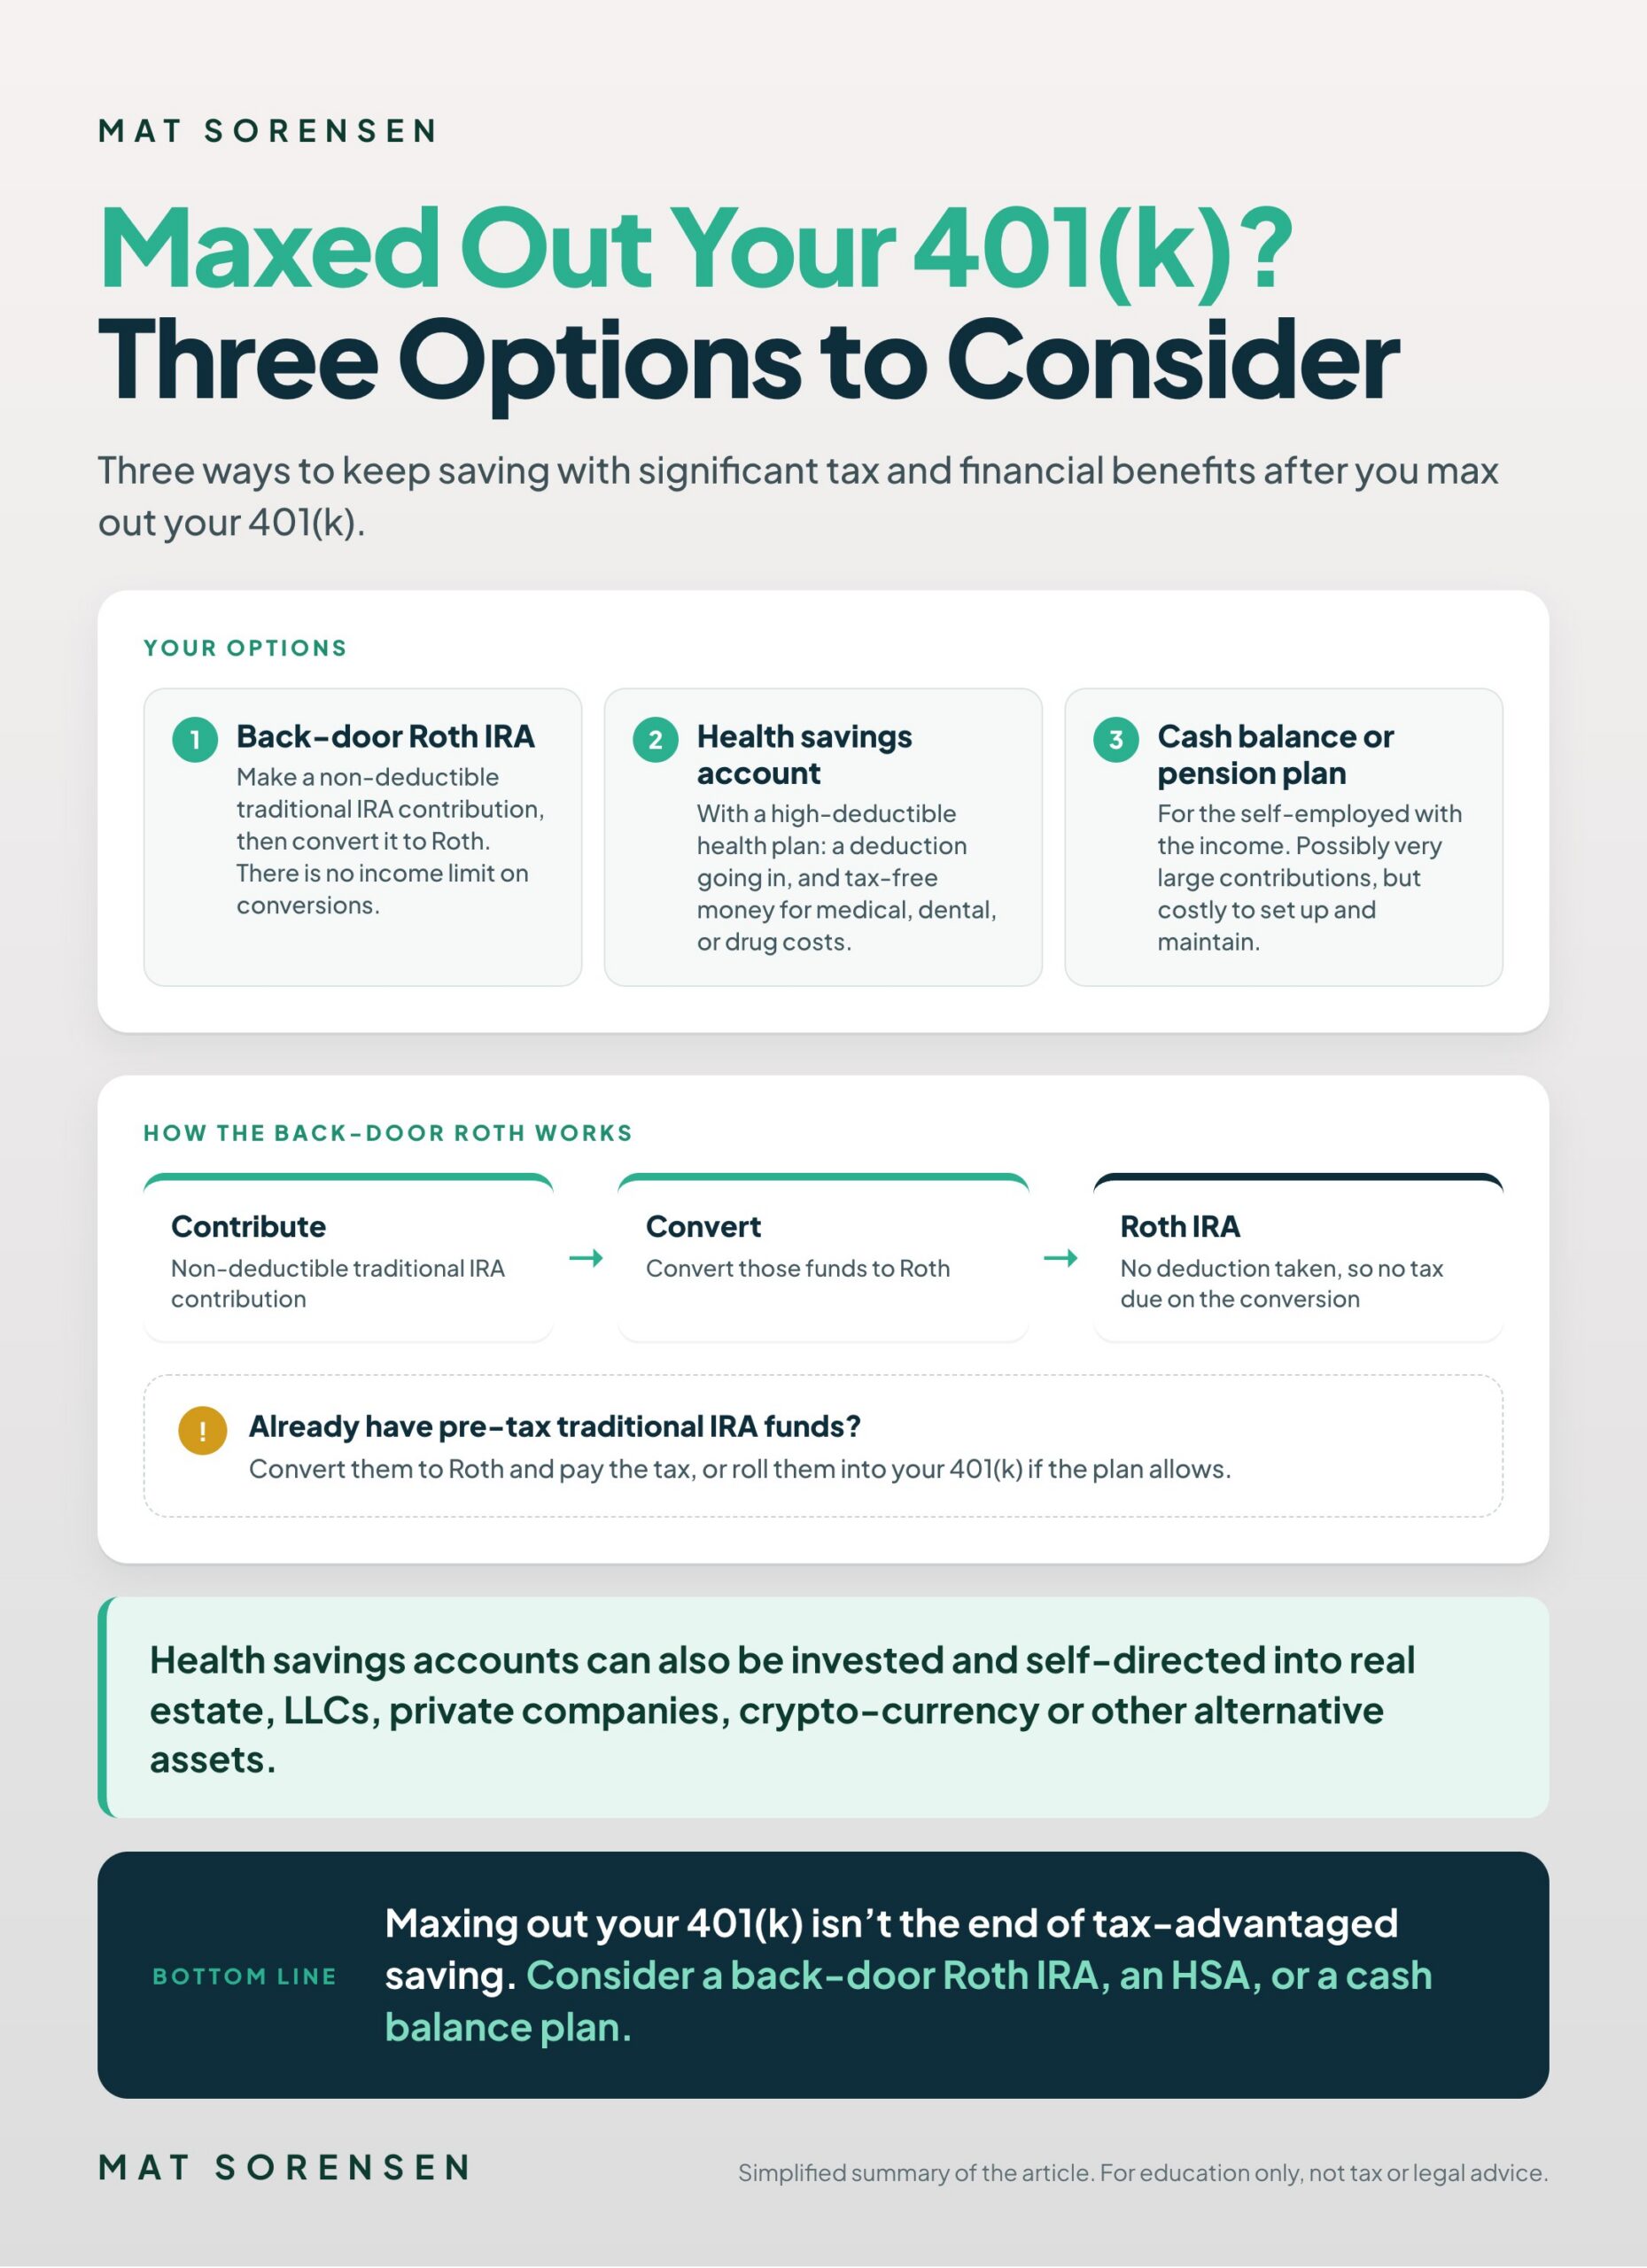
Infographic: three options after maxing out your 401(k), the back-door Roth IRA, a health savings account, and a cash balance or defined benefit plan

1. Back-Door Roth IRA

This is a really cool option that many clients utilize every year. (I do too.) First, you may be thinking that you can’t do a Roth IRA because your income is too high or because you already maxed out your 401(k). WRONG: It is still possible to do a Roth IRA, but you just have to know the back-door route. The reason it’s called a back-door Roth IRA is because you make a non-deductible traditional IRA contribution (up to $5,500 annual limit, $6,500 if 50 or older). Then, after the non-deductible traditional IRA contribution is made, you then convert the funds to Roth. There is no income limit on Roth conversions, and since you didn’t take a deduction on the non-deductible traditional IRA contribution, there is no tax due on the conversion to Roth. And now, voila, you have $5,500 in your Roth IRA. That’s the back-door route.

UPDATE (NOV 2026)

This section uses the IRA limits from when this article was written. For 2026, the IRA contribution limit is $7,500 ($8,600 if you’re 50 or older). (Source: IRS)

There is a road block though for some who already have funds already in traditional IRAs. The Roth conversion pro-rata rule states that you can’t convert only your non-deductible traditional IRA funds. Each conversion is treated as coming proportionally from all of your traditional IRA funds, including your pre-tax traditional IRA funds, which you got a deduction for and now pay tax on when you convert (this is figured on Form 8606 using the year-end value of all your traditional IRAs). So, if you have pre-tax traditional IRA funds and you want to do the back-door Roth IRA, you have two options:

  1. 1First, convert those pre-tax traditional IRA dollars to Roth and pay the taxes on the conversion.
  2. 2Second, if your 401(k) allows, you can roll those pre-tax traditional IRA dollars into your 401(k).

If you don’t have a traditional IRA, you’re on easy street and only need to do the two-step process of making the non-deductible traditional IRA contribution and then convert it to Roth.

You have until April 15th of each year to do this for the prior tax year. Additionally, while the GOP tax-reform restricted Roth re-characterizations, Roth conversions and the back-door Roth IRA route were unaffected. For more detail on the back-door Roth IRA, check out my prior article here.

2. Health Savings Account (HSA)

If you have a high-deductible health insurance plan, you can make contributions to your HSA up until April 15th of each year for the prior tax year. Why make an HSA contribution? Because you get a tax deduction for doing it, and because that money comes out of your HSA tax-free for your medical, dental, or drug costs. You can contribute and get a deduction, above the line, of up to $4,400 if you’re single or for up to $8,750 for family (2026). We all have these out-of-pocket costs, and this is the most efficient way to spend those dollars (from an account you got a tax deduction for putting money into). If you didn’t have a high deductible HSA-qualifying plan by December 1st of the prior year, then the HSA won’t work.

Any amounts you don’t spend on medical can be invested in the account and grow tax-free for your future medical or long-term care. Health savings accounts can also be invested and self-directed into real estate, LLCs, private companies, crypto-currency or other alternative assets. We’ve helped many clients invest these tax-favored funds using a self-directed HSA.

For more details on health savings accounts, check out my partner Mark’s article here.

3. Cash Balance Plan or Defined Benefit Plan

If you’re self-employed you may consider establishing a cash balance plan or a defined benefit plan (aka “pension”), where you can possibly contribute hundreds of thousands of dollars each year. The amount of your contribution depends on your income, age, and the age and number of employees you may have. A cash balance plan or defined benefit plan/pension will cost you ten thousand dollars or more in fees to establish, and is far more expensive to maintain and administer. But, if you have the income, it’s a valuable option to consider. For more details on cash balance plans, check out Randy Luebke’s article here.

FREE SELF-DIRECTED IRA GUIDE

Learn how a self-directed Roth IRA can invest in real estate, private companies, notes, and more, and keep the growth tax-free.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist
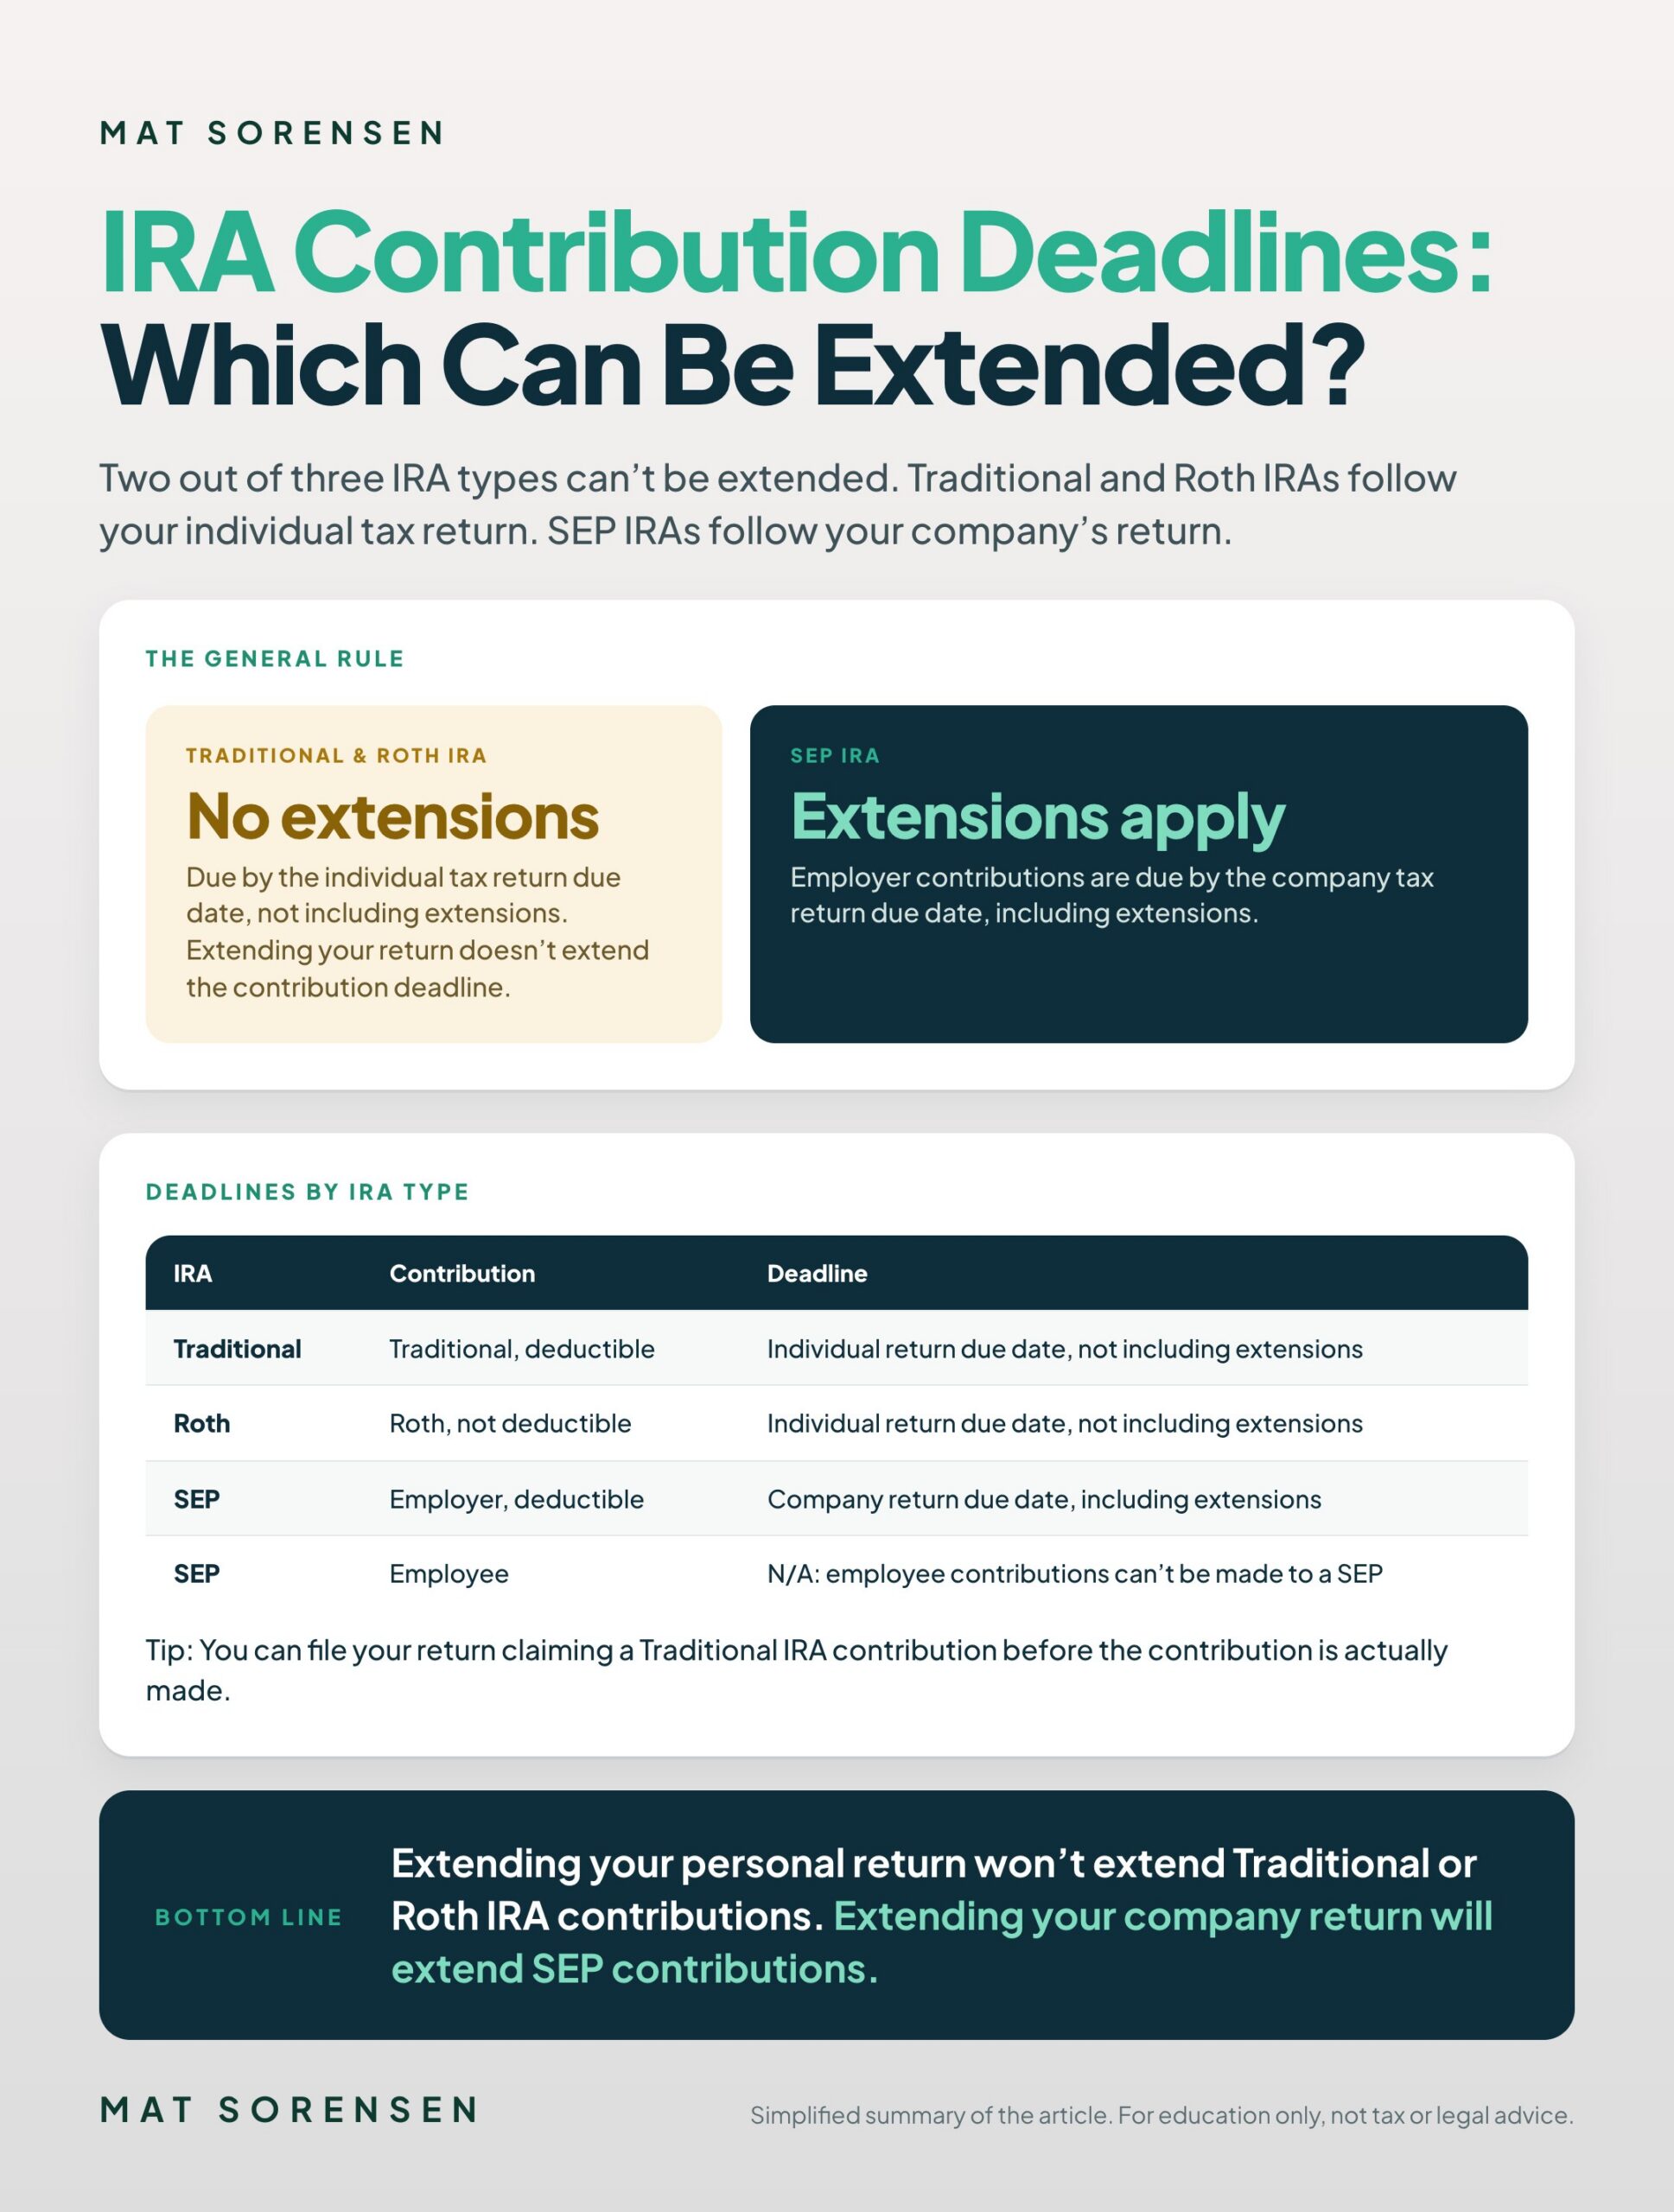
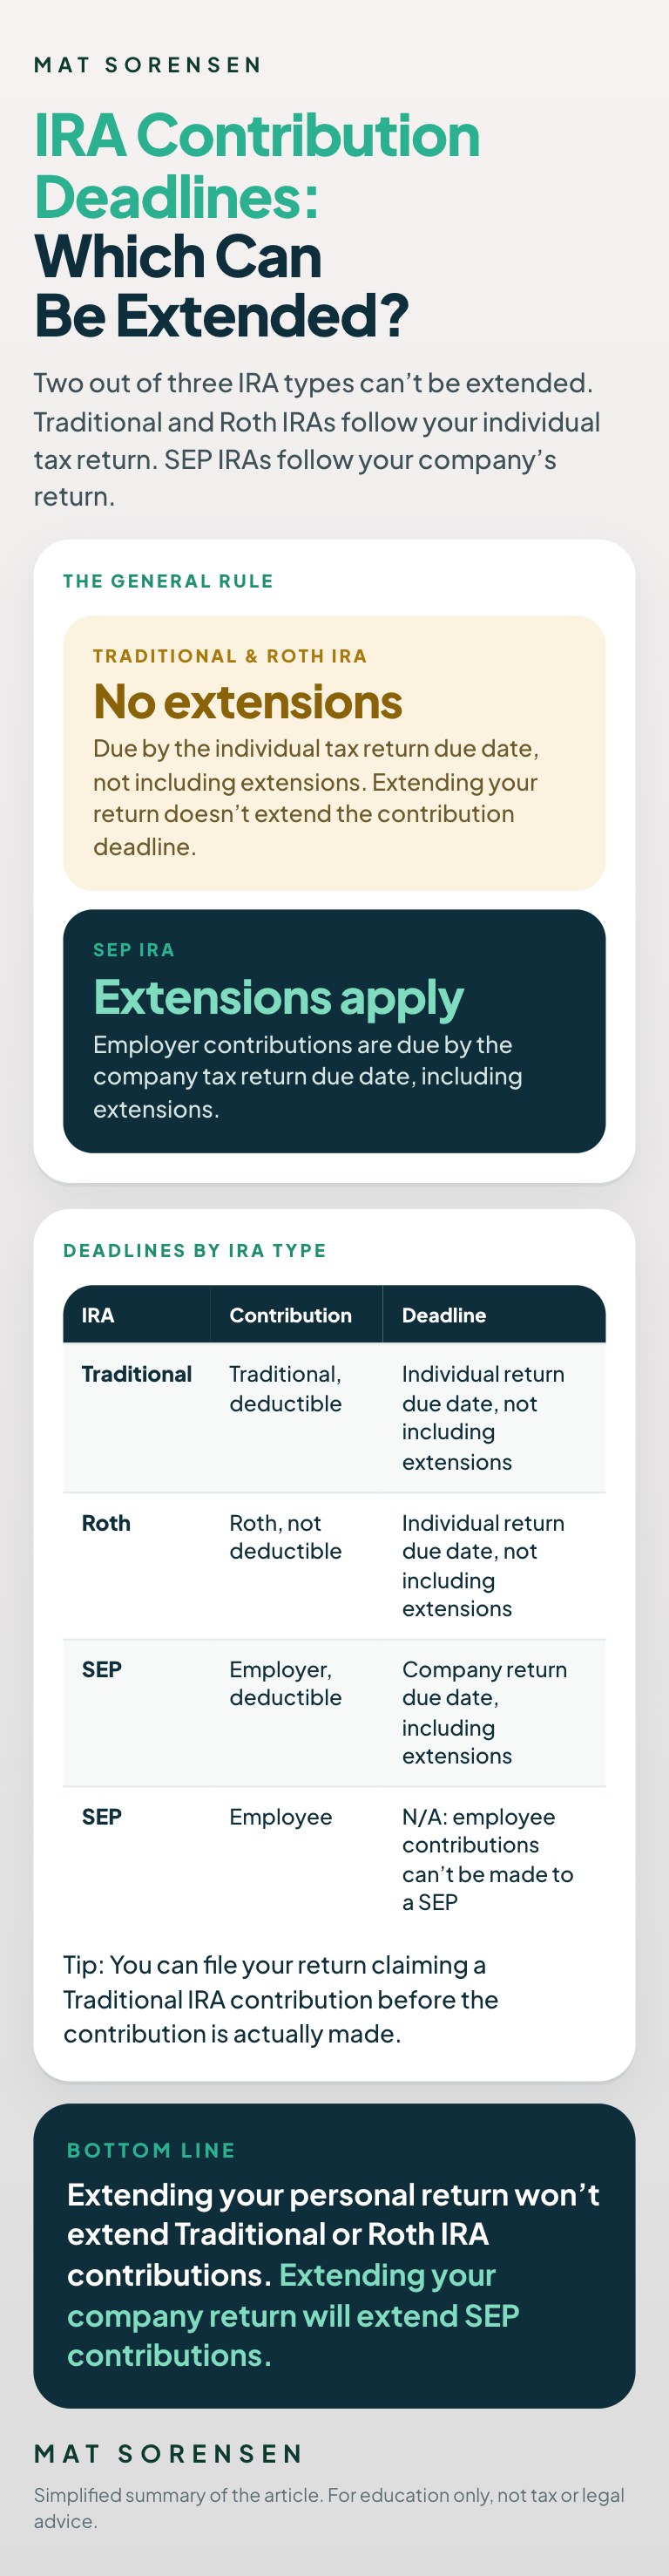
IRA Contribution Deadlines: Two Out of Three IRA Types Can’t be Extended

You have until April 18th, 2017 to make 2016 IRA contributions for Roth and Traditional IRAs. If you’re self-employed and are using a SEP, your deadline is determined by your company’s tax filing deadline (e.g. s-corp, partnership, or sole prop). So, if you were an s-corp or partnership in 2016, then your filing deadline was March 15th, 2017. If you are a sole prop, then the deadline is April 18th, 2017. If you extended your company return, that extension will also apply to your SEP IRA contributions. The table below breaks down the deadlines and extension options for Traditional, Roth and SEP IRAs.

UPDATE (NOV 2026)

This article was written for the 2016 tax year. The same rules apply every year: Traditional and Roth IRA contributions are due by your tax return due date, not including extensions (generally April 15 of the next year), and SEP IRA contributions by the business’s tax return due date, including extensions. (Source: IRS Pub 590-A; IRS SEP FAQ)

Infographic: Traditional and Roth IRA contribution deadlines do not include extensions, while SEP IRA employer contribution deadlines do
Type of IRA Contribution Type Deadline Details
Traditional IRA Traditional, Deductible April 18th, 2017: Due Date for Individual Tax Return Filing (not including extensions). IRC § 219(f)(3); You can file your return claiming a contribution before the contribution is actually made.  Rev. Rul. 84-18.
Roth IRA Roth, Not Deductible April 18th, 2017: Due Date for Individual Tax Return Filing (not including extensions). IRC § 408A(c)(7).
SEP IRA  Employee, Deductible N/A: Employee contributions cannot be made to a SEP IRA plan.
Employer Contribution, Deductible March 15/April 15th: Due Date for Company Tax Return Filing (including extensions). IRC § 404(h)(1)(B).

As outlined above, you have until the 2016 individual tax return deadline of April 18th, 2017 to make 2016 Traditional and Roth IRA contributions. The deadline for Traditional and Roth IRAs, however, does not include extensions. So, even if you extend your 2016 tax return, your 2016 Traditional and Roth IRA contributions are still due on April 18th, 2017.

SEP IRA contribution deadlines are based on the company tax return deadline, which could be March 15th if the company is taxed as an s-corporation or partnership, and April 15th if it is a c-corporation or sole proprietorship. Keep in mind that this deadline includes extensions, so if you extend your company tax return filing, you will extend the time period to make 2016 SEP IRA contributions.

FREE SELF-DIRECTED IRA GUIDE

Learn how to invest your IRA in real estate, private companies, notes, precious metals, and more.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist
Self Directed IRAs, Prohibited Transactions, and the IRS Statute of Limitations: Thiessen v. Commissioner

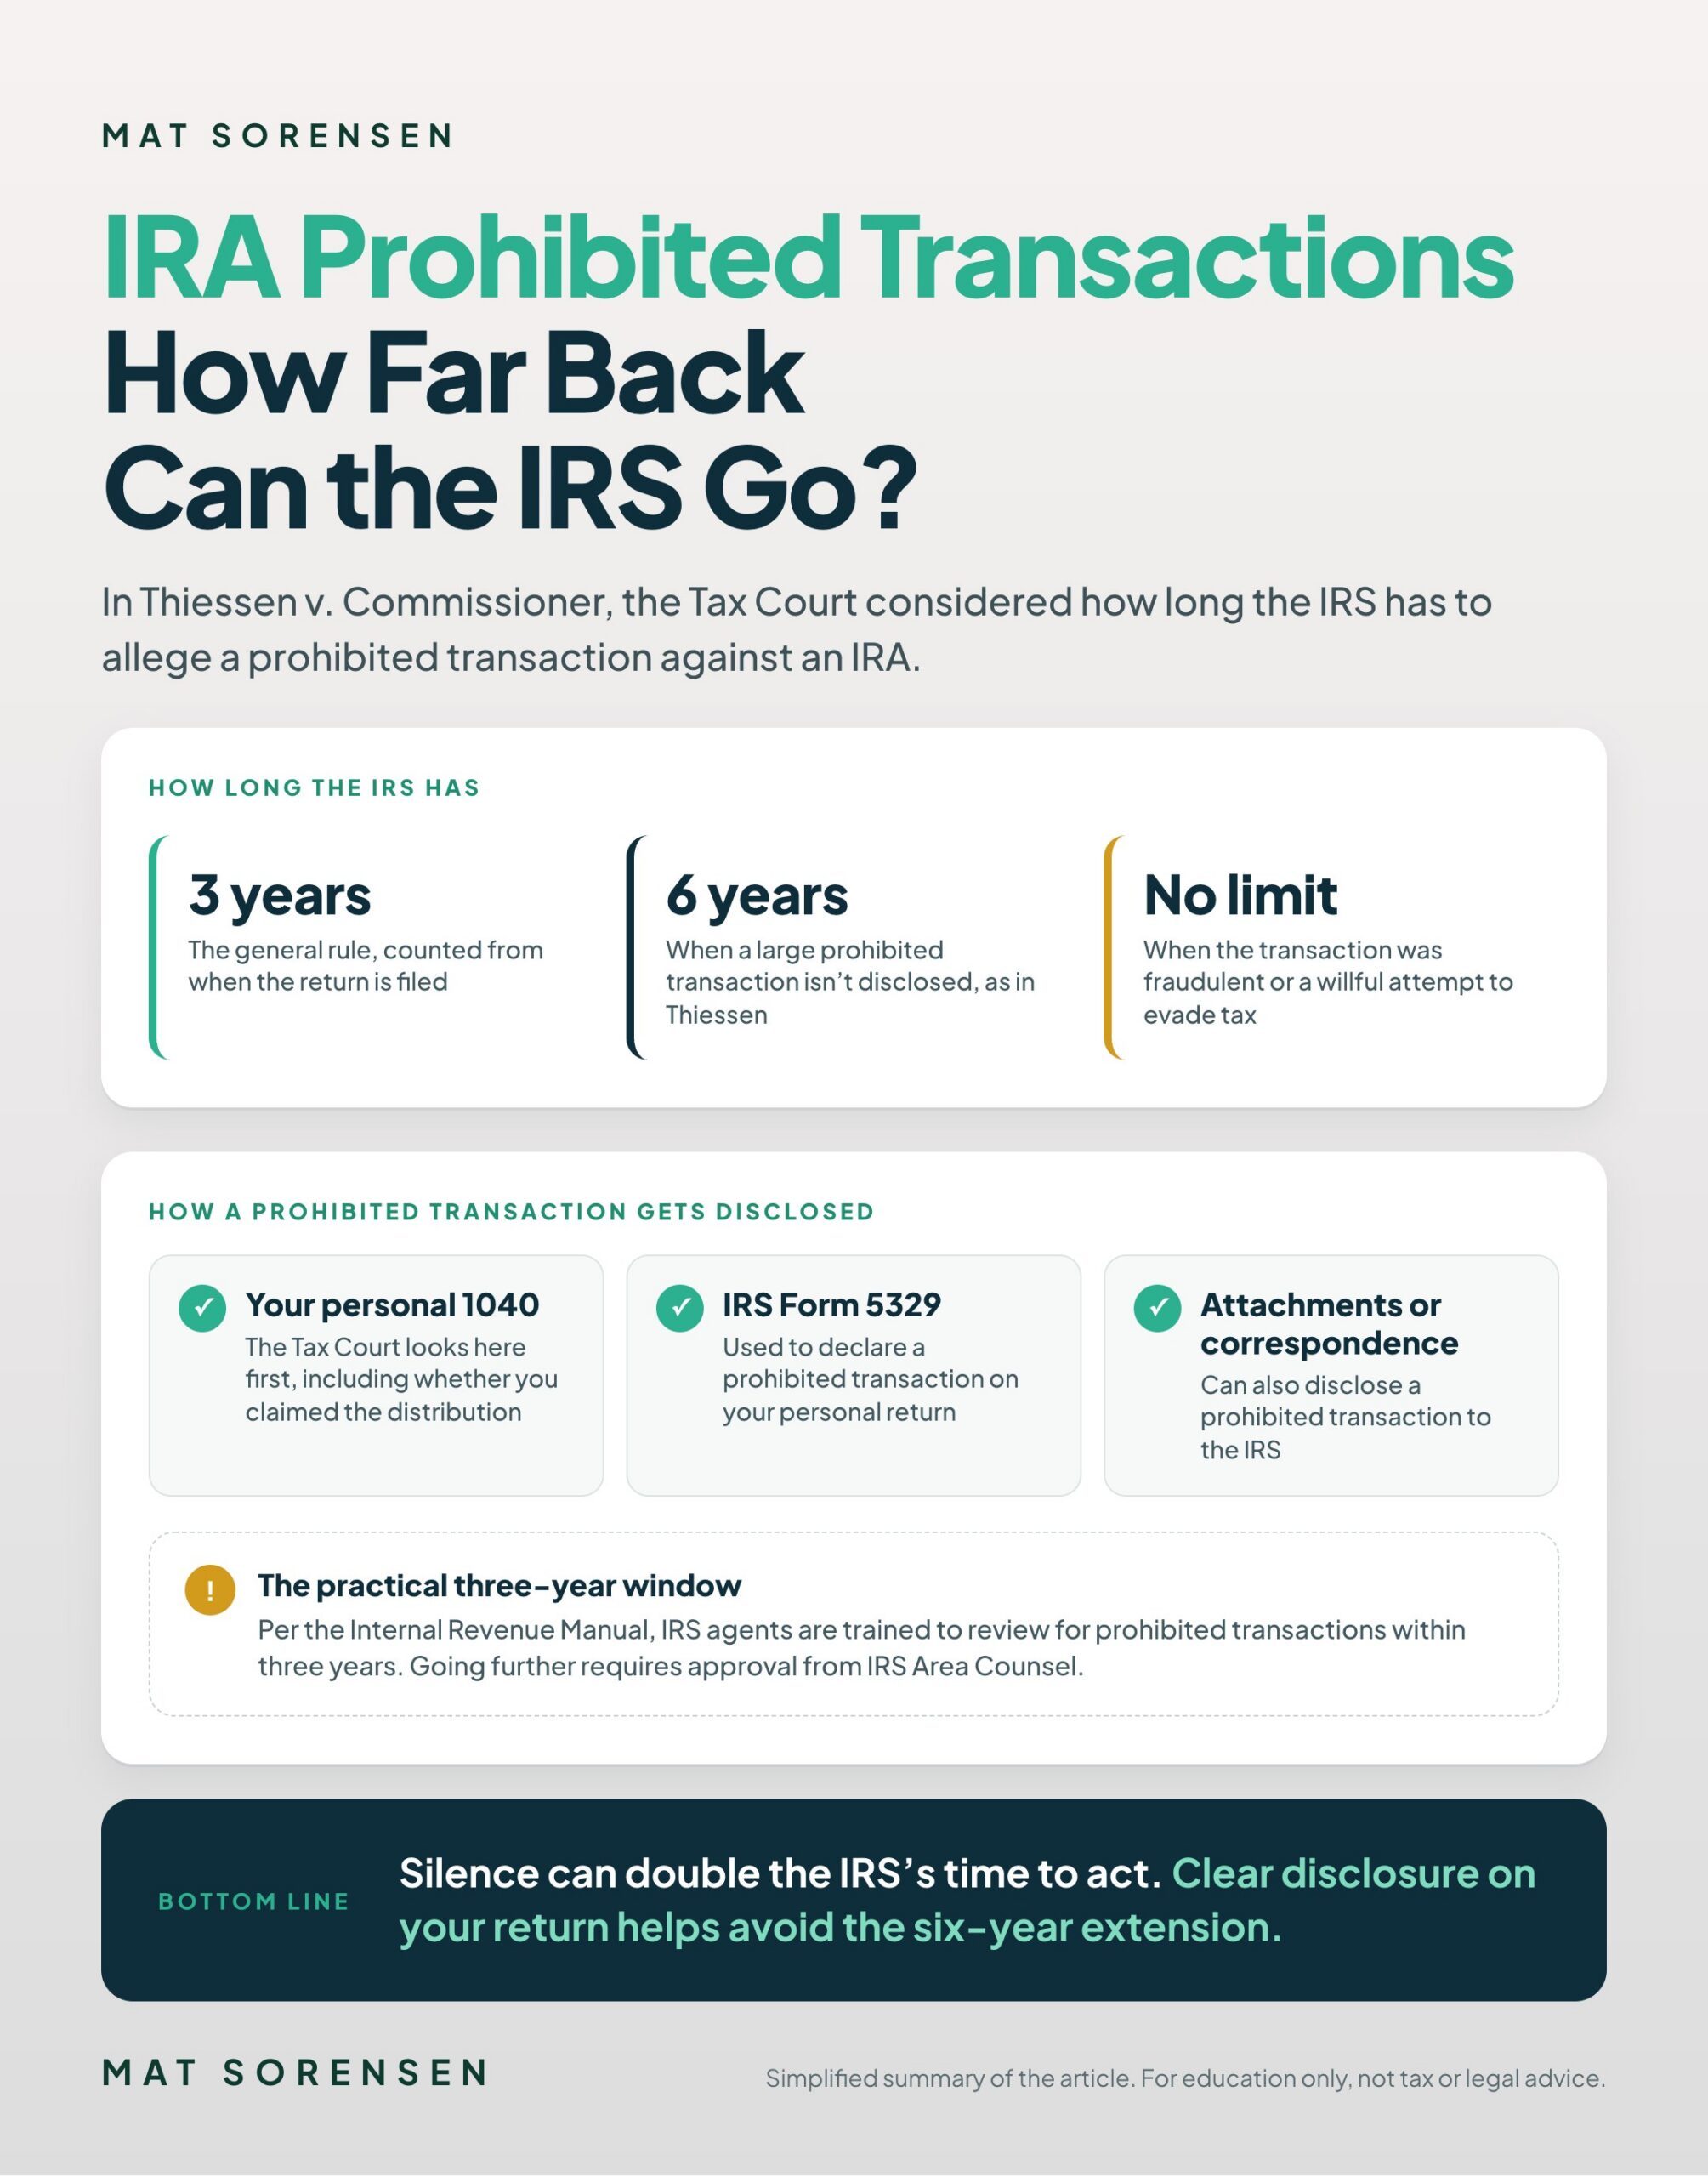
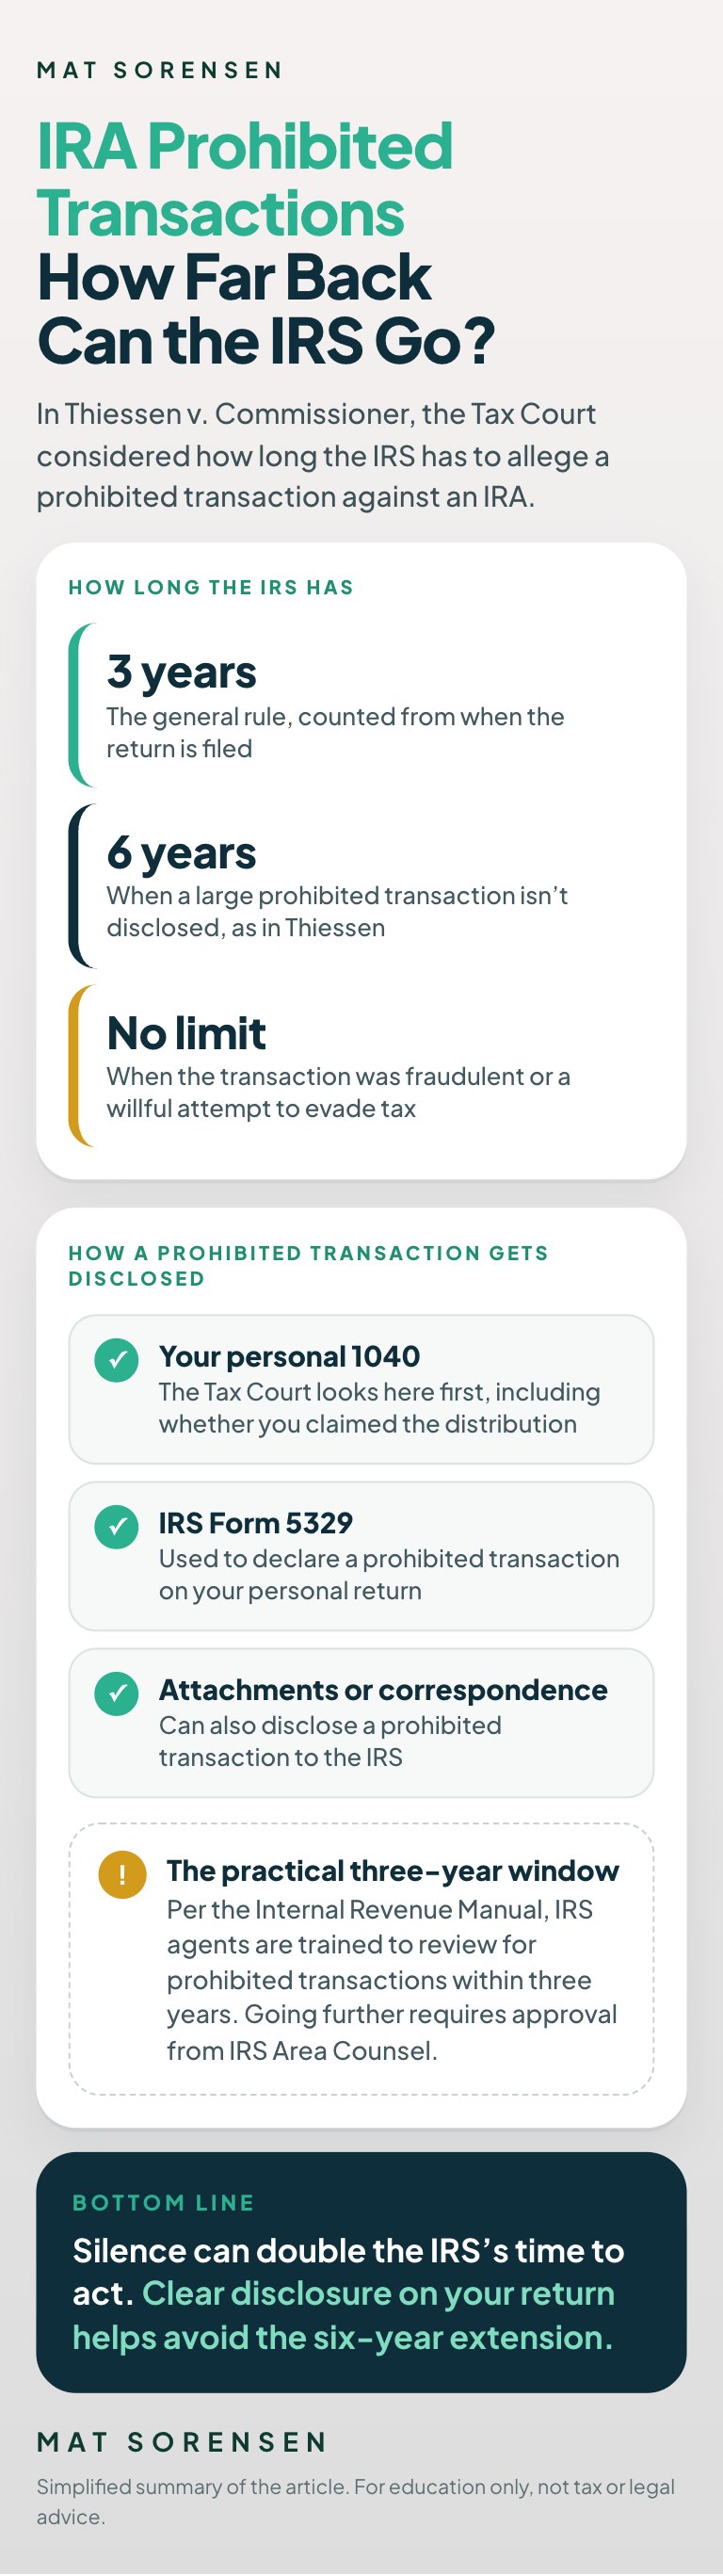
In the recent case of Thiessen v. Commissioner, 146 T.C. No. 7 (2016), the Tax Court considered how long the IRS has to allege a prohibited transaction against an IRA. In general, the IRS must allege a prohibited transaction against your IRA within three years after the return is filed. IRC 6501(a). However, that time-period may be extended another three years for a total of six years pursuant to IRC 6501(e)(1) when the taxpayer fails to report an amount that is in excess of 25% of the gross income stated in the return.

Infographic: the three-year, six-year, and unlimited IRS look-back periods for IRA prohibited transactions after Thiessen v. Commissioner, and how a prohibited transaction gets disclosed

What Counts as a Failure to Report

For prohibited transaction rule violations, a failure to report occurs when you don’t disclose the prohibited transaction to the IRS or when you fail to claim the distribution that occurs from a prohibited transaction on your personal tax return. A prohibited transaction could be disclosed to the IRS through attachments to the return or other correspondence but the Tax Court first looks to see what was reported to the IRS on the IRA owner’s personal 1040 tax return for the years in question. In other words, if you don’t volunteer clear information of a prohibited transaction to the IRS then the limitation period can be extended up to a total of six years so long as the prohibited transaction would result in a gross income in excess of 25% of the taxpayer’s personal return. Note: IRS Form 5329 is used to declare a prohibited transaction on your personal return.

There are a few very important takeaways from the Tax Court’s ruling in Thiessen and from the IRS Internal Revenue Manual on Prohibited Transactions.

Statute of Limitation Tips

PRACTICAL THREE YEAR PERIOD
According to the IRS Agent Manual, Internal Revenue Manual, 4.72.11.6, IRS agents are instructed and trained to only review for prohibited transactions within a three-year window. In order to pursue a prohibited transaction past three years, an agent must receive approval from IRS Area Counsel. So, for practical purposes, the IRS is examining prohibited transactions within a three-year window.

FAILURE TO DISCLOSE SIX YEAR PERIOD
As had occurred in Thiessen, if any IRA owner fails to disclose a prohibited transaction to the IRS, the IRS may pursue a prohibited transaction for up to six years. This six-year clock runs six years after you filed your return in question. So, if you filed a 2010 personal return on April 15, 2011, and if the return did not include disclosure of a prohibited transaction, the IRS could pursue a prohibited transaction up until April 15, 2017. Keep in mind, this failure to report though must be a prohibited transaction that exceeds 25% of the gross income of the taxpayer for the year in question.

WATCH OUT

A final word to note is that the IRS may pursue prohibited transactions past six years and into an indefinite time-period when the prohibited transaction was fraudulent or a willful attempt to evade tax. IRC 6501(c)(1),(2),(3). I’m not aware of cases in this situation, nevertheless, don’t expect to be in safe waters if you fraudulently entered into a prohibited transaction as the statute of limitations never runs in those situations.

THE SELF-DIRECTED IRA HANDBOOK

Mat’s best-selling guide to the rules: prohibited transactions, UBIT, IRA/LLCs, and the mistakes to avoid.

Get the Free Handbook

Prefer to talk it through? Book a call with a Directed IRA specialist