Solo 401(k) vs SEP IRA — Same Income, Twice the Contribution

Same business, same $100,000 income, wildly different retirement outcomes: one owner saves $25,000 in a SEP IRA, the other $49,500 in a Solo 401(k)—nearly double, with nothing changed but the account type. The difference isn’t performance; it’s plan design. The Solo 401(k) is engineered for today’s self-employed, while the SEP IRA remains a 1978-era solution with modern limitations. For self-employed professionals running their business through an S corporation—as most profitable ones should—the contribution gap between a Solo 401(k) and a SEP IRA widens even further.

The real question isn’t “Which account is better?” but “Which account is better for me, given my income, age, entity type, and contribution rules?” The answer is arithmetic, not which form is simpler. In this article, we’ll break down three reasons the Solo 401(k) wins for most business owners, plus the one common scenario where a SEP IRA still makes sense. We’ll also show what $50,000 a year can grow into in each account—and why, despite sharing a $72,000 annual cap, the Solo 401(k) reaches it with nearly $100,000 less in W-2 compensation.
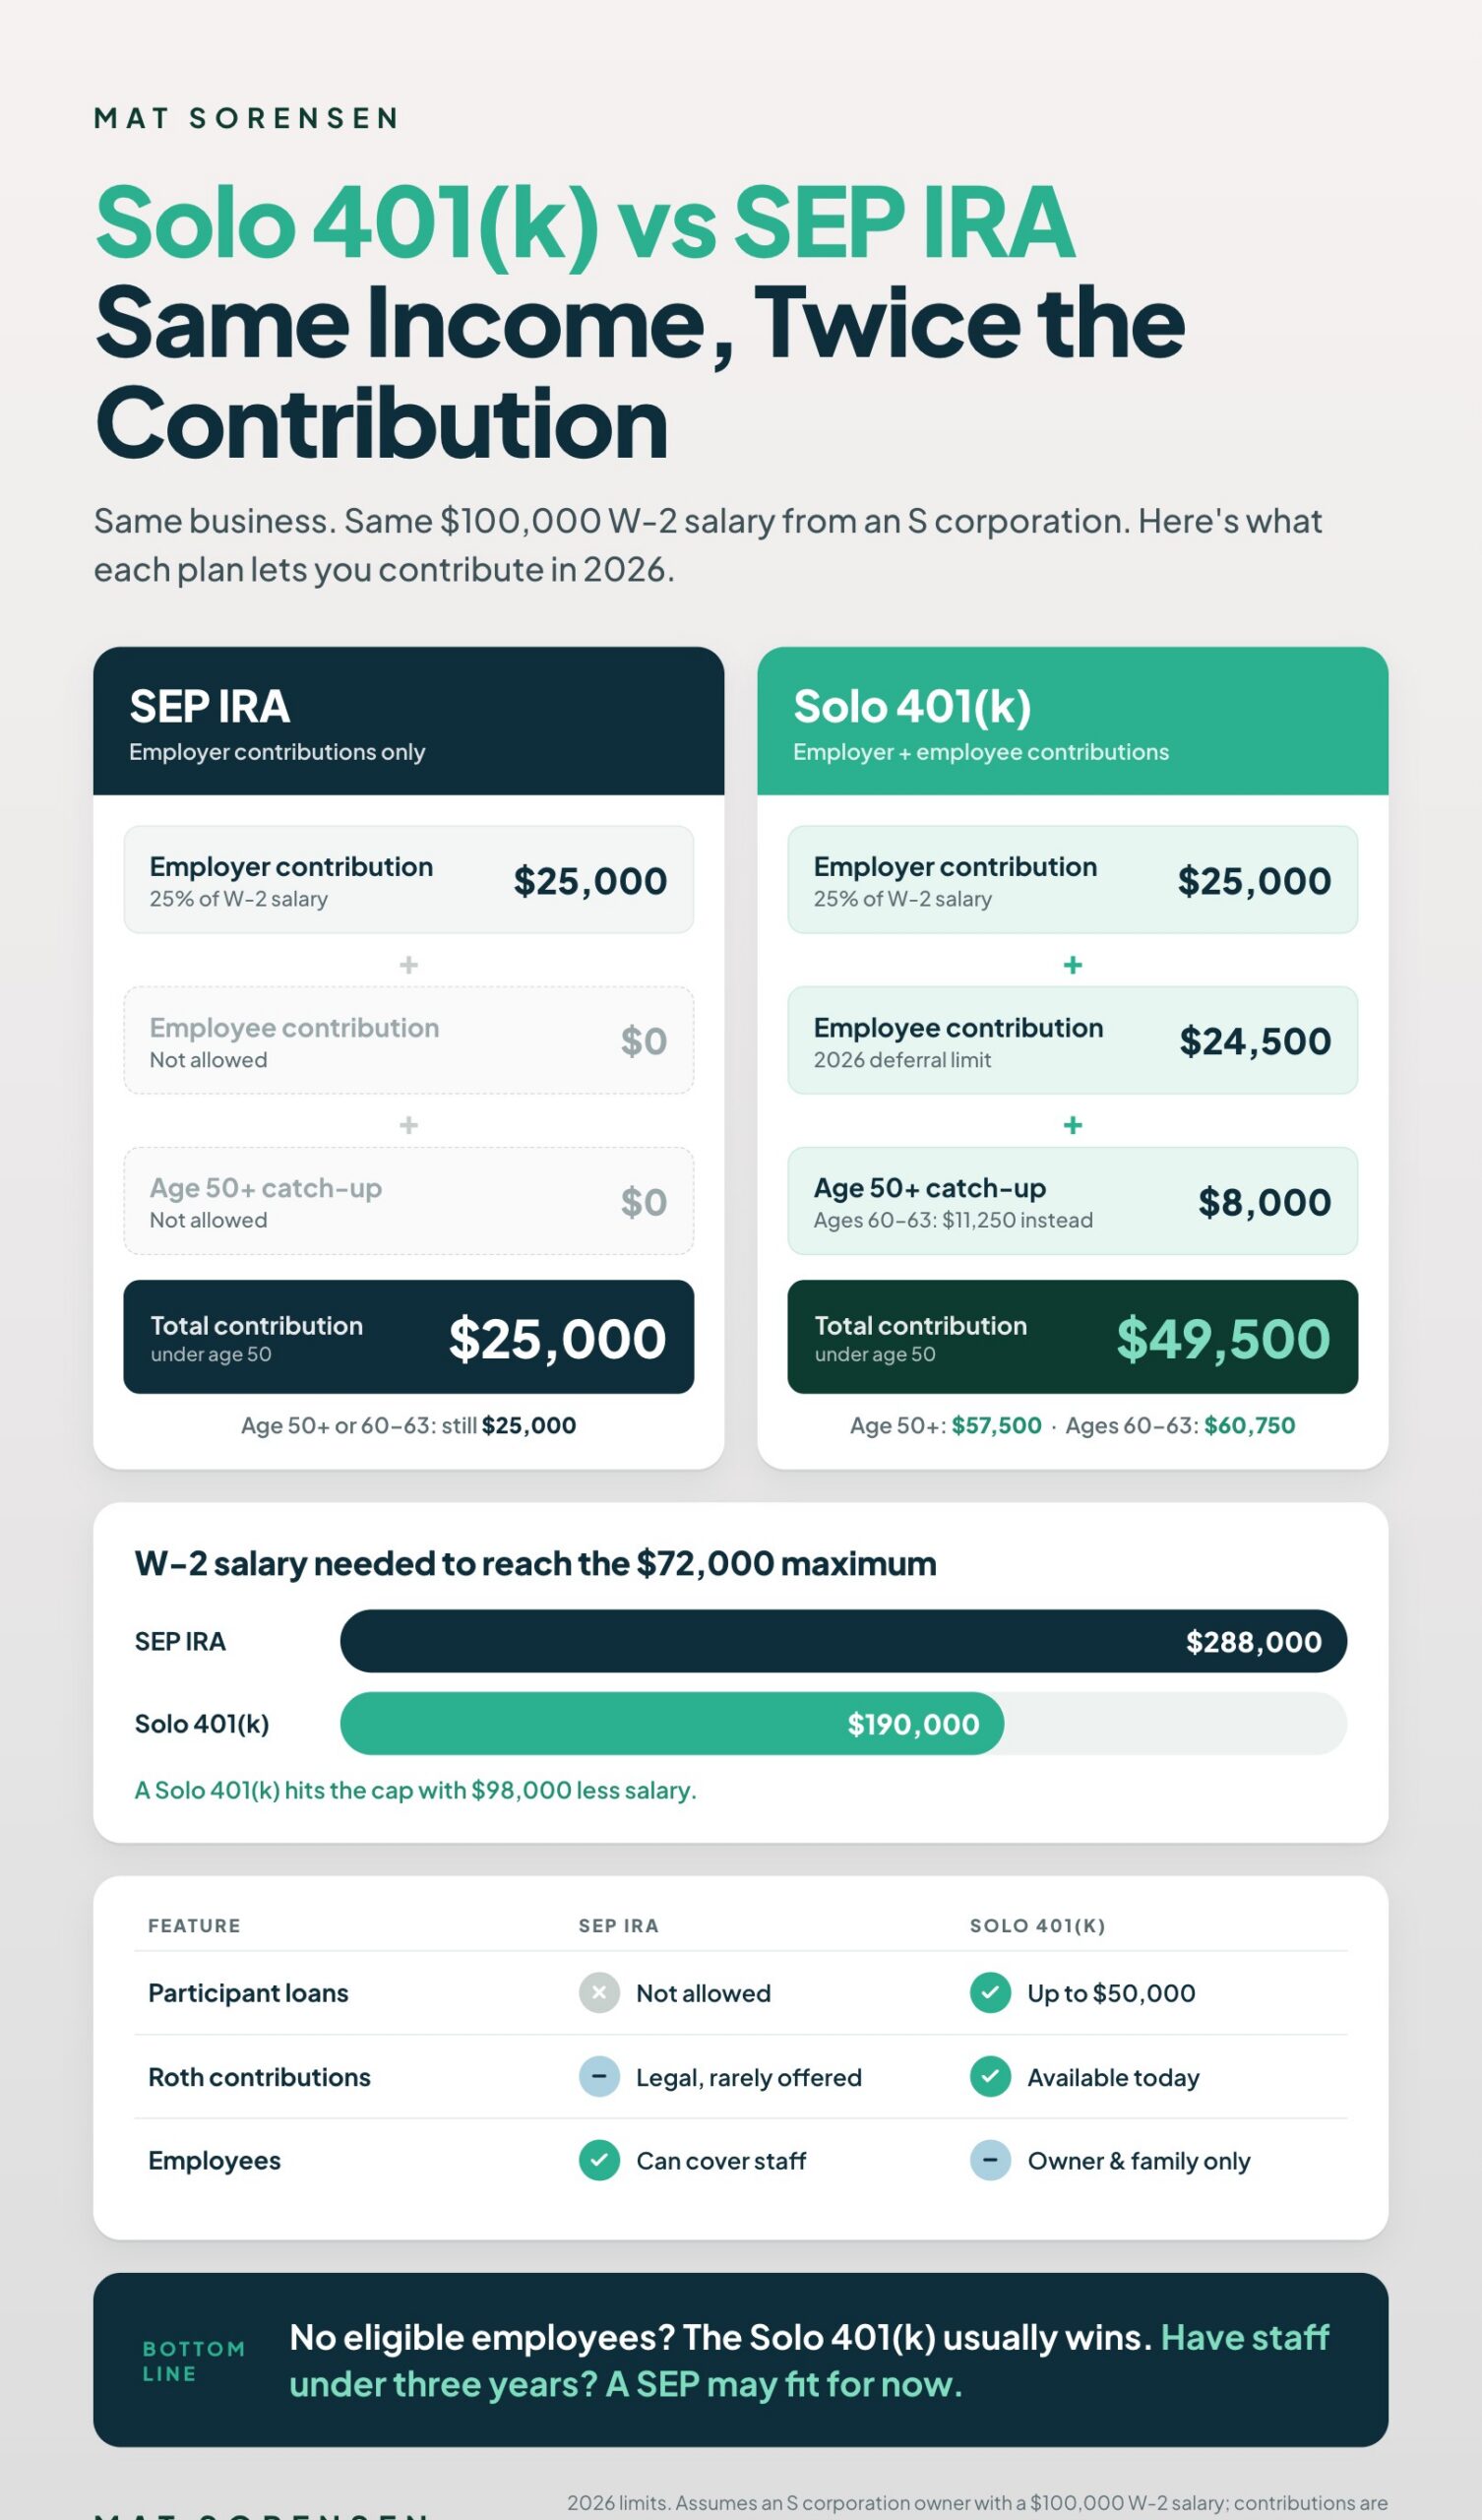
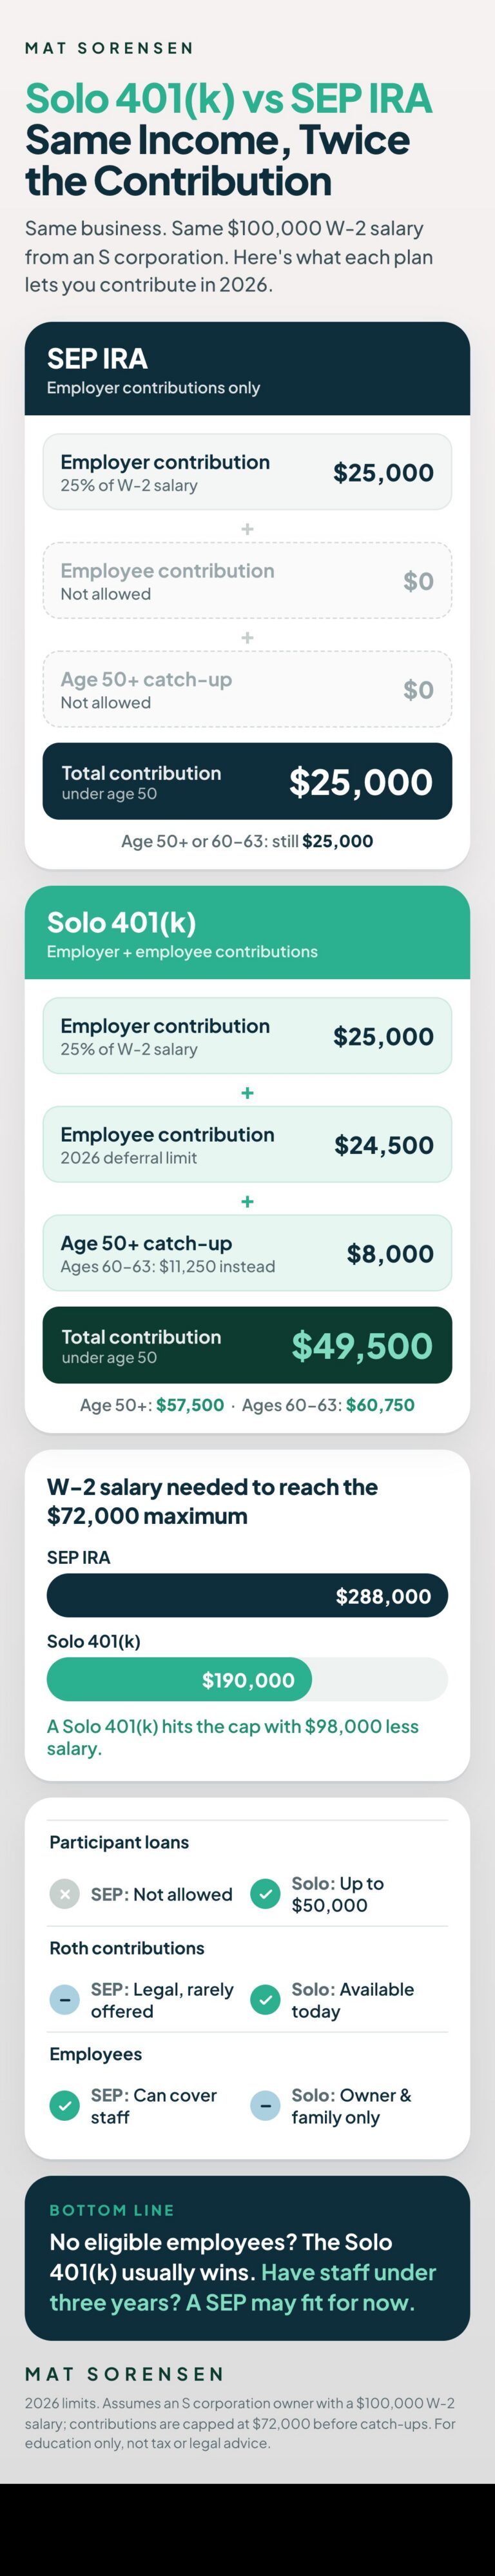
Infographic: Solo 401(k) vs SEP IRA on the same $100,000 W-2 salary

Why the Solo 401(k) Wins: You Can Contribute More on Less Income

The Solo 401(k) lets you contribute significantly more than a SEP IRA at the same income level—thanks to its dual-contribution structure.

Both plans share a $72,000 annual limit (2026), but the paths to that cap differ sharply:

  • SEP IRA: Only employer contributions are allowed—capped at 25% of W-2 wages for an S corporation owner, or roughly 20% of net self-employment earnings for a sole proprietor.
  • Solo 401(k): An employer contribution (25% of W-2) plus an employee contribution of up to $24,500 in 2026, with catch-up contributions on top for owners 50 and older.
2026 Contributions on the Same W-2 Salary
SEP IRA Solo 401(k)
$100,000 W-2 $25,000 $49,500
$100,000 W-2, age 50+ $25,000 $57,500
$100,000 W-2, ages 60–63 $25,000 $60,750
$200,000 W-2 $50,000 $72,000 (max)
Solo 401(k) = 25% employer contribution + $24,500 employee deferral, capped at $72,000. Catch-ups ($8,000 at 50+, or $11,250 at ages 60–63) are added on top of the cap.

S corporation owners benefit most. Since contributions are based solely on W-2 wages (not K-1 distributions), minimizing W-2 to save on payroll taxes severely limits SEP IRA contributions—but barely dents Solo 401(k) capacity.

Example: $200K Total Income ($80K W-2 + $120K K-1)
SEP IRA Solo 401(k)
Employer contribution (25% × $80,000) $20,000 $20,000
Employee contribution Not allowed $24,500
Total contribution $20,000 $44,500
The Solo 401(k) allows more than double the contribution on the same salary.
W-2 Salary Needed to Reach the $72,000 Maximum
SEP IRA Solo 401(k)
How the math works $72,000 ÷ 25% ($72,000 − $24,500) ÷ 25%
W-2 salary required ~$288,000 ~$190,000

Both the SEP IRA and Solo 401(k) top out at $72,000—but you reach that limit far sooner, and with significantly less income, using a Solo 401(k).

The $50,000 Escape Hatch (Participant Loan)

The Solo 401(k) has a major advantage over the SEP IRA: it can allow participant loans. In practical terms, you may borrow from your own account—up to $50,000—without triggering income tax or an early-withdrawal penalty. SEP IRAs do not offer this flexibility. Borrowing from a SEP IRA is prohibited and can create serious tax consequences.

A Solo 401(k) loan can provide liquidity when you need it most. You can use the proceeds to pay off high-interest debt, cover medical expenses, help fund a child’s education, make a home down payment, start a business, or meet another personal need. No hardship exception or special purpose is required.

The maximum loan is the lesser of $50,000 or 50% of your vested Solo 401(k) balance. For example, if your account balance is $60,000, the maximum available loan is $30,000—not $50,000. The loan must generally be repaid within five years, with payments made at a reasonable interest rate—often prime plus 2%. If prime is 5.25%, for example, the loan rate would be 7.25%. That interest is paid back into your own retirement account.

Solo 401(k) Loan at a Glance
Example
Maximum loan Lesser of $50,000 or 50% of your vested balance
$60,000 account balance Up to $30,000
$100,000+ account balance Up to $50,000
Repayment term Generally within 5 years
Interest rate Often prime + 2%, paid back into your own account

This structure gives business owners an important safety valve: you can maximize retirement contributions while retaining access to capital if an unexpected need arises. With a SEP IRA, accessing funds before age 59½ generally means a taxable distribution and potentially a 10% early-withdrawal penalty. A properly administered Solo 401(k) loan avoids both.

Additionally, a Solo 401(k) can also be self-directed, giving you the ability to invest beyond the standard menu of mutual funds and index funds. Depending on plan documents and applicable rules, it may hold assets such as rental real estate, private funds, private companies, and cryptocurrency—investments you understand and believe in.

FREE BEGINNER’S GUIDE

Get a step-by-step overview of Solo 401(k) contribution rules, setup, deadlines, loans, and self-directed investing.

Get the Free Solo 401(k) Beginner’s Guide

The Roth Option

The third major advantage of a Solo 401(k) is Roth capability. If your plan document permits it, you can make Roth Solo 401(k) contributions today, pay tax on the money now, and potentially withdraw the contributions and decades of investment growth tax-free in retirement.

A SEP IRA is a different story. In legislation known as SECURE 2.0, Congress made Roth SEP contributions legal, and the IRS now recognizes that SEP contributions may be made to Roth SEP IRAs. But availability remains limited in practice because the IRS has yet to release updated model form documents for Roth SEP IRAs. Many custodians, including Directed IRA, are waiting for those model documents before establishing customers’ Roth SEP IRAs.

Roth contributions do not produce an upfront tax deduction. You pay tax on the income before contributing it to the Roth Solo 401(k). In exchange, qualified distributions in retirement, generally after age 59½, can be entirely tax-free.

That trade-off can be compelling for investors who expect their tax rate to be higher later, value certainty around future taxes, or are focused on long-term compounding. Rather than taking a deduction today and paying taxes when funds come out, you pay tax once on the contribution and allow the account to grow without another tax bill at retirement.

Key takeaway: For Roth-focused savers, this feature alone can make the Solo 401(k) the more practical choice. A Roth SEP may be authorized by law, but a Roth Solo 401(k) is generally the account you can actually establish and use today.

Two More Advantages for Self-Directed Investors

You can be your own trustee. Every IRA, including a SEP IRA, must have a third-party custodian such as a bank, credit union, or trust company. With a Solo 401(k), you can serve as the trustee yourself and control the plan’s bank and brokerage accounts directly. That checkbook control is valuable when you invest in real estate, notes, or private companies, because you can sign off on investments without waiting on a third party to process your own funds.

No UDFI tax on leveraged real estate. When a SEP IRA buys real estate with a loan, it owes a tax on unrelated debt-financed income (UDFI). For example, if your SEP IRA buys a $100,000 rental with $40,000 of its own cash and a $60,000 loan, the IRS taxes roughly 60% of the property’s net income, and the IRA has to file a separate Form 990-T. Congress created an exemption for Solo 401(k)s, so this tax on leveraged real estate doesn’t apply to them. If you plan to use debt in your deals, the Solo 401(k) is the better fit.

The trade-offs. A Solo 401(k) requires an IRS-compliant plan document, so it costs more to set up than a SEP IRA. And once the plan holds more than $250,000 in assets, you’ll need to file Form 5500-EZ with the IRS each year. The return isn’t overly complex, but it’s an annual filing you’ll need to handle or hire out.

The One Exception: When the SEP Actually Wins

There is one common situation where a SEP IRA may be more practical than a Solo 401(k): you have employees.

A Solo 401(k)—also known as a one-participant 401(k)—is designed for a business owner with no eligible non-owner employees. It can generally cover the owner, the owner’s spouse, and children who work in the business; each may participate under the plan’s eligibility rules and have their own Solo 401(k) account within the same plan. However, once you have an eligible non-owner full-time employee who has worked for you for more than one year, the business is no longer a straightforward fit for a Solo 401(k).

SECURE 2.0 adds another consideration: certain long-term, part-time employees must be allowed to make elective deferrals after working at least 500 hours in two consecutive 12-month periods, subject to the applicable age and plan rules. That means part-time help can create 401(k) eligibility issues sooner than many owners expect.

The Solo 401(k) is meant for the business owner, their spouse, and their family. It is not intended for a company that has other full-time or part-time employees.

A SEP IRA offers more runway. Under the maximum permitted eligibility requirements, employees generally must be included only after they have:

  • 1Reached age 21
  • 2Worked for the business in at least three of the prior five years
  • 3Earned at least the applicable minimum compensation for the year

Importantly, a “year of service” can count even if the employee worked only briefly. A seasonal employee who works one summer can still accumulate one of the three required years.

EXAMPLE: THE SEP WINDOW

Suppose you are a real estate agent who hires a full-time assistant. After two years, a Solo 401(k) is no longer the straightforward solution because you have a non-owner employee. But that employee may not yet be eligible for a SEP IRA under the three-out-of-five-years rule.

That creates a useful planning window: you can establish a SEP IRA, make your annual employer contribution, and delay the point at which you must also fund contributions for the employee. Once the employee satisfies the SEP’s eligibility requirements, however, the business must generally make the same percentage contribution for that employee as it makes for the owner.

The practical takeaway: If you have no eligible employees—only independent contractors paid on Form 1099—a Solo 401(k) is usually the stronger choice. If you have employees and are in the gap between one and three years of service, a SEP IRA can be the better short-term retirement-plan option.

What That $50,000 a Year Actually Becomes

The contribution gap between a SEP IRA and a Solo 401(k) may look like a $24,500 annual difference. Over time, it can become a multimillion-dollar decision.

Assume you contribute $50,000 per year to a Solo 401(k) and earn a hypothetical 10% annual return. That is roughly in line with the S&P 500’s long-term historical average, though actual returns vary and are never guaranteed.

$50,000 a Year at a Hypothetical 10% Return
After 10 years~$800,000
After 20 years~$2.9 million
After 30 years~$8.2 million
Illustration only. Assumes $50,000 contributed at the end of each year, a constant 10% annual return, and no fees, taxes, or changes in contribution limits. Investment returns are not guaranteed, and the S&P 500’s historical performance does not predict future results.

If those contributions go into a Roth Solo 401(k), qualified distributions in retirement can be entirely tax-free. That means the value shown after 10, 20, or 30 years is not merely an account balance—it can be tax-free retirement income.

This is why the account decision matters. A Solo 401(k) does not simply give you more room to contribute this year; it gives more capital time to compound. For an owner able to put away $50,000 annually—even on a $100,000 W-2—the difference between a SEP IRA and a Solo 401(k) can grow from thousands of dollars today to millions of dollars by retirement.

What This All Comes Down To

The SEP IRA was built for an earlier era of self-employment. For most business owners with no eligible employees, the Solo 401(k) is the more powerful modern tool: it lets you contribute more on less income, access liquidity through a participant loan when needed, and use a practical Roth option to build tax-free retirement wealth.

The advantage is not subtle. A Solo 401(k) combines higher contribution capacity, greater flexibility, and Roth planning in one account. Yet many business owners never compare the numbers—they simply open whichever account their bank or broker makes easiest to access. That can mean leaving substantial retirement savings and tax-planning opportunities on the table.

Ready to explore a Solo 401(k) or self-directed IRA? My team at Directed IRA administers thousands of self-directed retirement accounts and can help you evaluate your options. Book a complimentary 15-minute call to get started and discuss which options may be best for you.

FREE 15-MINUTE CALL

Find out whether a Solo 401(k) or SEP IRA fits your income, entity, and employees.

Book a Call with Directed IRA

Crypto Tax Strategies in 2026: Pay Less, Keep More

Crypto is back. With Bitcoin and major altcoins up 20–30% in 2026, gains mean taxes—and the IRS is watching. You must report crypto activity on your federal return (Form 1040), answering the digital asset question before you even list your income. The good news: legal, proven strategies can significantly reduce your tax bill. Below are five high-impact strategies you may want to consider.

Infographic: how crypto gains are taxed and five strategies to reduce crypto taxes in 2026

How Crypto Gains and Losses Are Taxed

Every crypto-to-crypto trade (e.g., BTC → XRP), sale, or spend is a taxable event.

  • ✓Held ≤12 months: Short-term capital gain/loss, taxed at ordinary income rates (up to 37%)
  • ✓Held >12 months: Long-term capital gain/loss, taxed at 0%, 15%, or 20% depending on total taxable income

Most investors should seek to avoid short-term capital gains, as they are generally taxed at significantly higher rates than long-term capital gains. The primary exception is when those gains can be offset with short-term capital losses—a strategy we will discuss later.

It is also important to note that most investors will never reach the 20% long-term capital gains bracket. In 2026, the 20% rate generally applies only when taxable income exceeds $613,700 for married couples filing jointly, $545,500 for single filers, or $579,600 for heads of household. See the table below for reference.

Many investors instead fall within the 0% or 15% long-term capital gains brackets, creating valuable opportunities for proactive tax planning.

2026 long-term capital gains tax brackets

The 0% Capital Gains Bracket (2026 Thresholds)

Long-term capital gains tax depends on total taxable income (after deductions). For 2026, the 0% bracket typically extends up to:

  • ✓Married Filing Jointly: $98,900
  • ✓Single: $49,450
  • ✓Head of Household: $66,200

EXAMPLE

Example: A married couple with $120,000 gross income and a $32,200 standard deduction has $87,800 taxable income. They can realize up to ~$11,100 in long-term crypto gains and still pay 0% federal tax on those gains.

Tactical tip: If you’re near a bracket threshold, stage sales across years to stay in the 0% or 15% zone—avoiding a jump to 20%.

Strategy 1: Crypto Tax-Gain Harvesting

Don’t wait for losses to act. Proactively realize gains up to the top of your current bracket (0% or 15%). This reduces future taxable gains when you eventually sell—all while staying in a lower tax tier today.

EXAMPLE

Example: If you’re close to a tax-bracket threshold, consider selling just enough crypto to realize gains while remaining in the lower bracket. This allows you to lock in gains at a lower tax rate today rather than potentially paying a higher rate in the future. If your objective is a long hold, you may repurchase the asset shortly after the sale. 

Best for: Investors in the 0% or 15% long-term brackets who expect higher income (or rates) later.

Strategy 2: Tax-Loss Harvesting (No Wash-Sale Rule for Crypto)

When crypto dips, sell to lock in losses—then immediately rebuy the same asset. Unlike stocks, the wash-sale rule does not apply to crypto under current IRS guidance, so you can maintain market exposure while harvesting losses to offset other gains.

EXAMPLE

Example: Buy BTC at $90K, it drops to $60K. Sell to realize a $30K loss, rebuy at $60K. Use that loss to offset $30K in gains elsewhere, deferring or eliminating tax.

$90K

buy price

$60K

sale and rebuy price

$30K

realized loss

Note: Legislation has been proposed to extend wash-sale rules to crypto, but as of 2026, it remains inapplicable.

Strategy 3: Hold & Trade Crypto in a Roth IRA (or Other Tax-Advantaged Accounts)

A crypto Roth IRA lets you buy, trade, and grow digital assets tax-free—no capital gains, no short-term rates, and qualified withdrawals in retirement are 100% tax-free.

  • ✓Works with BTC, ETH, SOL, XRP, and more (via self-directed IRA custodians, such as Directed IRA)
  • ✓Ideal for long-term believers who won’t need the funds before age 59½ 
  • ✓Additional tax advantage accounts include kids Roth IRA (with earned income), Coverdell ESAs (education), and HSAs (healthcare)—all holding crypto as the underlying asset

Each account offers powerful tools to strengthen your tax-planning strategy. For guidance on tax-advantaged accounts—and help choosing and opening the right one—contact my team at Directed IRA to discuss an option tailored to your goals. 

Note: Contributions require earned income and stay within annual IRA limits ($7,500 in 2026, or $8,600 if 50+)

Strategy 4: Borrow Against Crypto—Don’t Sell

Need liquidity? Take a loan secured by your crypto holdings instead of selling. Debt isn’t taxable income, and you can defer capital gains indefinitely while accessing cash flow.

  • ✓Interest rates have improved as more lenders enter the crypto-collateral space, however, interest rates can still be volatile 
  • ✓The asset’s appreciation should outpace the interest accruing on the loan
  • ✓Risk-aware investors monitor loan-to-value (LTV) ratios to avoid forced liquidations in downturns

Use case: Fund living expenses, real estate, or new investments—without triggering a tax event.

Strategy 5: Charitable Remainder Trust (CRT) for $1M+ Gains

For ultra-high-net-worth investors, a Charitable Remainder Trust offers triple benefits:

  • ✓Immediate charitable deduction on your taxes (e.g., donate $1M in appreciated BTC)
  • ✓Tax-free sale of crypto inside the trust (no capital gains)
  • ✓Lifetime income stream (up to 20 years or life expectancy) paid to you

At your death, any assets remaining in the trust pass to charity rather than directly to your heirs. However, the trust may be structured to purchase a life insurance policy on your life, with the policy proceeds potentially passing to your children on a tax-advantaged basis.

This strategy is highly complex, and this article provides only a simplified overview. For guidance on whether it is appropriate for your situation—and how to structure and implement it to support your estate-planning goals—schedule a consultation with my law firm, KKOS Lawyers.

Best for: Ultra-high-net-worth investors seeking to combine estate planning, lifetime income, charitable giving, and tax-efficient planning for substantial crypto gains.

Quick Recap: 5 Ways to Slash Crypto Taxes in 2026

  1. 1Harvest gains strategically to maximize 0%/15% brackets
  2. 2Harvest losses freely by selling to lock in losses then immediately rebuying the asset
  3. 3Go tax-free with Roth IRAs, HSAs, or Coverdells holding crypto
  4. 4Borrow, don’t sell to access value without triggering gains
  5. 5Use a CRT for seven-figure gains: deduction + tax-free growth + income + legacy planning

Taxes are unavoidable—but overpaying isn’t. 

Download the FREE CRYPTO BEGINNER’S GUIDE and learn how a Roth IRA, traditional IRA, or HSA can buy and sell cryptocurrency tax-free! Buying Crypto in an IRA (Beginner’s Guide) 

Book a free call with my law firm KKOS Lawyers to learn how we can analyze 30 other tax strategies like this to help you pay less in taxes. Meet with Client Advisor 

Put your retirement dollars into the assets you actually believe in — BOOK A FREE CALL with DirectedIRA and set up a crypto Roth IRA today! Book a Call | Self-Directed Account Specialists 

FREE CRYPTO IRA GUIDE

Learn how to buy and hold cryptocurrency in a self-directed IRA.

Get the Free Crypto IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

What Happens If You Don’t Have a Will?

You will die someday, and when that happens, everything you own will go to someone else. If you do not have a will, a court—not your family and not your stated wishes—will decide who receives your property based on your state law. This article walks you step by step through creating a simple, legally valid will. It is not a full estate plan, but if you currently have nothing in place, it is the fastest way to document your wishes so they are followed. 

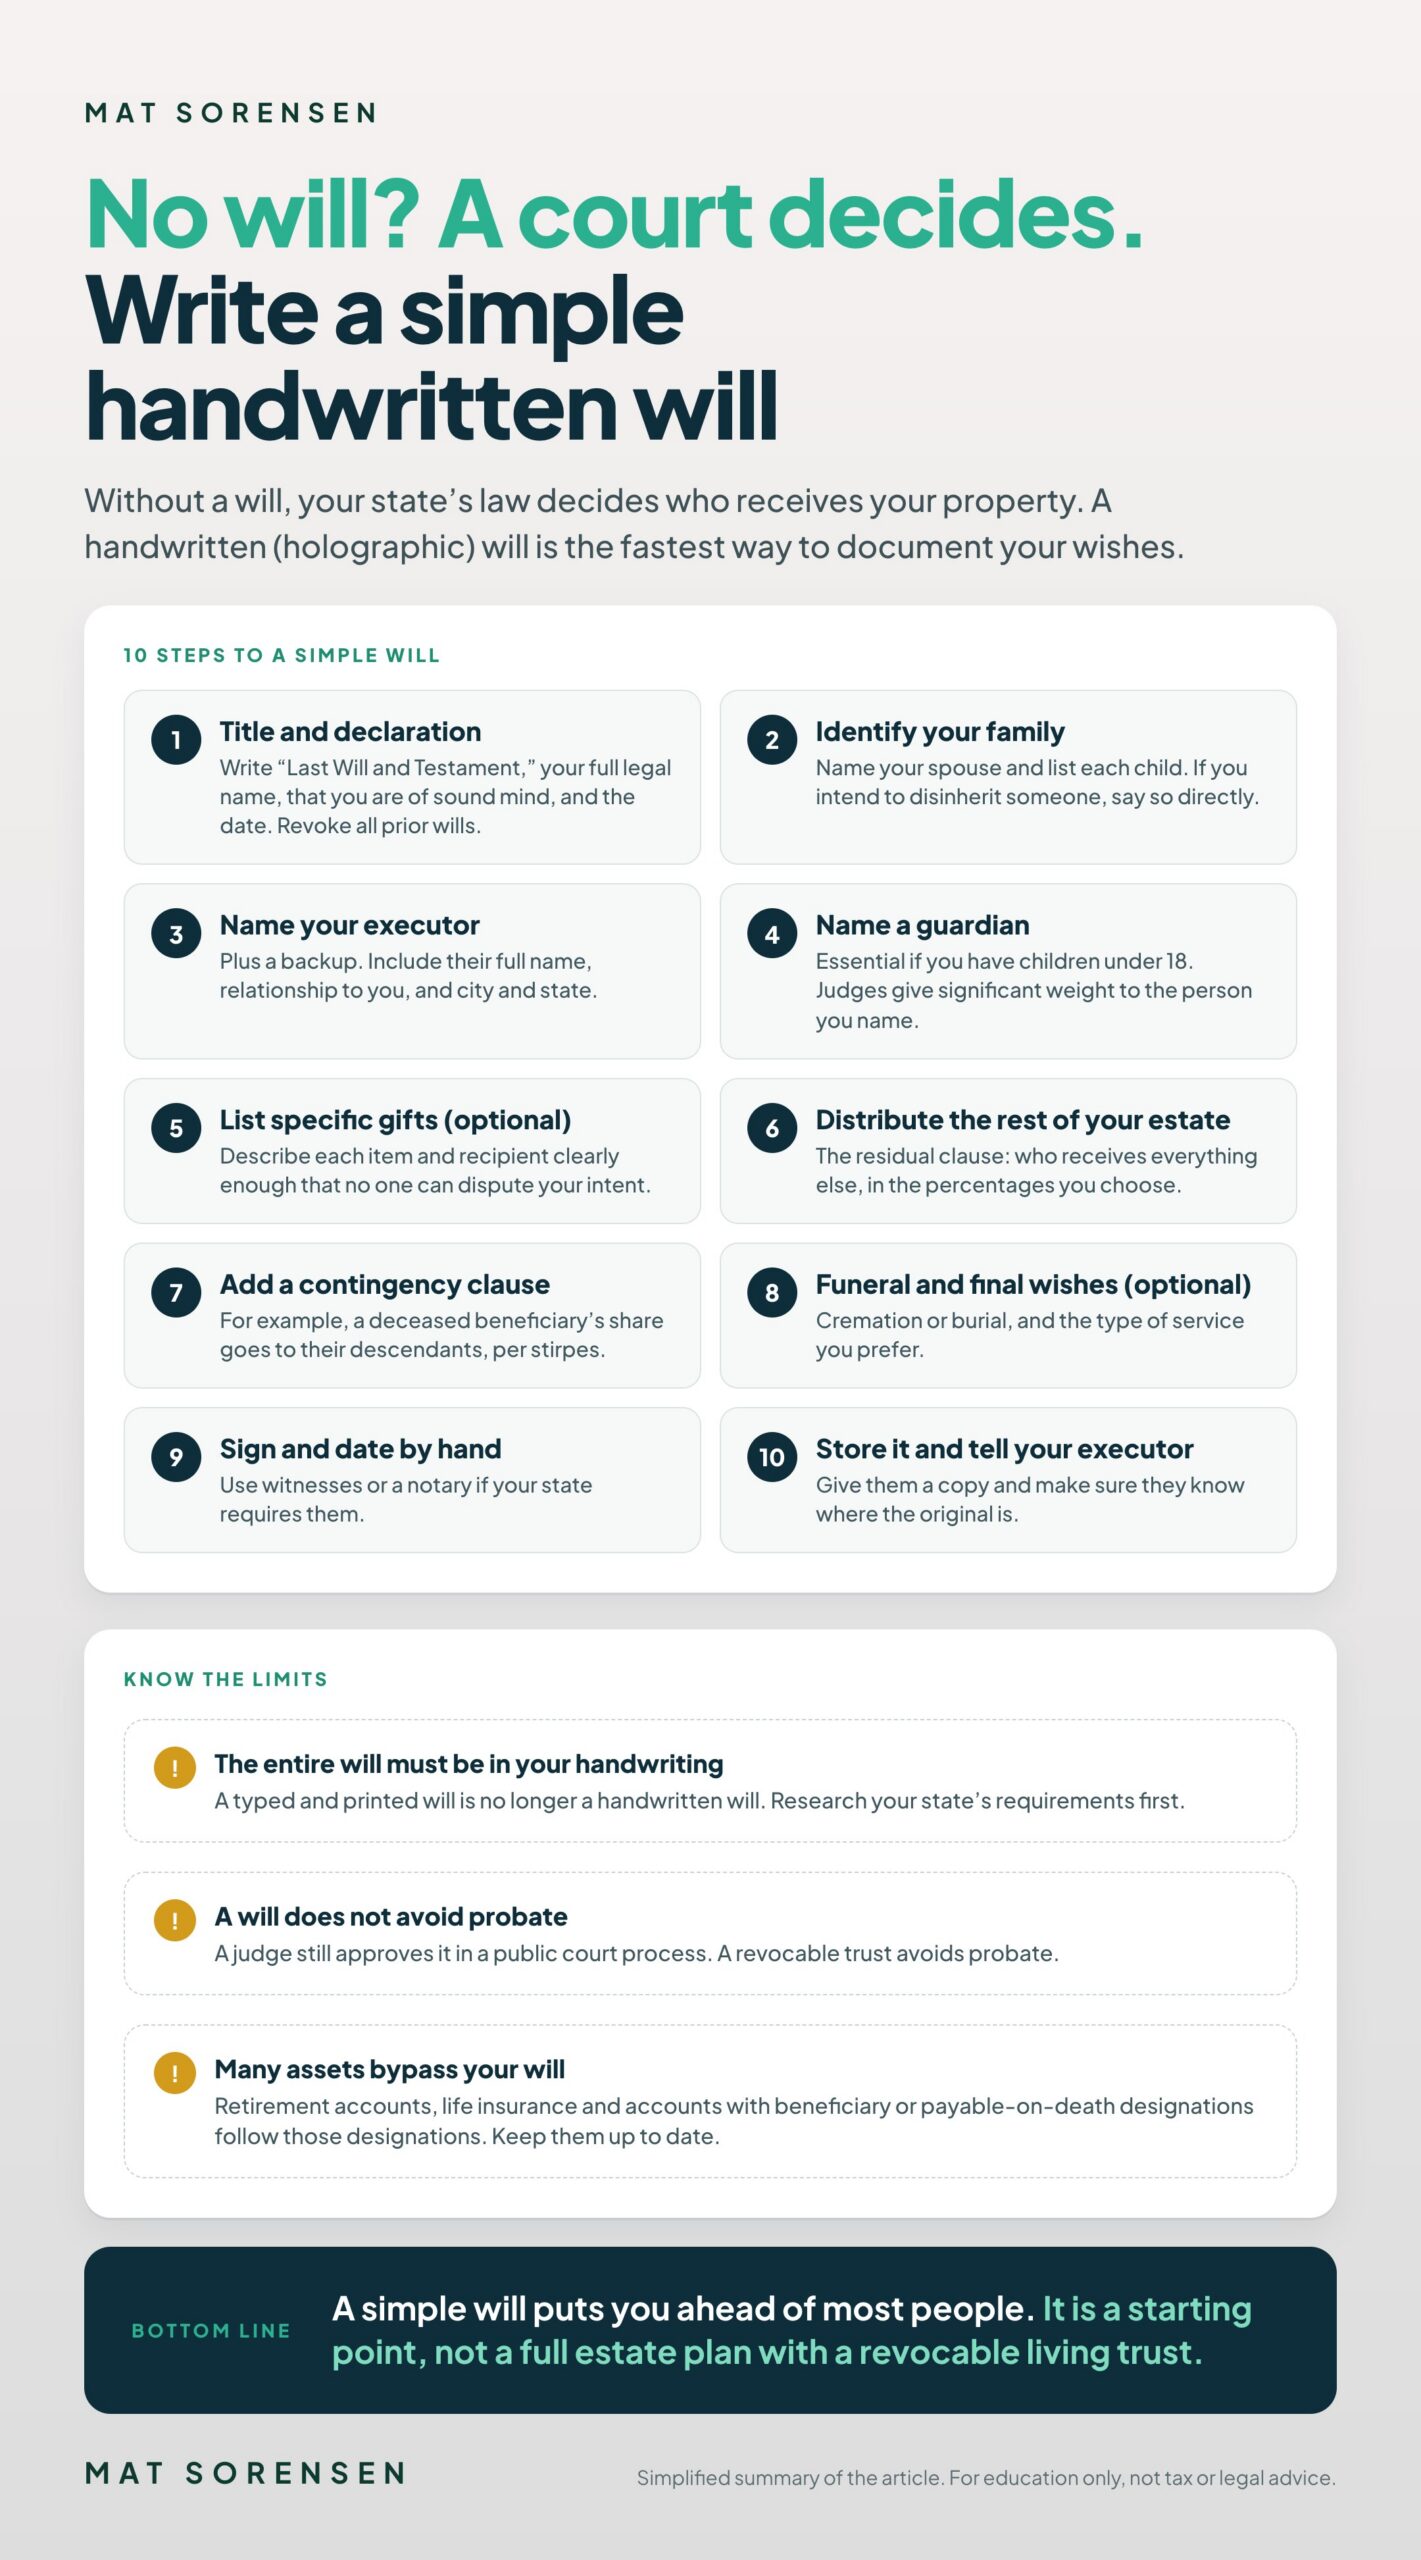
Infographic: 10 steps to write a simple handwritten will, and the limits of a will

What We’re Creating: A Simple Handwritten Will

We are creating a simple handwritten will, also known as a holographic will. This document must be handwritten and signed by you; in many states, those requirements make it legally valid and enforceable. Do not type and print this will, because it will no longer constitute a handwritten / holographic will. If you want to use this simple approach, the entire will must be in your handwriting.

CHECK YOUR STATE

Each state has unique laws regarding handwritten wills, and the laws of the state where you reside will apply to you. Many of these states do not require witnesses or other formalities, but each state is different, so you should research your state’s requirements before writing your handwritten will.

Step 1: Start With the Title and Declaration

First, write ‘Last Will and Testament’ at the top of the page. Next, include your full legal name, a statement that you are of sound mind, and the date. For example, I might write: ‘I, Mat Sorensen, being of sound mind, declare this to be my last will and testament. I revoke all prior wills and codicils.’ This language makes it clear that this document controls and cancels any earlier wills or similar documents.

Step 2: Identify Your Family

Next, you need to identify your family. Clearly state whether you are married and, if so, name your spouse. State whether you have children, and if you do, list each child in the will. This helps anyone reading the will understand whether someone was intentionally left out or simply omitted by mistake. For example, if you have three children but only list two and do not clearly disinherit the third, a court might decide to divide your estate among all three. To avoid confusion, list each child and, if you intend to disinherit someone, state that directly. Keep this section simple and factual by stating your relationships and names without extra language like ‘my favorite’ or ‘my first-born.’

Step 3: Name Your Executor

In this step, you will need to name an executor. This is one of the most important decisions in your will, because the executor handles your estate, pays any debts or taxes, and has the authority to distribute your assets.

EXAMPLE

In your handwritten will, write something like: ‘I designate [Full Name] as executor of my estate.’

In many cases, people choose a spouse or one of their children, often someone who is responsible, good with money, and able to handle the emotional and financial duties involved. You may also want to name a backup executor in case your first choice has died or is unable to serve. When listing your executor, include their full name, their relationship to you, and the city and state where they live.

Step 4: Name Your Guardian

If you have any children under 18, naming a guardian is essential. This can be one of the most critical sections of your will, because you are choosing who would raise your children if you pass away. You may feel that your parents are the best choice, but that may not be ideal if they would rather be grandparents than take on the full responsibility of parenting again. You might instead consider a sibling with children of similar ages, or a close friend or cousin you trust and who shares your values.

Note that the person you name is not automatically guaranteed to become the guardian. A court will ultimately decide who serves, based on who steps forward and what is in the best interests of your children, but judges give significant weight to the person you name in your will. If you do not list anyone, the court will decide without your guidance, which can lead to conflict within your family at a time when they are already grieving. Your family will want direction from you, so clearly list who you would want to serve as guardian for your children.

Step 5: List Specific Gifts (Optional But Helpful)

If there are particular items you want to leave to specific people, you should list them clearly. For example, you might leave a piece of jewelry to your daughter, a shared boat to your brother, or a business interest to your business partner. When you do this, be specific so there is no confusion about what goes to whom, such as: ‘I leave my electric guitar to [Full Name] in [City, State].’ The goal is to describe each item and recipient clearly enough that no one can reasonably dispute your intent. Do not overthink this section; if it slows you down, you can skip it for now and add or adjust specific gifts later. The purpose of this handwritten will is speed and clarity so you can get something in place, knowing you can always revise it in the future.

Step 6: Distribute the Rest of Your Estate

This section explains who receives the rest of your estate. It is the core distribution section of your will and is often called the ‘residual’ clause, because it covers everything that has not been specifically given away earlier. After any specific gifts you list, this clause directs all remaining assets to the people you choose in the percentages you select.

If you are married, you may want your spouse to receive everything that is left. You could say, ‘If I pass away, my surviving spouse receives the entirety of my residual estate.’ If your spouse has already died, or if you are single, you can then direct your remaining estate to your children or other beneficiaries in whatever percentages you decide.

When naming your children—whether they inherit if your spouse is not living or you are single and they are your primary beneficiaries—you should specify their shares as percentages. For example, if you have two children, you might have each inherit 50% of your estate, or you might choose a different split such as 10% for one child and 90% for the other. It is your wealth and legacy, and you decide how it is divided.

When writing this clause, you might say something like, ‘I leave the remainder of my estate to my children, to be split evenly, 50% to each.’ The key is to make it crystal clear who gets what. A simple handwritten will will not cover every possible contingency, such as what happens if a child dies before you or whether that child’s share should pass to their own children. Those details are usually addressed in an estate plan which is more comprehensive. 

Step 7: Add A Contingency Clause

If you want to add more detail about contingent beneficiaries, you can do that in this section. A common approach is to say something like, ‘If any of my beneficiaries listed above are deceased at the time of my death, I want their share to go to their descendants, per stirpes.’ This means that if you have four children who each receive 25% of your estate and one child dies before you, that child’s 25% share would go to that child’s heirs rather than being split among the surviving siblings. You may prefer a different approach, but using a per stirpes designation is a simple and widely used way to make sure a deceased beneficiary’s share passes down their family line.

Step 8: Funeral and Final Wishes (Optional)

Now you will state your funeral and final wishes. Indicate whether you prefer cremation or burial and note any preferences for the type of service, such as military or religious. You can also include any special requests that matter to you. This section is optional, and if you are trying to complete this handwritten will quickly, you can keep it very brief or skip it entirely as it is optional.

Step 9: Sign and Date Properly

This step makes this document official. You must physically sign and date your written will by hand. If your state requires witnesses or a notary, ensure they observe your signature and signing date. Not every state requires witnesses or a notary, so research your specific state’s requirements to ensure your written will is valid. In most states, your signature alone is sufficient.

Step 10: Store It and Tell Your Executor

Finally, you need to store your will safely and tell someone you trust about it and its location, because if no one knows it exists or where to find it, your executor and family cannot use it after you pass away. Make sure your executor knows they are named and understands their role, give them a copy of the will so they are familiar with your wishes, and clearly tell them where the original is stored. Your executor will need to file the original will with the probate court, so they must know exactly where it is and how to access it; do not hide it where it could be lost or overlooked.

Important Reality Check: A Will Does Not Avoid Probate

It is important to note that a will does not avoid probate—this is a common misunderstanding. With a will, you specify who receives your assets after you pass away, but the document still must go through a public court process where a judge approves it. This differs from a revocable trust, which avoids probate entirely. 

Many assets pass outside of your will anyway, such as retirement accounts, life insurance, bank accounts, or investment accounts with payable-on-death or beneficiary designations. Each has their own beneficiary designations—not within your will—which control who receives them, so make sure they are up to date. If you want to avoid probate altogether and include more detailed rules or contingencies, consider a trust-based estate plan, such as a revocable living trust.

If You Followed These Steps, You Now Have a Legally Valid Will

You now have a simple will in place that puts you ahead of most people. However, this is just a starting point, not the end. If you have substantial assets, real estate, a blended family, retirement accounts, or life insurance—and you want to avoid probate—you should consider getting a full estate plan with a revocable living trust done. 

If you want help getting this done, my law firm, KKOS Lawyers works with clients across the country, and you can book a call using the link below. We can go over the benefits of a full estate plan, the revocable living trust, power of attorney, and all the documents that help you leave your legacy behind.

Contact Us – KKOS Lawyers

The End of Real Estate LLC Privacy? New Rule Explained

The federal government is tightening its grip on real estate ownership disclosure — and if you plan to hold property in an LLC, your privacy may need to disclose the ownership and make filing to the federal government. Starting March 1, 2026, a new federal rule requires disclosure of who actually owns certain real estate in LLCs, giving regulators deeper visibility into ownership structures that many investors rely on for privacy and asset protection. Under this law, you must file a report with the federal government in any of the following situations:

  • ✓You transfer residential real estate from your personal name into your own LLC (or an LLC owned by anyone else).
  • ✓You purchase residential real estate in your LLC using cash and no licensed bank lender is involved.
  • ✓You acquire residential real estate using creative financing (such as seller-financed or “subject-to” transaction where no traditional bank mortgage is involved) and the property is held in your LLC.

If any of these situations apply to you, you are required to file this new report for each property that is transferred to or acquired in an LLC. 

UPDATE (NOV 2026)

On March 19, 2026, a federal court in Texas (Flowers Title Companies v. Bessent) vacated this rule. FinCEN says that while that order is in force, no one has to file Real Estate Reports and there is no penalty for not filing. FinCEN has appealed, so the rule could come back if the decision is reversed. (Source: FinCEN, via Holland & Knight)

Infographic: when the FinCEN residential real estate report applies to LLCs, who files it, what it discloses, and key exemptions

What Is This Law Trying to Do?

This new requirement is a FinCEN rule issued under the Bank Secrecy Act and is, frankly, a nuisance for ordinary real estate owners and investors. It is separate from the Corporate Transparency Act, the law Congress passed a few years ago that created beneficial ownership information (BOI) reporting for LLCs and corporations. While BOI reporting for many LLCs and corporations is no longer required as a result of treasury guidance saying it doesn’t apply to U.S. citizen owners, this real estate reporting rule for LLCs was not part of that change (but see the update above). Its stated purpose is to fight money laundering by making it clearer who actually owns and controls LLCs that hold real estate.

When Does This Law Apply?

Three criteria must be met for this law to apply. 

  1. 1The property must be residential real estate. This includes a single-family home, condo, duplex, fourplex, or land intended to be developed for residential use. Commercial properties or apartment buildings with five or more units do not qualify.
  2. 2The purchase must be made in your LLC without using a bank or mortgage lender. When banks or mortgage lenders are involved, they run your information through FinCEN (the Financial Crimes Enforcement Network), which satisfies the federal reporting requirement. However, if the property is purchased with cash, through seller-financed or “subject-to” arrangements, or with other forms of creative financing, there is no federal reporting in place—triggering the need for this disclosure report.
  3. 3The transaction must involve a transfer to an entity, such as an LLC or corporation. For example, if you buy real estate in your own name and then transfer it to an LLC, this new report would be required.

If all three criteria are met, you must file this residential real estate report with FinCEN online at fincen.gov.

Exemptions to the Residential Real Estate Rule

 Using a trust to purchase or hold residential real estate can qualify for an exemption from the residential real estate reporting rule. If you establish a trust (as the settlor or grantor) and transfer property from your personal name into that trust, that transfer is exempt and no real estate report is required under this rule. This exemption was primarily created to negate the requirement of individuals transferring property they own to a trust they have set-up for themselves and their family. 

Some clients have asked whether they can buy residential real estate in a trust that is owned by an LLC (LLC is beneficiary to trust) to maintain privacy and avoid filing this new report. The idea is that, even though the LLC is the beneficiary, they hope the trust exemption will still protect them. At this time, there is limited guidance on this approach because the rule is new and FinCEN has not clearly addressed this specific structure. That said, if your primary goals are privacy with the federal government and potentially avoiding the reporting requirement, there may be strategies involving additional trusts and structuring options that leverage the trust exemption, though they typically come with added complexity and cost. Keep in mind though, much like your personal tax return, the federal real estate report that is filed is not available publicly and is not searchable by the public or available under a freedom of information act request. 

Who Has to File This Report?

The person responsible for filing the residential real estate report is determined by a reporting “cascade.” In simple terms, if a title or escrow company is involved in the transaction, that company is required to file the report. If no title or escrow company is involved, the responsibility shifts to the person or firm that prepares the deed.

At my law firm KKOS Lawyers, we prepare hundreds of deeds each month, transferring properties from our clients’ personal names into LLCs or trusts. When we prepare your deed, we also handle this real estate report on your behalf. If you are working with another law firm or service provider, you should expect them to prepare and file the report whenever they are transferring property into an LLC and the rule is triggered. If you prepare the deed yourself and do not use a title or escrow company then you are the one responsible for filing the report with FinCEN.

Why Is There Controversy Surrounding This New Report?

The real estate report requires you to disclose anyone who owns 25% or more of the LLC, as well as anyone who exercises control over the LLC, such as the manager. In other words, every individual with at least 25% ownership or significant decision-making authority must be reported to the federal government. Many clients prefer not to disclose ownership information to the government, the state, or in any public record because they value privacy. However, under this rule, you are required to report all individuals who meet the 25% ownership threshold or who have control of the LLC.

How to Fill Out the New Form, Step by Step!

You can find the Real Estate Report form that must be filed with FinCEN here: RER Form

Screenshot of the FinCEN Real Estate Report form

In the first section, enter the name of the filer or the name of the trust, and select the appropriate filing type. The preparation date will be filled in automatically.

Screenshot of the FinCEN Real Estate Report form

In Part I, you will first identify who is filing and completing the report. For example, if we at KKOS Lawyers were preparing it on your behalf, we would select ‘Deed Instrument Filer’ and enter our firm’s name.

Screenshot of the FinCEN Real Estate Report form

In Part II, you will provide the property information. Enter the street address and the full legal description of the property, which you can find on your property deed.

Screenshot of the FinCEN Real Estate Report form

In Part III, you will identify who is receiving the property. Start by completing the transferee section with your LLC’s information, then list all individuals who own 25% or more of the LLC.

If you are transferring property from your personal name into an LLC for real estate investing, and no money is actually changing hands, you can indicate that no consideration was paid. Next, enter the LLC’s legal name, address, and EIN. This section is focused on the entity that will own the property.

When you reach ‘Person(s) associated with the transferee,’ you must list everyone who owns at least 25% of the LLC, as well as anyone with significant decision-making authority. If you are completing the form for your own LLC, you would list yourself as a beneficial owner, indicate your citizenship, and provide your personal information. Unlike the BOI reports that never went into effect, this form does not require you to upload a copy of your government ID. If there is more than one beneficial owner or decision-maker, use the ‘+’ button to add each additional person and include all of their required details.

Screenshot of the FinCEN Real Estate Report form

In Part IV, you will identify who is transferring (deeding) the property to the LLC. If you are moving property from your personal name into your LLC, enter your own information here. If the property is being received through any other method, list the details of the transferor accordingly.

Screenshot of the FinCEN Real Estate Report form

In Part V, you will detail any payment information involved in the transaction. This includes the amount paid, the banks used, and the account numbers where the funds were transferred. For most clients transferring property from their personal name to their own LLC for asset protection—with no money changing hands—you can simply select ‘No Consideration Paid’ and skip the rest of this section.

The core requirements of this report are straightforward: disclosing the LLC’s owners, identifying the property, and specifying the transferor. That’s the key information being filed with the federal government.

Frequently Asked Questions

1. What if I’ve already transferred properties to my LLC before March 1, 2026? Do I need to file retroactively?

No, this rule only applies to deed transfers and purchases occurring on or after March 1, 2026.

2. Where is this information stored, and can the public access it?

The report contains private information, similar to your tax return. It is not publicly searchable, and even under the Freedom of Information Act, no one can request it from FinCEN. If other government agencies were to request it, they would have to obtain a subpoena first.

3. Do self-directed IRA owners need to file if purchasing residential real estate through an IRA or IRA LLC?

If you acquire property directly in your IRA or through a custodial arrangement, no report is required. However, if an IRA LLC (or an LLC owned by your IRA) purchases residential real estate without a bank or mortgage lender involved, you must file the real estate report. If a title company, attorney, or deed preparer is handling the transaction, they will file it on your behalf.

While this new requirement adds an extra step to the process, compliance is still mandatory. Failure to file can result in civil penalties or even criminal charges. To stay compliant, engage the right professionals—like a title company, attorney, or deed preparer—who will file the report on your behalf, or complete it yourself if no such parties are involved. The goal is clear: enjoy the asset protection benefits of an LLC while ensuring this report is filed whenever you transfer residential real estate into one.

For those interested in creative strategies or leveraging the trust exemption, additional structuring may offer ways to navigate this requirement—though success depends on your state’s laws and your specific estate. Always consult a lawyer for advice tailored to your situation. If you’d like to connect with an attorney at KKOS Lawyers, click the link below—we’re here to help.

Contact Us – KKOS Lawyers

How I’d Build Wealth From Scratch in 2026 (If I Lost It All)

If I had to start over at zero—no assets, no investments, no portfolio—what’s the smartest path to building wealth again? The key is focusing on strategically building wealth that lasts. There’s no perfect investment or trendy shortcut. It starts with doing the right things, in the right order, and staying consistent. 

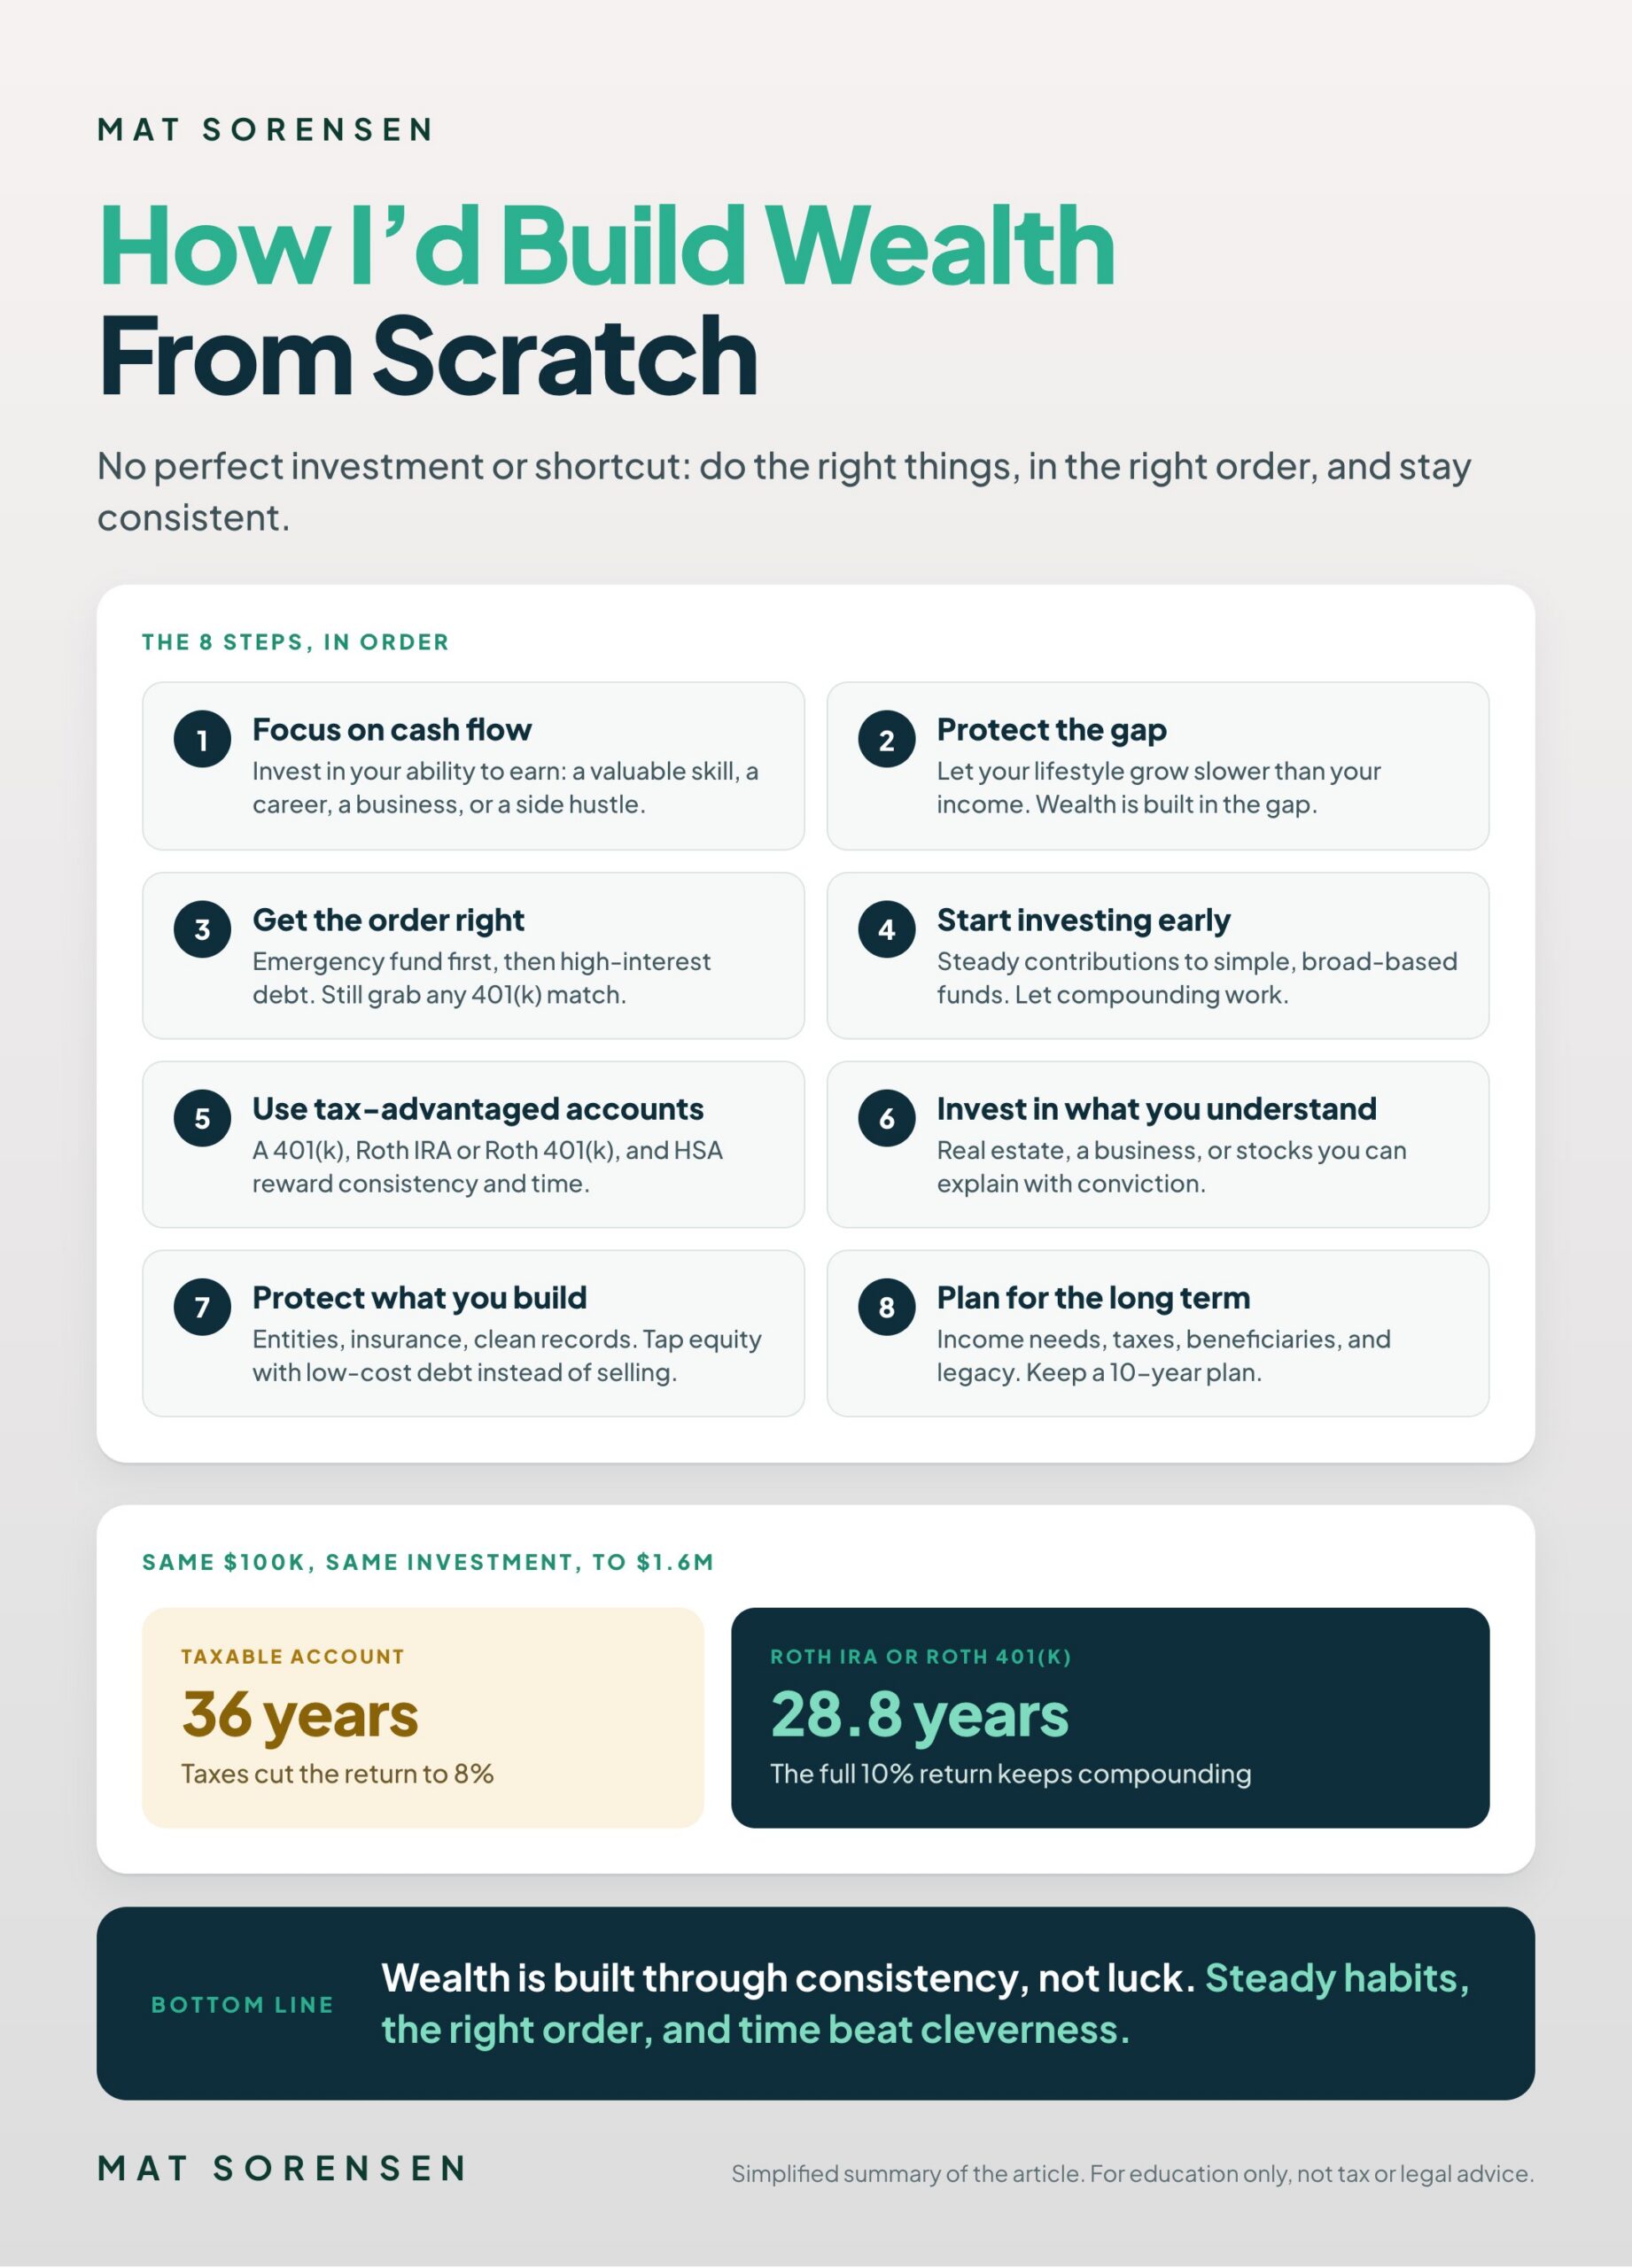
Infographic: the 8 steps to build wealth from scratch in the right order, from cash flow to long-term planning, and how a Roth account reaches $1.6M faster than a taxable account

Step 1: Focus on Cash Flow

Cash flow gives you options—and options create freedom. The first step is to invest in your ability to earn. Learn a valuable skill and put it to work in the marketplace to generate income whether it is a career or a business. That income should cover your living expenses, pay down debt, fund your savings, and build capital for future investments. To expand your margin in cash flow, consider developing a high-value skill, growing a side hustle, or taking on temporary work to increase your earning potential.

When I was a new attorney in my 20’s, I worked as assistant corporate counsel for a large health care company. I was making a good income but had debt, a family, and was impatient with my financial situation so I took on a side hustle. I worked on nights and weekends putting up advertising signs on top of gas station pumps. This gave me extra income to get out of high interest debt and to actually have cash flow to start deploying into savings to buy a home and acquire an asset. For many people, your cash flow situation may require more education, training, a side hustle, a career progression or some other action and achievement that will make you more valuable in the workforce or in your business.

Step 2: Protect the Gap Between Income and Spending

To build true wealth, your lifestyle must grow slower than your income. One of the biggest financial mistakes is letting your lifestyle expand as fast as your income. When your spending rises in step with what you earn, there’s no cash left to invest. Without consistent investing, you’ll always work for your lifestyle instead of letting your money work for you. Wealth is built in the gap between what you earn and what you spend. Those who retire early do so by maintaining a wide margin—living below their means, saving, and strategically turning that capital into income-producing assets.

REAL-LIFE EXAMPLE

I had a friend who retired in his 40’s. He was a physician and when he told me he retired I was shocked. He was always financially savvy and invested into real estate with his excess cash flow but his trick wasn’t to just earn more, instead he told me he didn’t increase his lifestyle and spending in line with his income growth. He said his lifestyle and spending always lagged about 5 years behind his income growth and his income and spending gap was wide enough that he could set more and more money aside. In other words, if he was making $250K, he lived like he made $150k. Once he was making $500K, he lived like he made $250k. Do that for a year or two and you start making progress. Do that for 10 to 15 years, and you have significant wealth accumulation. 

Step 3: Get the Order of Operations Right

People don’t fail at investing because they pick bad investments—they fail because they don’t follow the right order. First, build an emergency savings fund. Second, pay off high-interest debt, such as credit cards with 20% rates. Lower-interest debt,  like low interest student loans or a mortgage, can wait, but your goal is for your investments to outperform your debt costs. If your debt carries a higher interest rate than your expected investment return, focus on paying it down first. 

EXAMPLE

For example, if you have credit card debt at 18% interest rates, you need to pay that debt down first before you start investing. It will be hard to find an investment that gets you a higher return than 18%. The only exception worth noting here is if you have a 401(k) at work where they offer a match. Many 401(k) plans offer a match of 50% to 100%. So for example, if you make $100K and you put in $3K to your 401(k), your employer puts in $3K and now you have a total of $6k but it only cost you $3K. That is a 100% return on investment on day one so even if you have high interest credit card debt it makes sense to at least put enough into your 401(k) if your employer offers a match of 100% or even 50%. After you’ve put in enough to your 401(k) to get the free money match, go back and focus on paying down high interest debt. 

Step 4: Start Investing Early, Even If It Is Boring

Once your financial foundation is set, begin investing—even small amounts make a difference. Early investing is less about picking the perfect strategy and more about building consistent habits, learning how markets work, compounding returns over time, becoming comfortable with risk, and letting time do the heavy lifting. Avoid chasing complex strategies or hot trends. If you’re new to investing, focus on steady contributions to simple, broad-based investments like an S&P 500 index fund, which can be a mutual fund or, an ETF, or a target-date fund. Don’t overanalyze every option—just get started and let your money grow. You can always adjust your investments later; for now, the goal is to build momentum and benefit from compounding.

Step 5: Layer in Tax-Advantaged Accounts Intentionally

As your income grows, your financial strategy becomes increasingly important. Start by taking full advantage of the tax-advantaged accounts available to you. An employer-sponsored 401(k) is one of the most effective tools for growing wealth—especially if your company offers a matching contribution, which is essentially free money. A Roth IRA or Roth 401(k) allows your investments to grow tax-free and gives you flexibility in retirement withdrawals. A Health Savings Account (HSA) offers a unique triple benefit: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses.

These accounts work together as powerful wealth-building tools that reward consistency, discipline, and time. By contributing regularly and letting compounding and tax advantages work in your favor, you can grow wealth efficiently and sustainably. And remember, your money isn’t completely locked away—options like a 401(k) participant loan provide some flexibility if you ever need access to funds. Invest with confidence, knowing you’re building a system that balances growth, efficiency, and accessibility.

Retirement accounts will grow and build wealth faster than standard brokerage or taxable account investments because retirement accounts are not taxed when you make money. This means that every penny of return gets re-invested and grow and when you think of investing over  a 20 or 30 year window of time the difference between making 10% on your investments and keeping 10% (versus say 8% in a taxable account) means your money doubles and compounds over time. 

When $100K turns into $1,600,000 from Investment Returns Only

Retirement accounts total return not affected by taxes, non-retirement accounts taxable so consider account value and growth only after tax is paid. $100K is an investment amount and growth is only from investment returns and not from making additional contributions or funds to invest. 

$100k Investment Making 10% Annual Return Roth IRA or Roth 401(k) Taxable Account
10% Investment Return $1.6M in 28.8 Years X
8% Investment Return (same investment but because tax burden on investment income or gains being taxable total return is only 8%, example) X $1.6M in 36 Years

As the above example illustrates, saving in tax advantaged accounts like a Roth IRA or Roth 401(k) allows your wealth to accumulate faster which means you can reach your retirement goals faster. If you’re 40 with $100K to set aside you could end up with $1.6M by the time you’re 68 using a tax advantaged account or if you used a taxable account you could end up with $1.6M by the time you’re 76. Of course, investment returns and tax situations vary but in every instance funds invested in a Roth account that grows and comes out tax-free will beat funds invested from a taxable account. 

Step 6: Build Wealth Through Engines You Understand

Focus on investments you genuinely understand—those where you can clearly see how they generate returns, what factors influence their success, and what risks could affect them. The best investments aren’t necessarily the most complex ones; they’re the ones you can explain with confidence and conviction. If you can’t describe how your investment works or why it should succeed, it’s probably not the right place for your money. 

The goal is long-term asset accumulation—not frequent selling of appreciated assets. You want to own investments that work for you, generating cash flow and appreciating over time. That might be real estate, a business, or a stock portfolio—what matters is that you truly understand it and continue deepening your expertise. Concentrate your efforts where you have knowledge and conviction rather than spreading yourself thin across areas you don’t fully grasp. Wealth is created through focused conviction and concentration of what you know best and is preserved through thoughtful diversification to manage risk.

Step 7: Protect What You Build as It Grows

As your assets grow, your priorities evolve—protection becomes just as important as growth. Focus on building a solid foundation through proper legal and entity structures (e.g. an LLC for your rental property), adequate insurance, clean documentation, and full compliance. Protection doesn’t make you wealthier, but it prevents costly setbacks. A single lawsuit, poor partnership, or compliance mistake can erase years of progress.

This is also the stage where you begin to protect and strategically use your equity—whether it’s in your home, business, real estate, or investment portfolio. First, ensure your assets are well-protected. Then, learn how to access and leverage them to generate additional income or support your lifestyle without selling them outright. By using low-cost debt tied to strong assets, you can unlock capital for new investments or cash flow needs while your original assets continue to grow over time and this can all happen without selling the asset and causing capital gains tax. The alternative is selling the asset to receive the equity and then paying tax on the gains. By accessing equity in your asset via debt (e.g. cash out refinance of real estate or stock portfolio line of credit) you keep the asset and the future appreciation and also don’t have to pay tax on the gain from the sale because you still own the asset.

Step 8: Think Long-Term About Distribution

Think long-term and be intentional about where you’re heading. Take time to envision what your ideal financial future looks like—how much income you’ll need in retirement to sustain your lifestyle, how to structure your finances for tax efficiency, who are the beneficiaries to your wealth, and what kind of legacy or impact you hope to leave behind. These questions help you design a financial plan that aligns with your values, not just your numbers. You don’t need to have every detail mapped out from day one, but you should have a clear sense of direction. Wealth without purpose or planning eventually gets wasted. I keep a 10 year plan and update multiple times over the year. I think back in 5 years and then in 3 and 1 year phases. I make goals and stick to them. We underestimate what we can accomplish in 10 years and by taking the time to think through what your goals can be in 10 years you have more clarity about what you should be doing in 5 years, 3 years, and this year.  

The Big Picture: Consistency Beats Cleverness

Wealth is built through consistency, not luck. Success comes from steady habits, patience, and discipline—not quick wins or trends. Building wealth from scratch isn’t about chasing the perfect investment; it’s about following a sound plan, taking deliberate steps in the right order, and staying the course long enough for your efforts to produce lasting results.

If you’d like to learn more, I’ve created a guide called The Ideal Order of Investing, available through the link below. In it, I break down the key steps to take in the right sequence—helping you focus on what matters most right now and what to prioritize next in your wealth-building journey.

Building Wealth Guide: The Ideal Order of Investing | Mat Sorensen

FREE SELF-DIRECTED IRA GUIDE

Learn how a self-directed Roth IRA can invest in real estate, private companies, notes, and more, and keep the growth tax-free.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

Disclaimer

This article is for educational purposes only and does not constitute legal, tax, or investment advice. Tax results depend on individual circumstances, future legislation, and proper implementation. Consult qualified advisors before implementing any strategy. Investment outcomes depend on investment performance, contribution discipline, future tax law, and proper execution. No specific result is guaranteed.