When is a Business Partner a Disqualified Person to My Self-Directed IRA?

Most self directed IRA owners know that their self directed IRA cannot conduct transactions with themselves or certain family members (e.g. spouse, kids, parents, etc.). Most self directed IRA owners also know that their self directed IRA cannot do business with a company they own or that their disqualified family members own 50% or more of. However, one of the most confusing areas of the prohibited transaction rules are the prohibited transaction rules which apply to business partners or officers, directors, and/or highly compensated employees of companies the IRA owner or family members are personally involved in. For example, what if I own a business with a partner? Can my IRA enter into a transaction with that business partner if we aren’t family? Well, it depends.
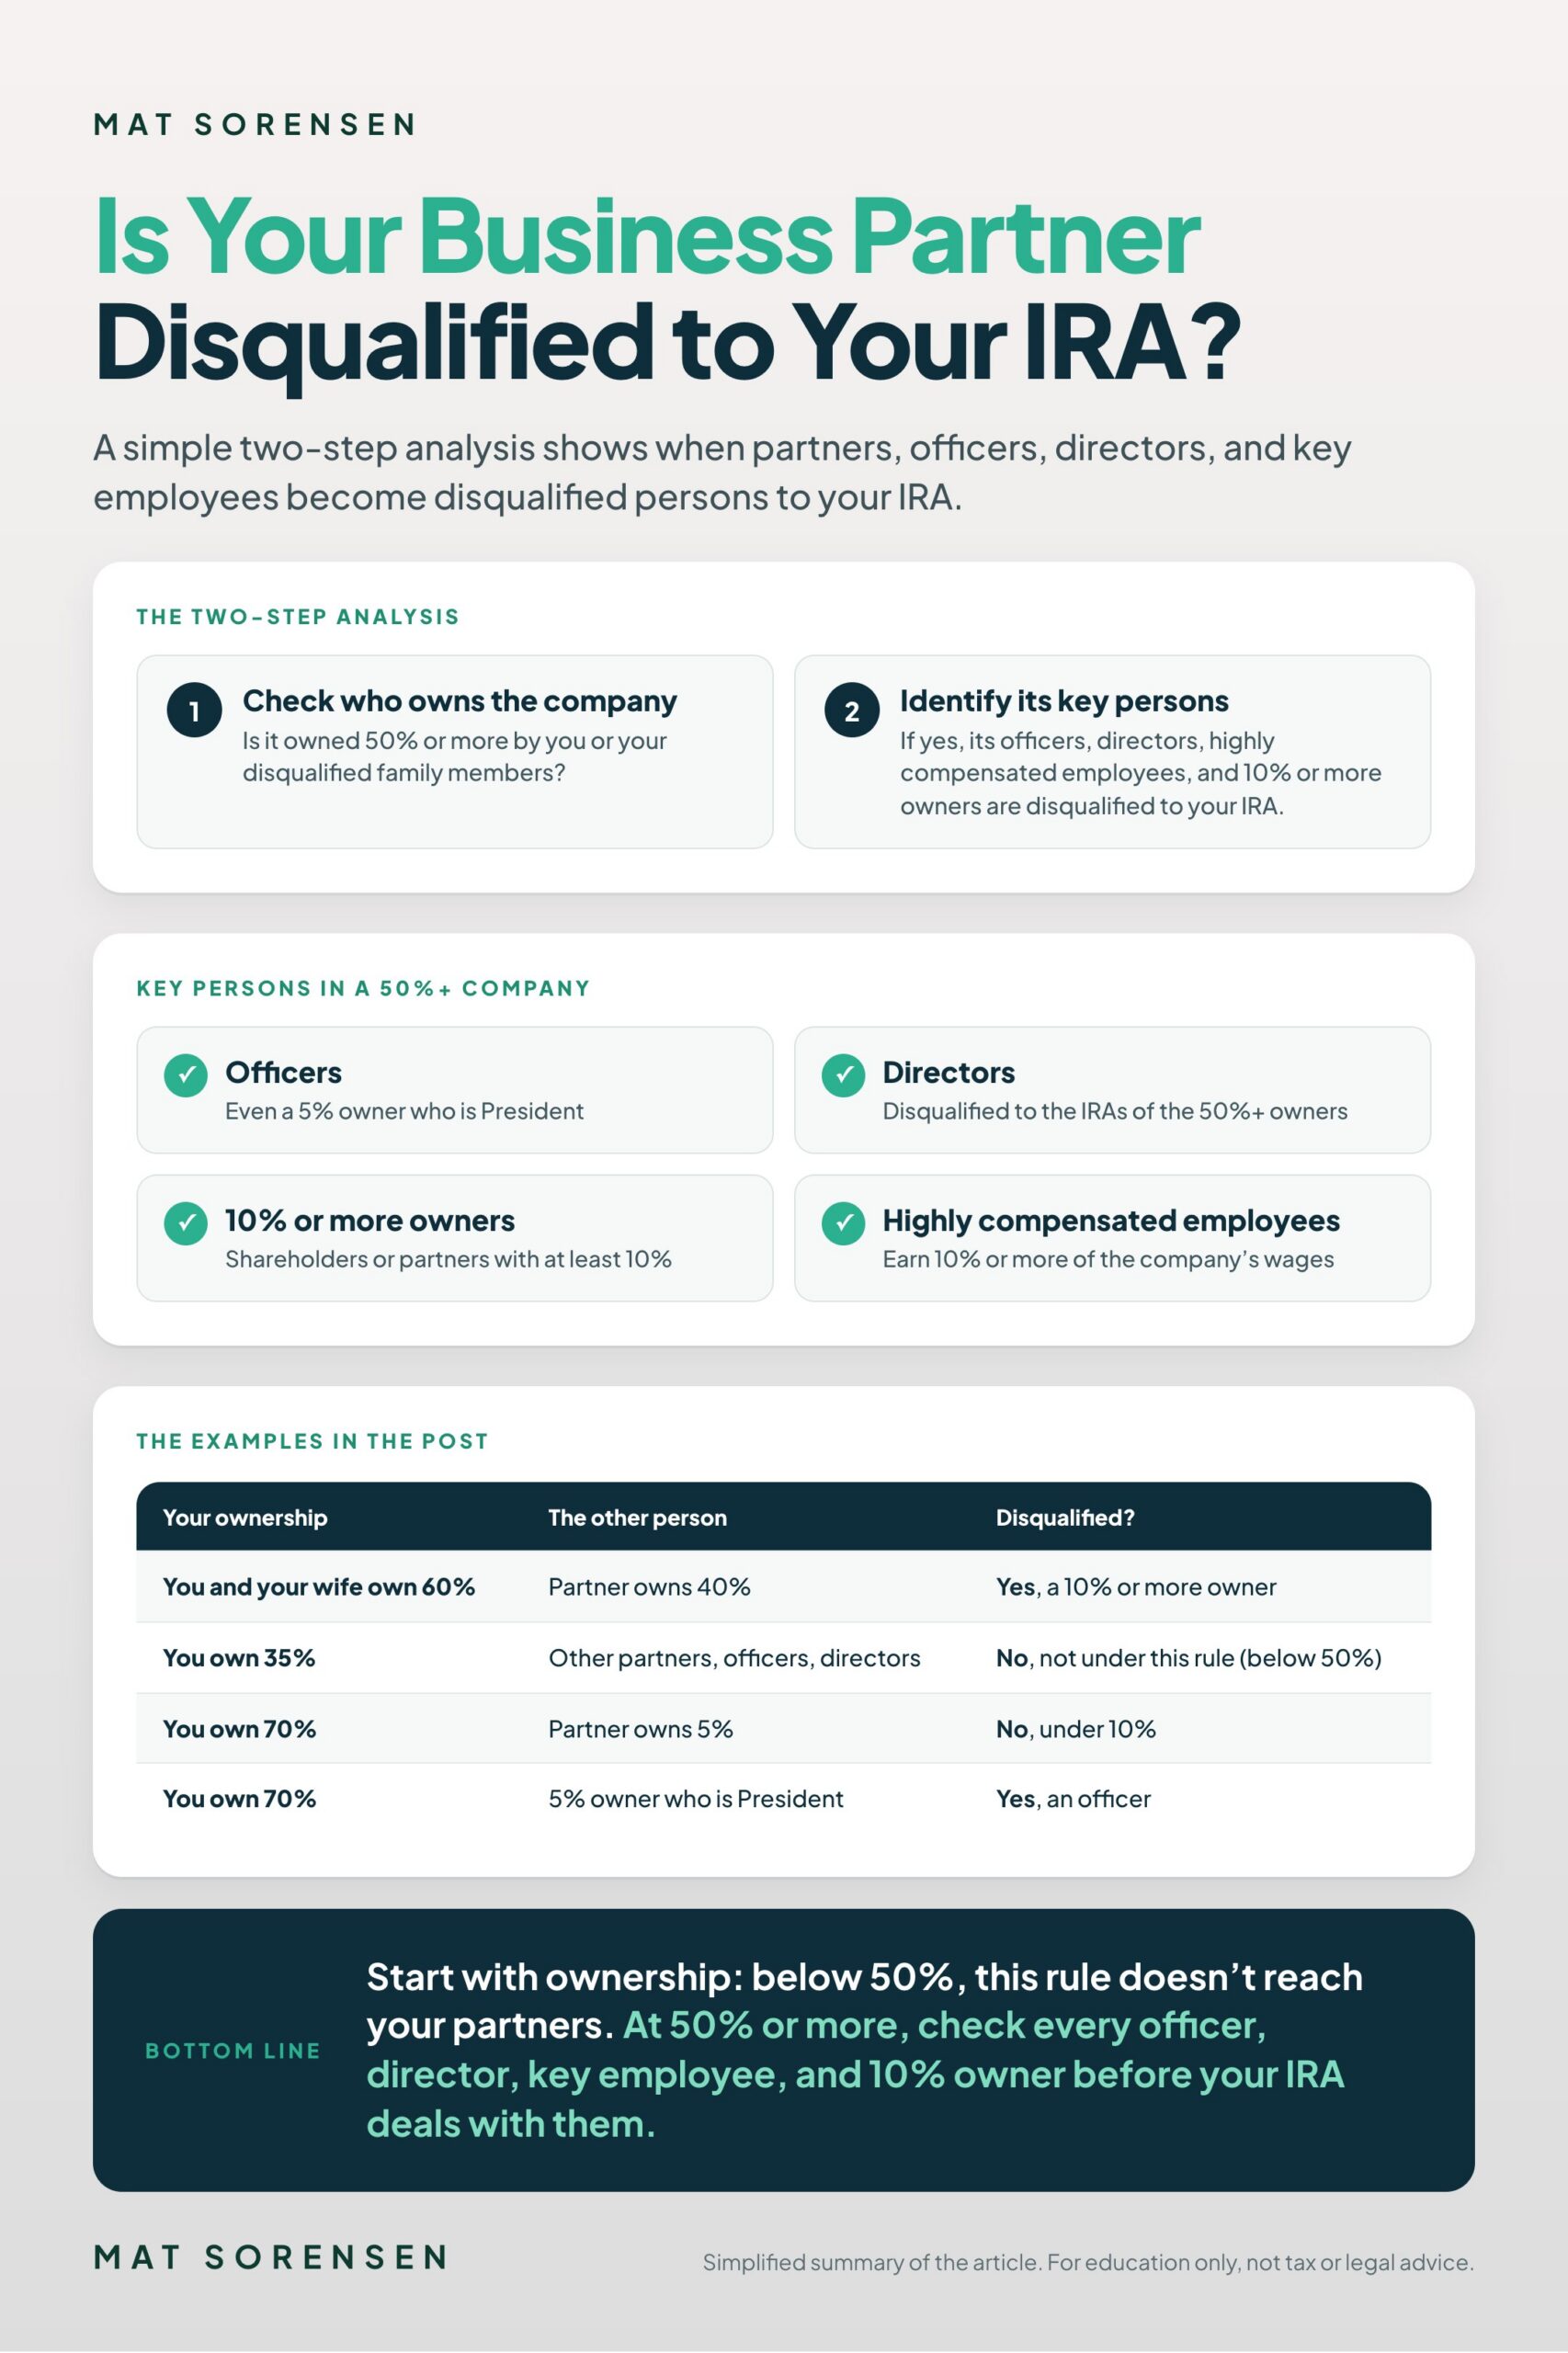
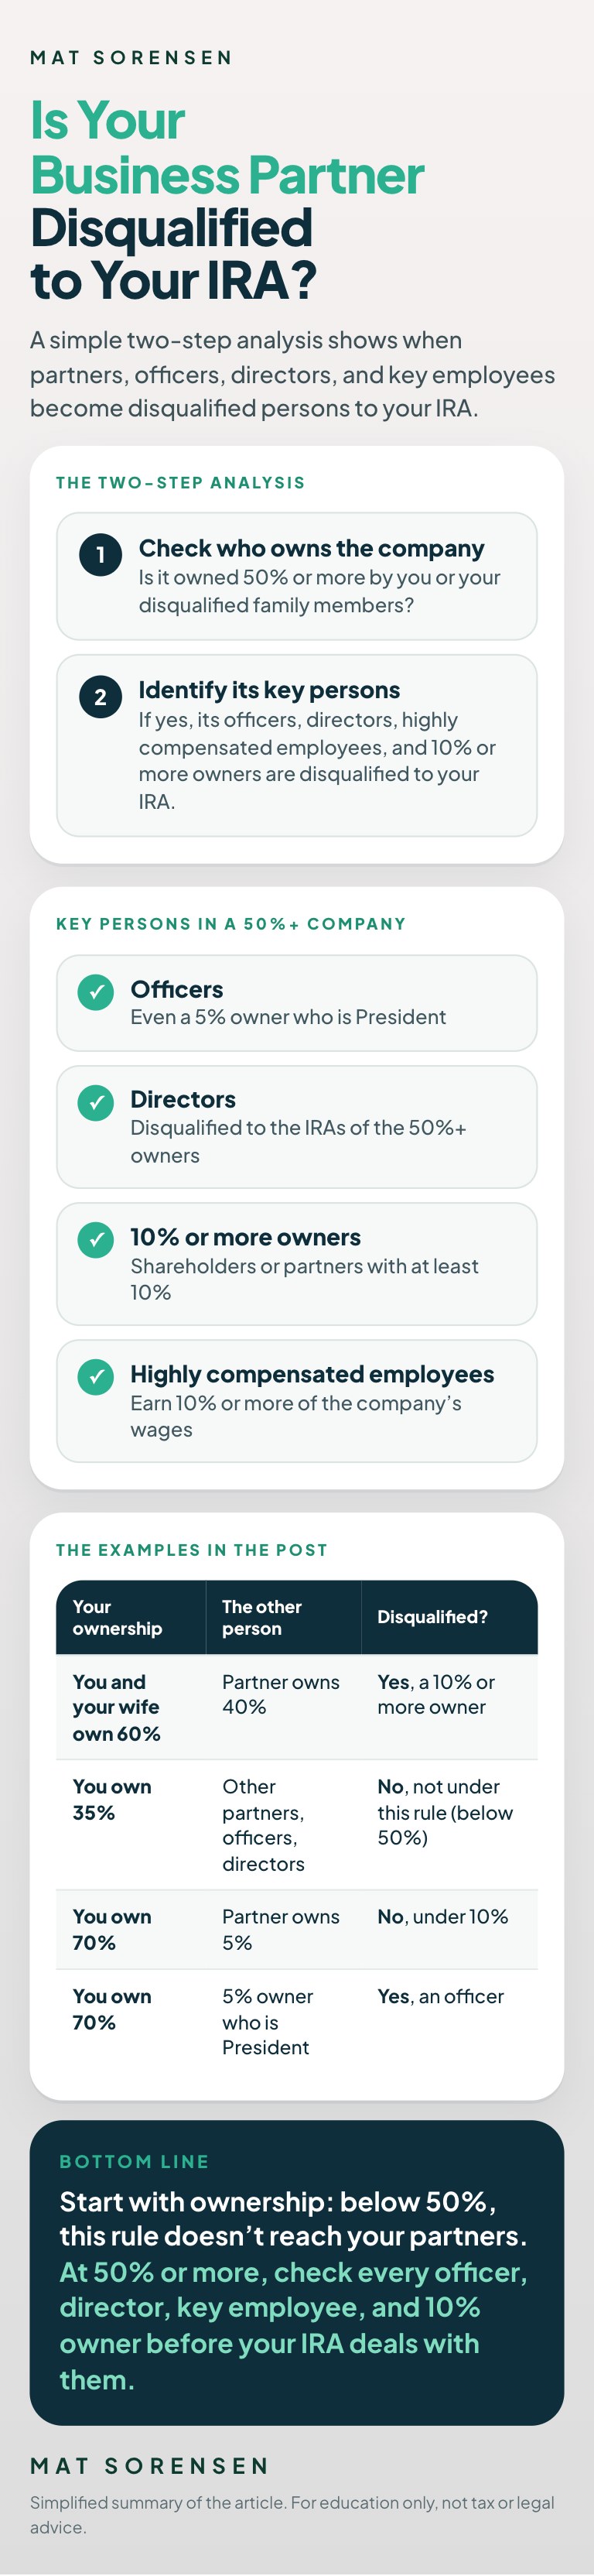
Infographic: the two-step analysis for when a business partner, officer, director, or key employee is a disqualified person to your IRA

Disqualified Person Analysis

To analyze the rules you first need to determine whether the company in which the business partner (or officer, or director) is involved in is a company that is owned 50% or more by the IRA owner or their disqualified family members. IRC 4975 (e)(2)(E),(H), (I). So, for example, if my wife and I owned 60% of the business and our partner owned 40% of the business, then this company would be owned 50% or more by disqualified persons.

Once we know that the company is owned 50% or more by disqualified persons, we need to identify all of the officers, directors, highly compensated employees, and 10% or more owners of that company. In sum, all of these persons are disqualified to the IRAs of the 50% or more owners. In the example above, since my business partner owned 40% of the company, he is a 10% or more owner and as a result he is a disqualified person to my IRA (since my wife and I own 50% or more of the company).

EXAMPLE

Let’s look at another example. Say that I am a 35% owner of a business with a few other partners who are not disqualified family members to me.  Since I do not own 50% or more of this company, it doesn’t matter who the other partners, officers, or directors, are, as they are not disqualified to my IRA as part of this rule since my ownership (and that of my disqualified family members) is below 50%.

EXAMPLE

As a final example, let’s say that I own 70% of a company and that I have a partner who owns 5%. Under the rule, my partner or fellow shareholder does not have 10% or greater ownership and as a result they are not disqualified to my IRA. However, if that 5% owner was the President of my company then they would be a disqualified person.

These rules can be tough to understand when you read the code, but if you take the two step analysis you can easily determine what partners, officers, directors, or highly compensated employees are disqualified to your IRA.

Here’s also a quick summary of the rule from my book where I took the text of the tax code and put it into plain language.

Key Persons in Company Owned 50% or More by Disqualified Persons

An officer, director, or 10% or more shareholder, or highly compensated employee (earns 10% or more of the company’s wages) of a company owned by the IRA owner or other disqualified persons. IRC § 4975 (e)(2)(H).

Before investing with someone who is an officer, director, highly compensated employee, or a shareholder/owner in a company you are involved in, please consult these rules and where you are unclear, seek the advice of competent counsel.

THE SELF-DIRECTED IRA HANDBOOK

Mat’s best-selling guide to the rules: prohibited transactions, UBIT, IRA/LLCs, and the mistakes to avoid.

Get the Free Handbook

Prefer to talk it through? Book a call with a Directed IRA specialist
401(k) Contributions from S-Corp Income

A properly structured s-corporation is utilized best when business owners adopt and contribute to a 401(k) plan. Whether the business has only one owner/employee (or spouses only) or whether the business has dozens or even hundreds of employees. Simply put, a 401(k) plan can be used as a tool for putting the income of the business owner (any applicable employees) away for retirement with the added benefit of a tax deduction for every dollar that can be contributed. There are so many neat things about 401(k) plans and there are so many options.  For example, you can do Roth 401(k) plans, you can self direct a 401(k) plan, and you can even loan money to yourself from your 401(k) account. While books have been written about all of these options and benefits, one of the most misunderstood concepts of 401(k) plans is how s-corporation owners can contribute their income to the plan. That is the focus of this article.

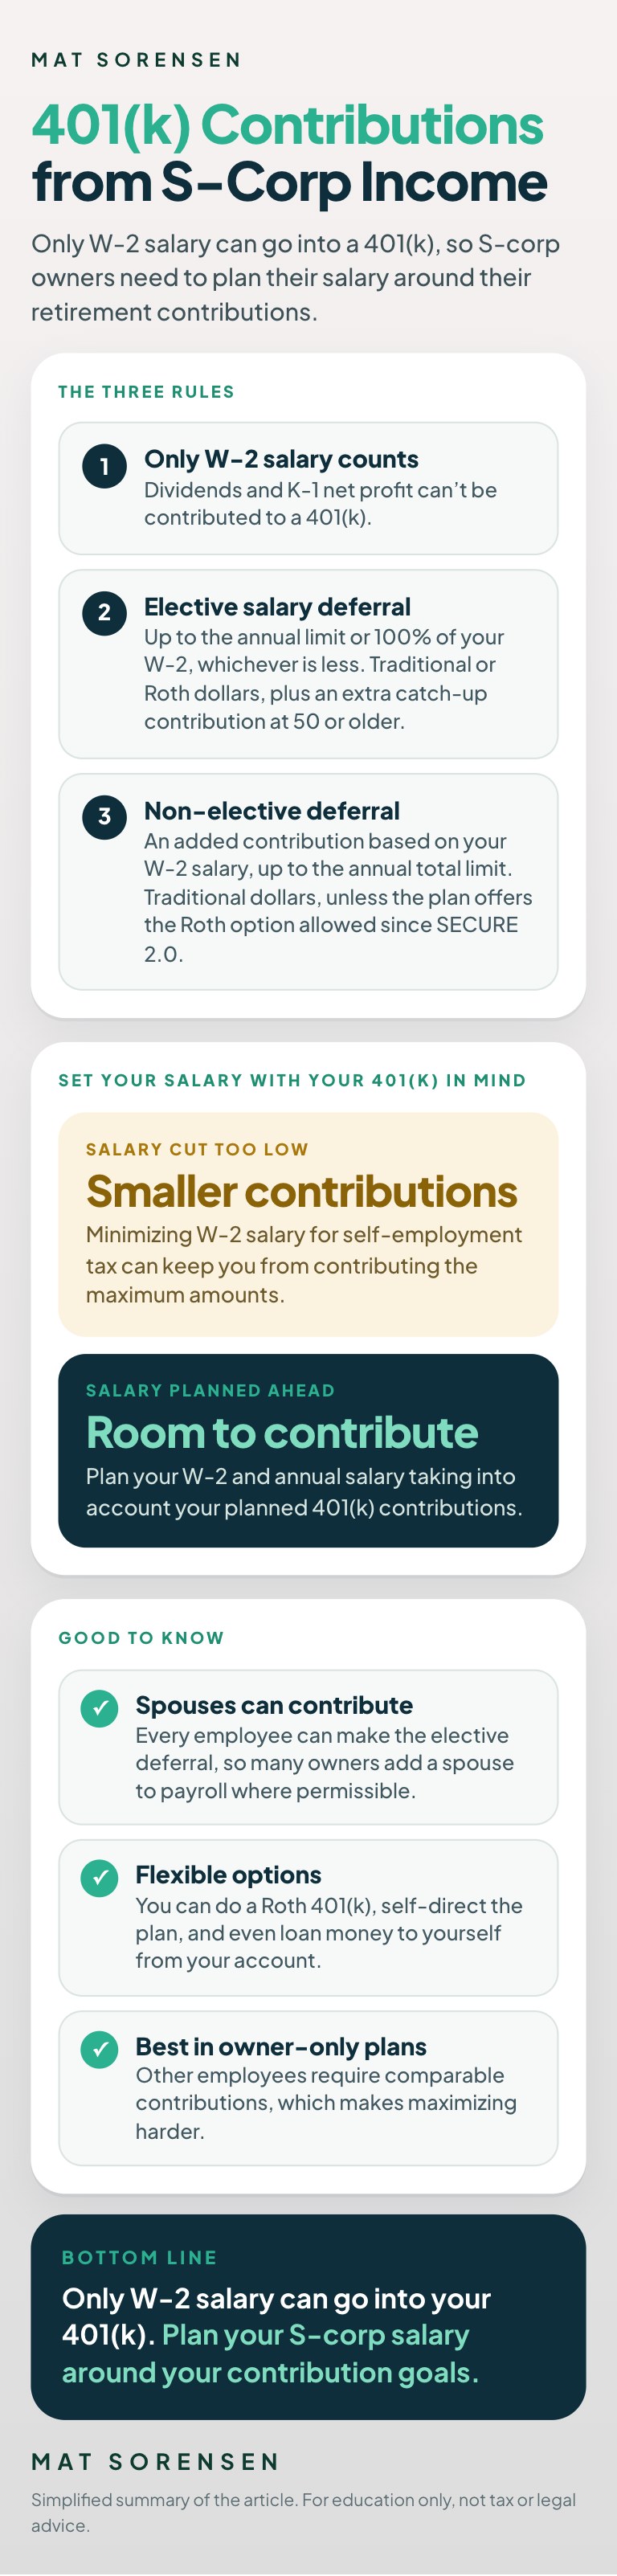
Infographic: the three rules for making 401(k) contributions from S-corporation income and why S-corp owners should plan their W-2 salary

Rules for 401(k) Contribution

In order to understand how s-corporations income can be contributed to a 401(k) plan, you need to understand the following three basic rules:

  1. 1Only W-2 Salary Income can be Contributed to a 401(k). You cannot make 401(k) contributions from dividend or net profit income that goes on your K-1. See IRS.gov for more details. Since many s-corporation owners seek to minimize their W-2 salary for self-employment tax purposes, you must carefully plan your W-2 and annual salary taking into account your annual planned 401(k) contributions. In other words, if you cut the salary too low you won’t be able to contribute the maximum amounts. On the other hand, even with a low W-2 Salary from the s-corporation you’ll still be able to make excellent annual contributions to the 401(k) (up to $17,500 if you have at least that much in annual W-2 salary).
  2. 2Easy Elective Salary Deferral Limit of $17,500 or 100% of Your W-2, whichever is less. If you have at least $17,500 of salary income from the s-corporation, you can contribute $17,500 to your 401(k) account.  Every employee under the plan is allowed to make this same contribution amount. As a result, many spouses are added to the s-corporation’s payroll (where permissible) to make an additional $17,500 contribution for the spouse’s account. If you are 50 or older, you can make an additional $5,500 annual contribution.  Follow this link for the details from the IRS on the elective salary deferral limits. The elective salary deferral can be traditional dollars or Roth dollars.
  3. 3Non-Elective Deferral of 25% of Income Up to a $52,000 total Annual 401(k) Contribution. In addition to the $17,500 annual elective salary contribution, an s-corporation owner can contribute 25% of their salary compensation to their 401(k) account up to a maximum of a $52,000 total annual contribution.  This non-elective deferral is always made with traditional dollars and cannot be Roth dollars. So, for example, if you have an annual W-2 of $100,000, you’ll be able to contribute a maximum of $25,000 as a non-elective salary deferral to your 401(k) account. If you have employees who participate in the plan besides you (the business owner) and your spouse, then the non-elective deferral calculation gets much more complicated. But for now, let’s assume there are no other employees and run through the examples.

UPDATE (NOV 2026)

Since the SECURE 2.0 Act (2022), a 401(k) plan can let employees choose Roth treatment for employer matching and profit-sharing contributions (if fully vested); those contributions are taxable in the year they’re made. (Source: IRS Notice 2024-2)

Examples

Let’s run through two examples. The first is an s-corporation business owner looking to contribute around $30,000 per year. The second is a business owner looking to contribute the maximum of $52,000 a year.

EXAMPLE

Example 1: Seeking a $30,000 Annual Contribution.

S-Corporation Owner W-2 Salary = $50,000

Elective Salary Deferral = $17,500

25% of Salary Non-Elective Deferral = $12,500 (25% of $50,000)

Total Possible 401(k) Contribution = $30,000

EXAMPLE

Example 2: Seeking Maximum $52,000 Annual Contribution

S-Corporation Owner W-2 Salary = $138,000

Elective Salary Deferral = $17,500

25% of Salary Non-Elective Deferral = $34,500 (25% of  $138,000)

Total Possible 401(k) Contribution  (maximum) = $52,000

As a result of the calculations above, in order to contribute the maximum of $52,000, you need a W-2 salary from the s-corporation of $138,000. Keep in mind that if you have other employees in your business (other than owner and spouse) that you are required to do comparable matching on the 25% non-elective deferral and as a result such maximization is often difficult to accomplish in 401(k)s with employees other than the owner and their spouse. Consequently, the additional 25% non-elective salary deferral is best used in owner only 401(k) plans.

UPDATE (NOV 2026)

The rules and examples above use the limits from when this article was written. For 2026, the employee deferral limit is $24,500 ($32,500 at age 50+) and the total limit is $72,000. (Source: IRS)

FREE SOLO 401(K) GUIDE

Self-employed? Learn how a self-directed Solo 401(k) works and how much you can contribute.

Get the Free Solo 401(k) Guide

Prefer to talk it through? Book a call with a Directed IRA specialist
Why You Need a Living Will? Ripped From the Headlines: THE MUNOZ CASE

The recent case of Marlise Munoz reminds us all of one important decision we should not leave to others: Whether we want to remain on life support or not. A living will is a legal document that can be used to make  decisions as to whether we want to be on life sustaining support or whether we want to “pull the plug” if we are brain dead and in a vegetative state.

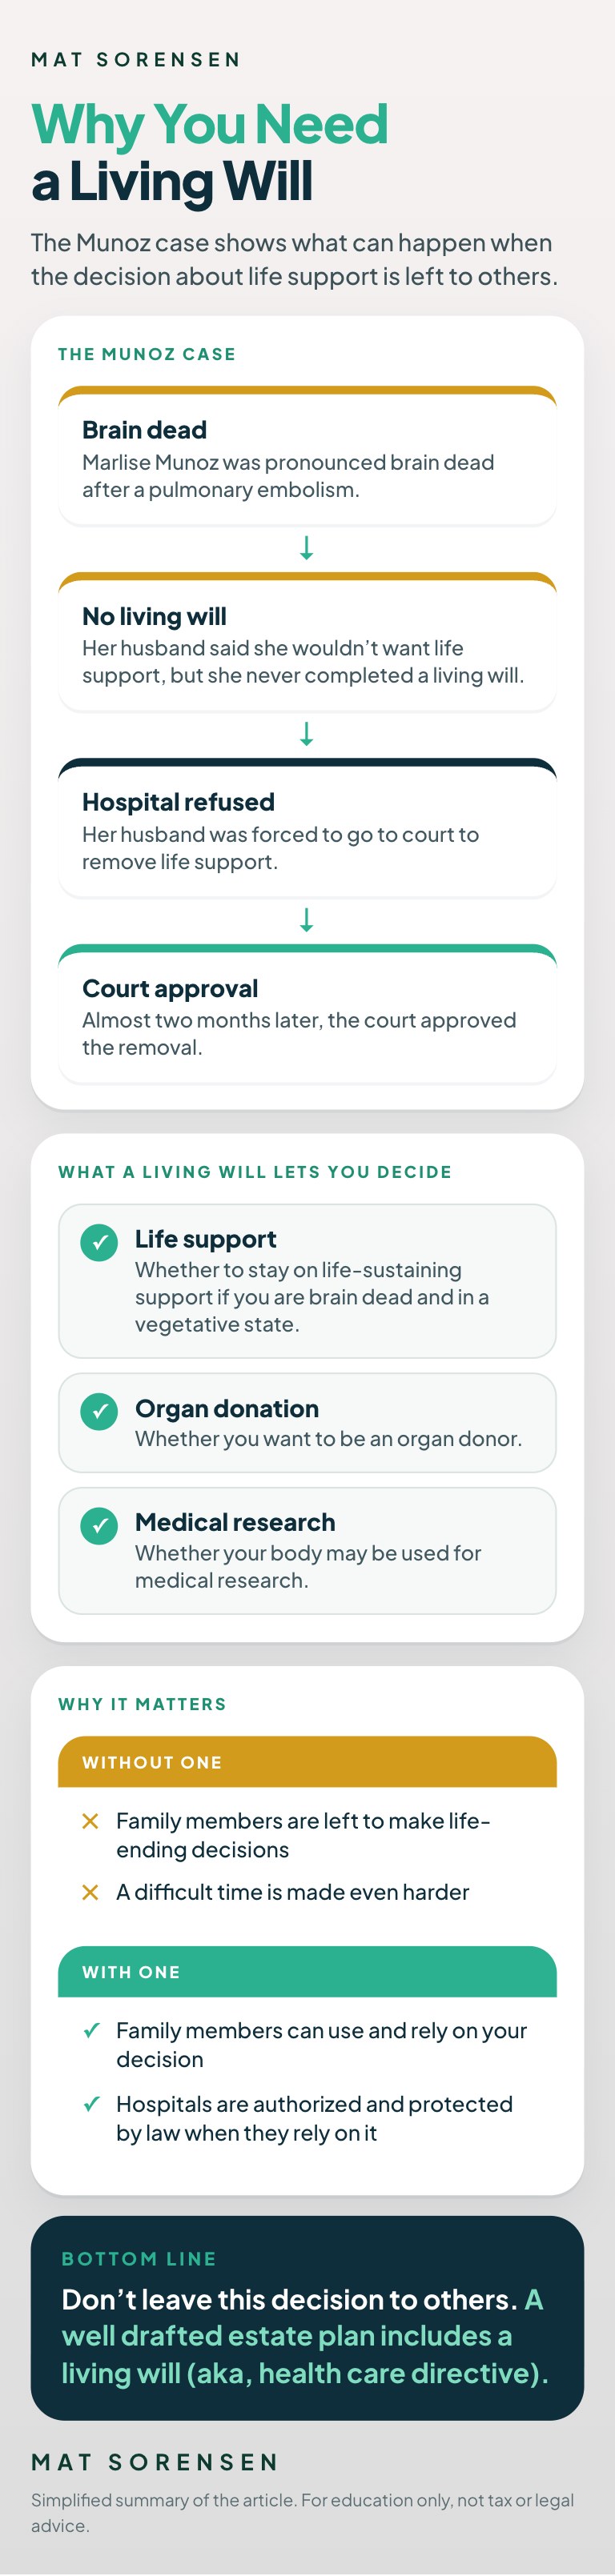
Infographic: what happened in the Munoz case and what a living will lets you decide

What Happened in the Munoz Case

In November, Marlise Munoz suffered a pulmonary embolism and was taken to a hospital in her town of Fort Worth. She was pronounced brain dead two days later. Marlise was 14 weeks pregnant and under Texas law, her body was required to be left on life support even though the fetus was not able to survive.

Erick Munoz, Marlise’s husband, attempted to have her life support and ventilation removed after being told she was brain dead and after being with his wife’s body in the hospital. He stated she had previously expressed to him that she would not want to be kept on life support if she was in a vegetative state. However, Mrs. Munoz did not complete a living will.

Mr. Munoz stated to the Court that it was difficult to “endure the pain of watching my wife’s dead body be treated as if she were still alive.”

He further stated that, “As a married man, I became very familiar with the way Marlise’s body felt, the way her hair smelled and the way her eyes appeared when we looked at each other, among other things. Over these past two months, nothing about my wife indicates she is alive. When I bend down to kiss her forehead, her usual scent is gone. Finally, one of the most painful parts of watching my wife’s deceased body lie trapped in a hospital bed each day is the soulless look in her eyes. Her eyes, once full of the ‘glimmer of life,’ are empty and dead.”

Despite Mr. Munoz’s requests to the hospital that his wife be removed from life sustaining support, the hospital refused and Mr. Munoz was forced to file an action in Court to have the ventilation and feeding tube removed. Almost two months later, the Court in Texas finally approved the removal of life support and Mr. Munoz is finally able to lay his wife’s body to rest.

How a Living Will Helps Your Family

Dealing with the death of a spouse or other close family member is one of the most difficult situations a person will face. However, that experience is compounded and made even more difficult when family members are put into situations where they must make life ending decisions for their loved ones.

A well drafted estate plan includes a living will (aka, health care directive) whereby a person makes a legal decision for themselves about whether they want to be on  life sustaining support or whether they want to be removed if they are brain dead and in a vegetative state. The living will can be used and relied on by family members and also allows a person to declare whether they want to be an organ donor and whether they want their body to be used for medical research or not. Hospitals are authorized and protected by law when they rely on a living will and it makes family decisions at a hospital so much easier.

Contingency Clauses in Real Estate Purchase Contracts

Contingency clauses are some of the most important components of a real estate purchase contract, and can provide significant protections to buyers of real estate. A contingency clause typically states that a buyer’s offer to buy property is contingent upon certain things. For example, the contingency clause may state, “The buyer’s obligation to purchase the real property is contingent upon the property appraising for a price at or above the contract purchase price.” Under this contingency, the buyer is relieved from the obligation to buy the property if the buyer obtains an appraisal that falls below the purchase price. Because contingency clauses provide the buyer a way to back-out of a contract they can be excellent tools for real estate investors who make numerous offers on properties.

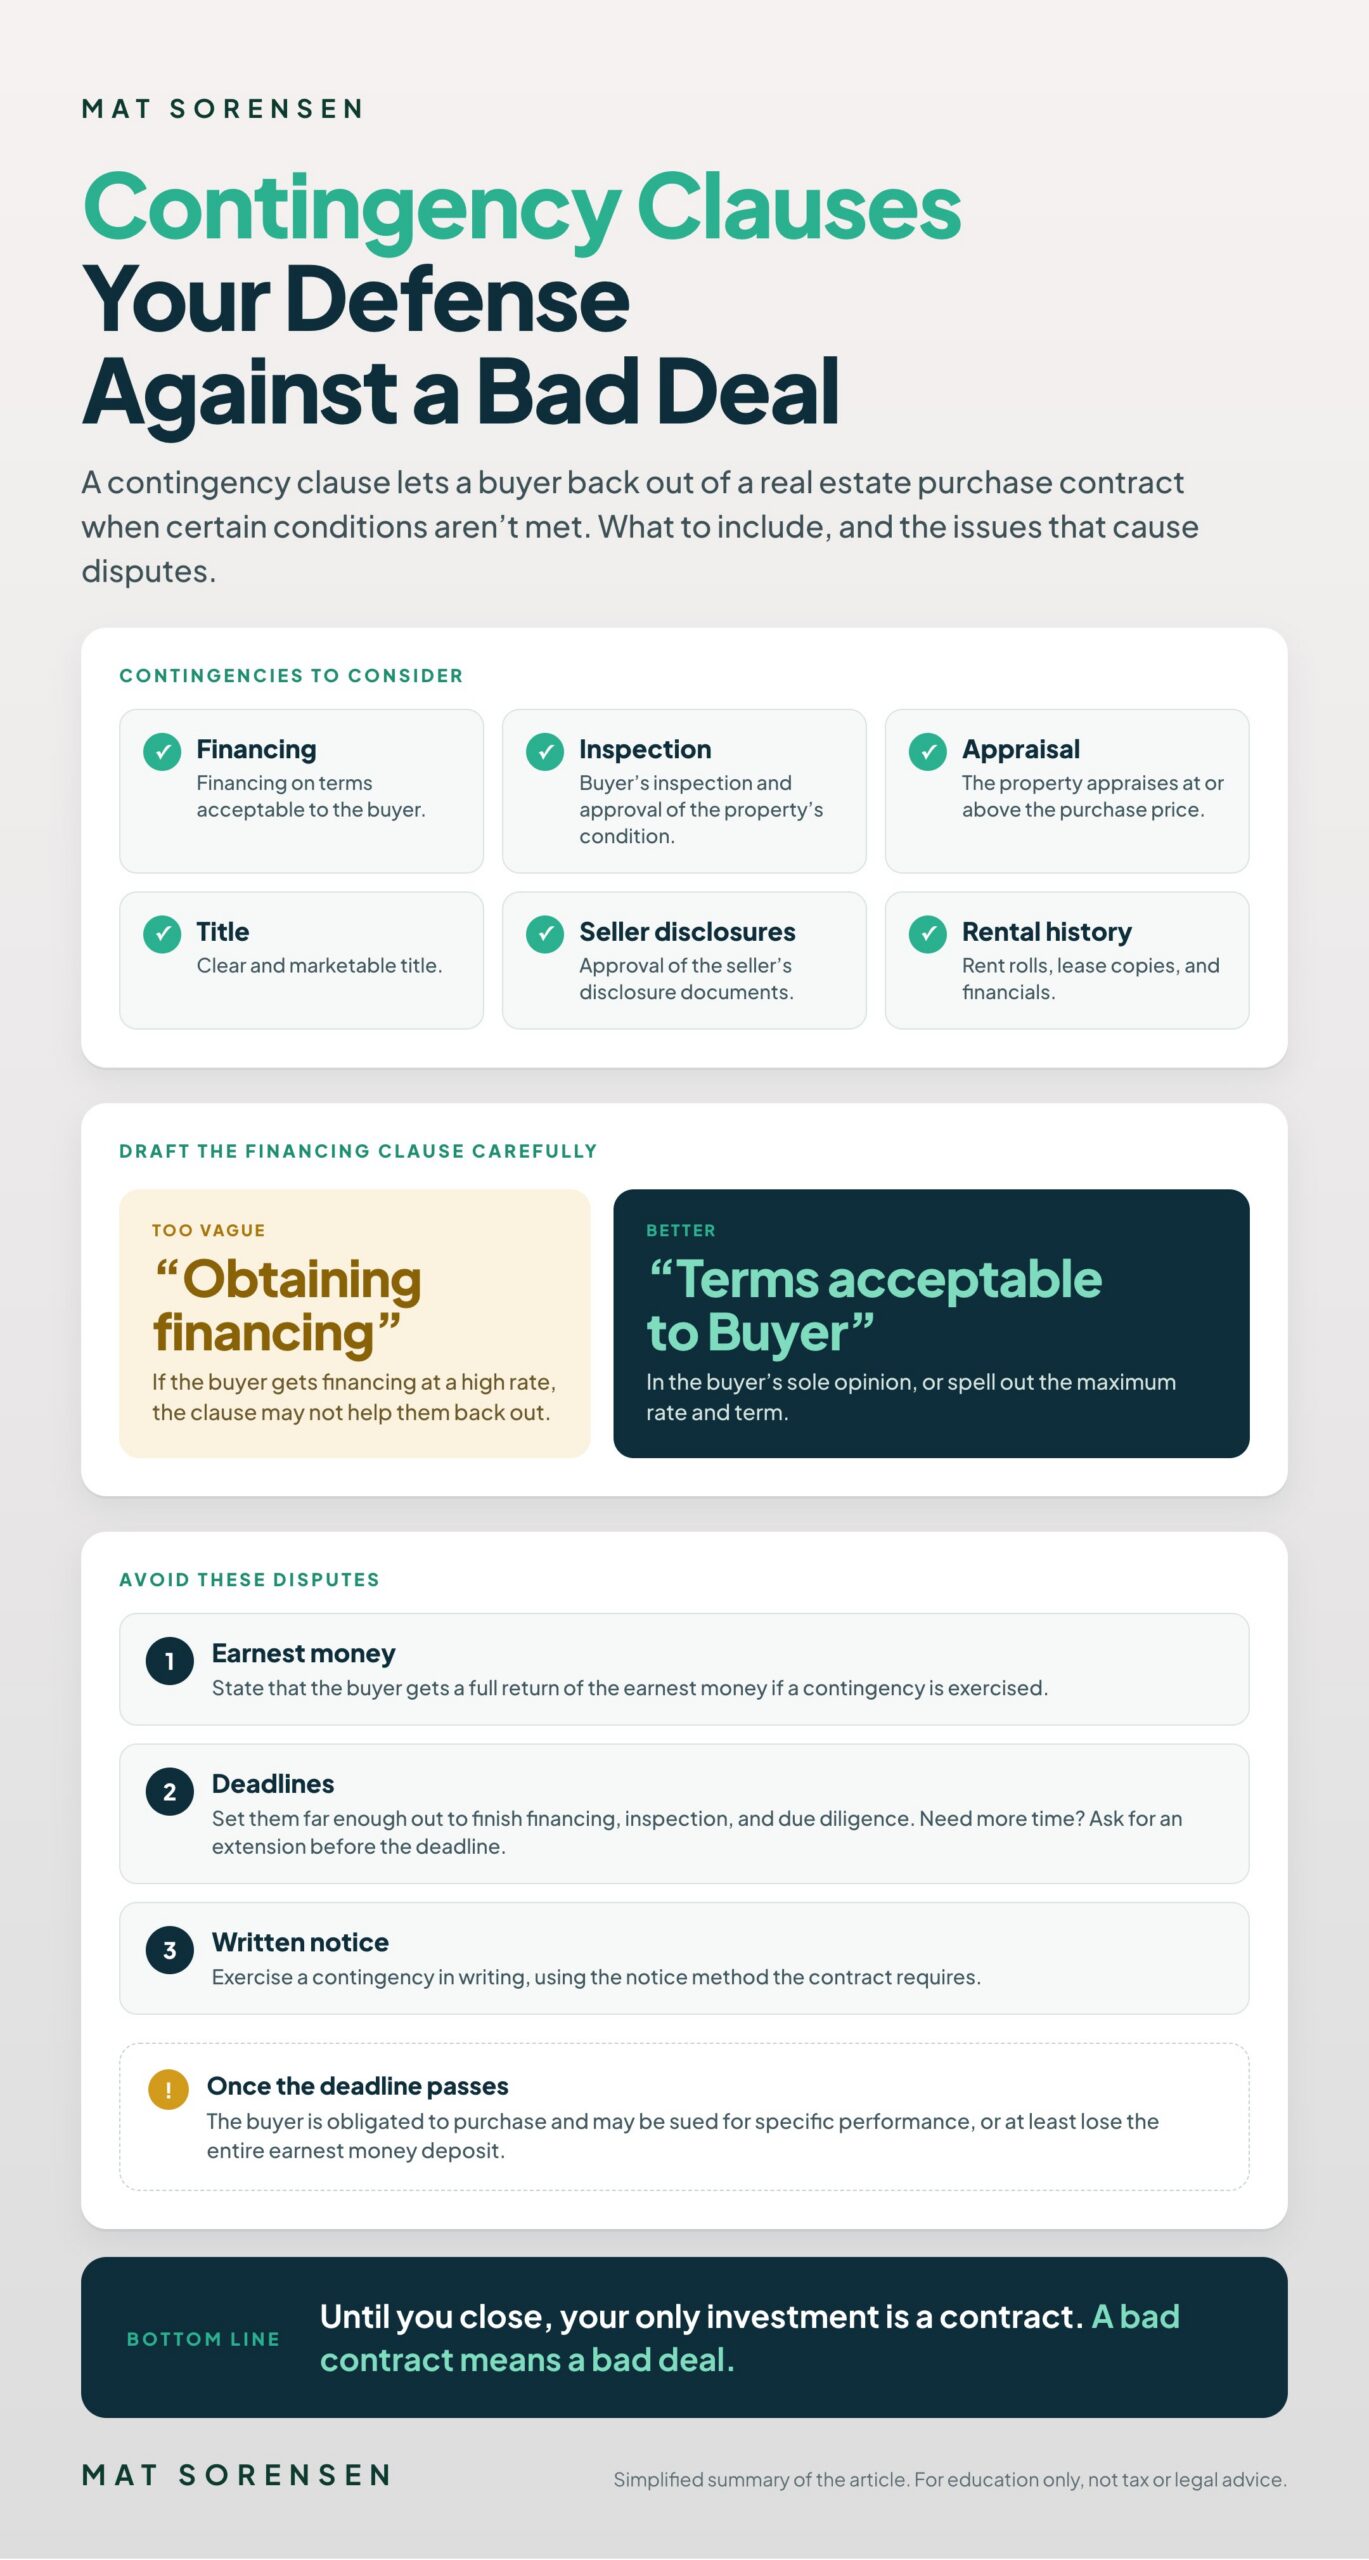
Infographic: contingency clauses to consider in a real estate purchase contract and the issues that cause disputes

Contingency Clause Examples

Here are some contingency clauses to consider in your real estate purchase contract.

1. Financing Contingency

A financing contingency clause states something like, “Buyer’s obligation to purchase the property is contingent upon Buyer obtaining financing to purchase the property on terms acceptable to Buyer in Buyer’s sole opinion.” Some financing contingency clauses are not well drafted and will provide clauses that say simply, “Buyer’s obligation to purchase the property is contingent upon the Buyer obtaining financing.” A clause such as this can cause problems as the Buyer may obtain financing under a high rate and thus may decide not to purchase the property. However, because the contingency only specified whether financing is obtained or not (and not whether the terms are acceptable to buyer), the clause can be unhelpful to a buyer deciding not to purchase the property. Some financing clauses are more specific and, for example, will say that the financing to be obtained must be at a rate of at most 7% on a 30 year term and that if the buyer does not obtain financing at a rate of 7% or lower then the buyer may exercise the contingency and back out of the contract.

2. Inspection Contingency

An inspection contingency clause states something like, “Buyer’s obligation to purchase is contingent upon Buyer’s inspection and approval of the condition of the property.” Another variation states that the Buyer may hire a home inspector to inspect the property and that the Seller must fix any issues found by the inspector and if the Seller does not fix the items specified by the inspector then the Buyer may cancel the contract. Inspection clauses are very important as they ensure that the Buyer is obtaining a valuable asset and not a money pit full of defects and repair issues.

Other important contingency clauses are clear and marketable title clauses, approval of seller disclosure documents, and rental history due diligence information (e.g., rent rolls, lease copies, financials, etc.).

Contingency Clause Issues

When using contingency clauses buyers should pay attention to a few key terms. I’ve personally seen many disputes arise as a result of one of the following issues.

1. What Happens to the Earnest Money

One important consideration that is often vague in real estate purchase contracts is what happens to the buyer’s earnest money when the buyer exercises a contingency. Does the buyer receive a full return of the earnest money? Does the seller keep the earnest money? If the contract is silent and if you as the buyer exercise a contingency, don’t count on the seller agreeing to a release of the earnest money as they are often upset that you are not going to purchase the property. Make sure the contract clearly states something like the following,

“If Buyer exercises any contingency, Buyer shall receive a full return of any earnest money deposit or payment to Seller.”

2. Contingency Deadlines

Another important contingency clause issue is the date of the contingency clause deadline. Most contingency clauses have expiration dates that occur well before closing. Those dates should typically be somewhere from 2 weeks to 2 months from the date of the contract, depending on the purchase and seller disclosure items and the type of property being purchased.

EXAMPLE

For example, single family homes will typically have a shorter window as financing and inspection can occur more quickly than would occur under a contract to purchase an apartment building.

Whatever the deadline is, make sure that the deadline is set far enough out so that you can complete your contingency tasks. You need to make sure you have enough time to obtain adequate financing commitments, to properly inspect the property, and that you have enough time to review the seller’s disclosure documents. Setting a two week deadline is sometimes done but two weeks is usually not enough time to complete financing commitments, inspection, and due diligence activities that are necessary to determine whether you are going to commit to purchasing the property.

If contingency deadlines are approaching and you need more time, then ask the seller for an extension before the deadline arrives. If the Seller refuses an extension, then exercise the contingency you need more time to satisfy.

3. Exercise Your Contingency in Writing

If you do exercise a contingency and decide to back-out of the purchase of the property, make sure you do it in writing. Don’t rely on telephone calls or even e-mails (unless the contract permits e-mails as notice). Additionally, make sure that the reason for the contingency and that the date of the contingency are put in writing and are sent to the seller in a method where the date can be tracked in accordance to the notice provisions of the contract. For example, if the contract requires a contingency to be noticed by fax or hand delivery, don’t rely on an e-mail to the seller or the seller’s agent as such communication will not invoke the contingency.

Once the deadline to exercise a contingency has passed, the buyer is obligated to purchase the real property and may be sued for specific performance (meaning they can be forced to buy) or at the least the buyer will lose their entire earnest money deposit.

Contingency clauses are the best defense mechanism to a bad deal and should always be used by real estate buyers. Keep in mind that until you close on the property, the only investment you have is a contract and if you have a bad contract, then you have a bad deal.

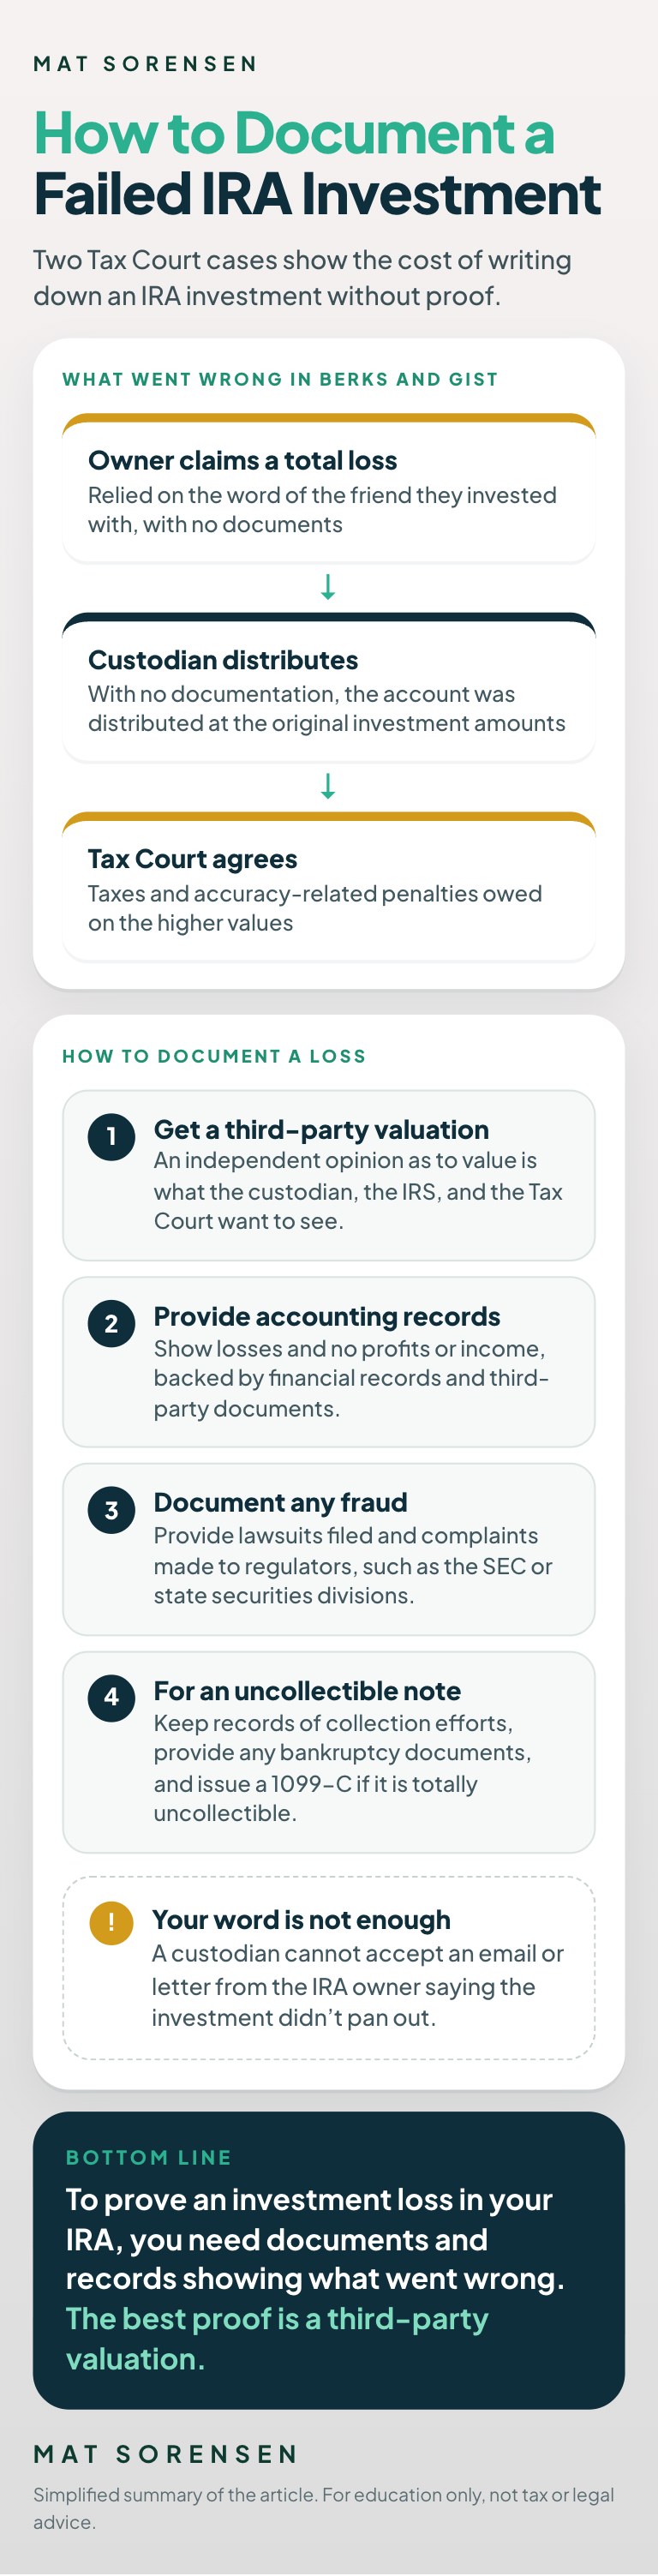
How to Document and Write Down a Failed IRA Investment

While every self directed IRA investor enters into investments with high hopes and expectations of large gains, sometimes an IRA has to declare a loss on its investments and sometimes those losses are total losses. However, how does an IRA document a loss on a private partnership investment or an uncollectible promissory note investment? Two Tax Court opinions released today show us what not to do. Berks v. Commissioner, T.C. Summary Opinion 2014-2, Gist v. Commissioner, T.C. Summary Opinion 2014-1.

Infographic: what went wrong in Berks and Gist, and four ways to document a loss on a failed self-directed IRA investment

Berks v. Commissioner and Gist v. Commissioner

In Berks and Gist, self directed IRA owners invested their IRAs into various real estate partnerships and had equity interests and promissory note interests. Approximately five years after the investments were made, the IRA owners sought to declare the values on all of the investments worthless as the partnerships were no longer in business and as the IRA owner was told by their friend who they invested with that the investments were worthless. The IRA custodian for Berks and Gist sought additional documentation before agreeing to write down the value of the investments. Writing down the value of an investment and closing an account is a red flag for the custodian and the IRS as both want to ensure that IRA owners are not unfairly writing down investments in an effort to avoid taking distributions from the IRA which are taxable. As a result, the IRA custodian sought documentation as to the valuation change and upon receiving no documentation; the IRA custodian distributed the account to the IRA owners with the original investment amounts made from the account.

The self directed IRA accounts were closed by the custodian and the IRA owners were responsible for the taxes due from the 1099-R as well as accuracy related penalties. Eventually the un-claimed 1099-R went into collections with the IRS and the IRS sought payment of the additional taxes owed. The taxpayers disputed the amounts owed and took the case to Tax Court. The case eventually proceeded to trial and the taxpayers both lost in separate cases because they went into the case with no documentation or evidence of collection attempts. Instead, there was only testimony from the IRA owner and from their advisor that assist them in the investments. In Berks, the Court stated, “…[the IRA owner] simply took Mr. Blazer [their friend they invested with] at his word, and they apparently never saw the need to request any documentation that would substantiate that the partnerships had failed or that the promissory notes in the IRA accounts had become worthless.” Accordingly, the Court ruled against the IRA owners and held that the investment values as reported by the custodian (the initial investment amounts) were the best representation of fair market value. As a result, the IRA owners were subject to taxes owed on the higher valuation amounts.

I handled a very similar case to this one in Tax Court myself. In my case, the case resulted in the IRS reducing the valuation of the distributed IRA down to the proper discounted fair market valuation the IRA owner was seeking. As a contrast to what the taxpayers did to document their losses in Berks and Gist (e.g., no documents or records), I have outlined the steps that should be taken to properly document a loss with your IRA custodian and/or with the IRS/Tax Court.

Documenting a Loss/Failed Investment

  1. 1Hire a Third Party to Prepare an Opinion as to Value. Your custodian, the IRS, and the Tax Court all want to see an independent person’s opinion as to the value of an investment.
  2. 2Provide Accounting Records Showing Losses and No Profits/Income. In my Tax Court case on the same issue (obviously different facts and investments), we were able to re-construct the accounting records and losses from the company that demonstrated the significant valuation change. These accounting records we assembled were accompanied by financial records and third party documents which supported our numbers. The IRS agreed with our decreased valuation before trial, and dismissed their case against our client.
  3. 3Document Fraud. If fraud was involved by persons receiving the income. Was a lawsuit filed? Were complaints made to regulatory bodies (e.g. SEC or state divisions of securities)? Provide those documents to your custodian.
  4. 4If the Investment Losses are from a Un-Collectible Promissory Note.
    1. Engage a lawyer or collection agency to make collection efforts. Keep documents of their collection efforts.
    2. If the borrower filed bankruptcy, provide the bankruptcy documentation.
    3. If the loan is totally un-collectible, Issue a 1099-C (Forgiveness of Debt Income to the Defaulted Borrower, you’ll need the borrower’s SSN/EIN for this).

KEY TAKEAWAY

The best way to document an investment loss is to provide a third party valuation to your custodian.  A custodian cannot accept an e-mail or letter from the IRA owner saying the investments didn’t pan out. If a third party opinion as to value cannot be produced, you’ll need to provide some of the records and documents I outlined above to demonstrate the loss. Remember, as Tom Cruise said in A Few Good Men, “It doesn’t matter what happened. It only matters what I can prove.” To prove an investment loss in your IRA, you’ll need documents and records showing what went wrong.

THE SELF-DIRECTED IRA HANDBOOK

Mat’s best-selling guide to the rules: prohibited transactions, UBIT, IRA/LLCs, and the mistakes to avoid.

Get the Free Handbook

Prefer to talk it through? Book a call with a Directed IRA specialist