Avoiding the 20% Withholding Tax on 401(k) Distributions

Distributions from a 401(k) to its owner are subject to a 20% withholding tax whereas distributions from an IRA are not subject to a withholding tax. As a result, any amounts distributed from a 401(k) to its owner will be reduced by 20% and that 20% will be sent to the IRS in expectation of the taxes that will be due from the account owner for the distribution. Any amounts distributed from an IRA, however, are not subject to the 20% withholding as the IRA owner can elect out of withholding. The discrepancy in the rules is one advantage of using an IRA in retirement as opposed to a 401(k) since the amounts distributed from the IRA can be received in their entirety.

Keep in mind, the tax owed on a distribution from an IRA or 401(k) is the exact same. The difference is when you are required to pay it. In both instances you will receive a 1099-R from your custodian/administrator but in the 401(k) distribution you are required to set aside and effectively pre-pay the taxes owed.

Infographic: how rolling 401(k) funds to an IRA before taking a distribution avoids mandatory 401(k) withholding

The 401(k) Withholding Rule in Practice

EXAMPLE

Let’s walk through a common situation that outlines the issue. Sarah is 64 and has a 401(k). She would like to distribute $100,000 from the 401(k). She contacts her 401(k) administrator and is told that on a $100,000 distribution they will send her $80,000 and that $20,000 will be sent to the IRS for her to cover the 20% withholding requirement.

Since this 20% withholding requirement does not apply to IRAs, Sarah decides to roll/transfer the $100,000 from her 401(k) directly to an IRA. Once the funds arrive at the IRA, Sarah takes the $100,000 distribution from the IRA and there is no mandatory 20% withholding so she actually receives $100,000 in total.

Keep in mind, Sarah will still owe taxes on the $100,000 distribution from the IRA and she will receive a 1099-R to include on her tax return. That being said, Sarah has given herself the ability to access all of the amounts distributed for her retirement account without the need for sending withholding to the IRS at the time of distribution.

$80,000

What Sarah would receive from the 401(k)

$100,000

What she receives from the IRA

It’s that simple. Don’t take distributions from a 401(k) and subject yourself to the 20% withholding tax when you can roll/transfer those 401(k) funds to an IRA and receive the entire distribution desired without a 20% withholding.

FREE ROLLOVER GUIDE

Learn how to move an old 401(k) or IRA into a self-directed IRA, tax-free.

Get the Free Transfers & Rollovers Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

RESOLVING TAX DISPUTES WITH THE IRS: WHAT ARE MY OPTIONS?

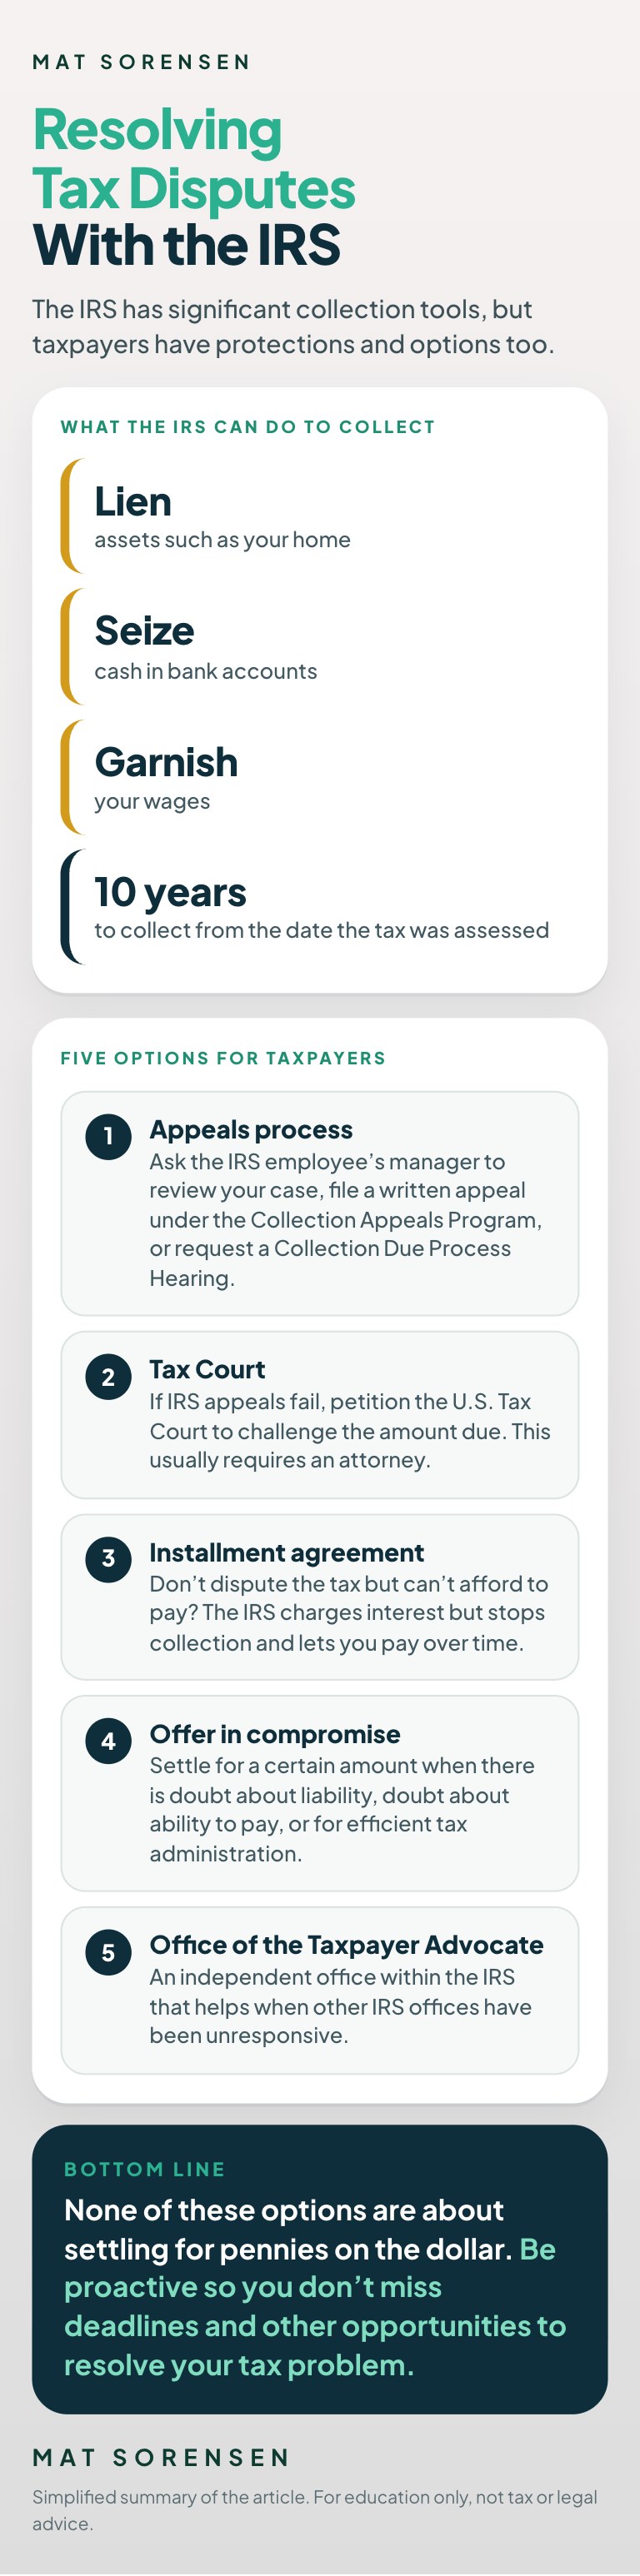
The IRS has some significant collection tools it can use to collect federal taxes. The IRS can lien assets such as your home, seize cash in bank accounts and garnish wages. Although the IRS does have these significant collection tools, there are also numerous taxpayer protections available during the tax collections process. The process of tax collection from the IRS can be long and “taxing” and the IRS has ten (10) years from the date when your tax liability was assessed to collect on the taxes. During this collection process, it is important that you are proactive in dealing with an outstanding tax liability. Below is a list of options that are available to taxpayers. I would note that none of these options revolve around settling for pennies on the dollar.

Infographic: IRS collection tools and five options taxpayers have to resolve a tax dispute

1. Appeals Process

If you disagree with the decision of an IRS employee at any time during the collection process, you may ask that employee’s manager to review your case. If you disagree with the manager’s decision, you have the right to file a written appeal under the Collection Appeals Program. You can appeal collection actions such as liens, levies of bank accounts or garnishment of wages. You are also entitled to a Collection Due Process Hearing where you can challenge the IRS’s determination of tax owed.

2. Tax Court

If you are unsuccessful in the IRS appeals process you may file a petition in the U.S. Tax Court to challenge the amount due. This appeals process is far more difficult to understand and usually requires the assistance of an attorney.

3. Installment Agreement

If you have tax owed which you do not dispute but cannot afford to pay you may set up an installment agreement with the IRS to re-pay the tax owed. Under an installment agreement the IRS does charge interest on the amount owed but will cease collection activity and will allow you to pay the tax over time. If you owe $50,000 or less then you don’t have to complete an extensive financial statement and the process can be done on-line or by phone with the IRS. If, however, you owe over $50,000, then you must complete IRS form 9465, and the IRS may also ask for a financial statement (Form 433-F) that outlines your assets, income, and debts.

4. Offer in Compromise

You may make a deal with the IRS under what is called an offer-in-compromise. Under an Offer in Compromise you agree to pay a certain amount to the IRS as a settlement for all amounts they have assessed as due. There are three grounds under which the IRS will accept an Offer in Compromise.

  • ✓First, if there is a doubt as to whether you are truly liable for the tax.
  • ✓Second, if there is doubt as to whether you are actually able to pay the IRS back.
  • ✓Lastly, an offer may be accepted if the offer promotes efficient tax administration due to an economic hardship or special circumstance of the taxpayer.

5. Office of Taxpayer Advocate

At any time in the collection process where the IRS office has been unresponsive to taxpayer requests, a taxpayer may receive the assistance of the Office of The Taxpayer Advocate. The Taxpayer Advocate is an independent office within the IRS but it is their responsibility to assist the taxpayer in dealing with other offices within the IRS. Only the IRS would have such an office. The Taxpayer Advocate can help give you advice on how to resolve your tax problem. We have used the Office of the Taxpayer Advocate in many instances and while they are within the IRS office they can be helpful in getting responses to requests for information and in obtaining decisions on Offer in Compromises and Appeals.

Be Proactive in Your Case

Many CPAs and Attorneys are familiar with tax collection and it is crucial that a taxpayer facing collection actions be aware of the procedural options available to them. We have helped numerous clients in our office resolve difficult tax situations by using some of the procedures above. The key is to be proactive in your case to ensure that you don’t miss deadlines and other opportunities to resolve your tax problem.

By: Mathew Sorensen, Attorney and Author of The Self Directed IRA Handbook