Same business, same $100,000 income, wildly different retirement outcomes: one owner saves $25,000 in a SEP IRA, the other $49,500 in a Solo 401(k)—nearly double, with nothing changed but the account type. The difference isn’t performance; it’s plan design. The Solo 401(k) is engineered for today’s self-employed, while the SEP IRA remains a 1978-era solution with modern limitations. For self-employed professionals running their business through an S corporation—as most profitable ones should—the contribution gap between a Solo 401(k) and a SEP IRA widens even further.
The real question isn’t “Which account is better?” but “Which account is better for me, given my income, age, entity type, and contribution rules?” The answer is arithmetic, not which form is simpler. In this article, we’ll break down three reasons the Solo 401(k) wins for most business owners, plus the one common scenario where a SEP IRA still makes sense. We’ll also show what $50,000 a year can grow into in each account—and why, despite sharing a $72,000 annual cap, the Solo 401(k) reaches it with nearly $100,000 less in W-2 compensation.
Why the Solo 401(k) Wins: You Can Contribute More on Less Income
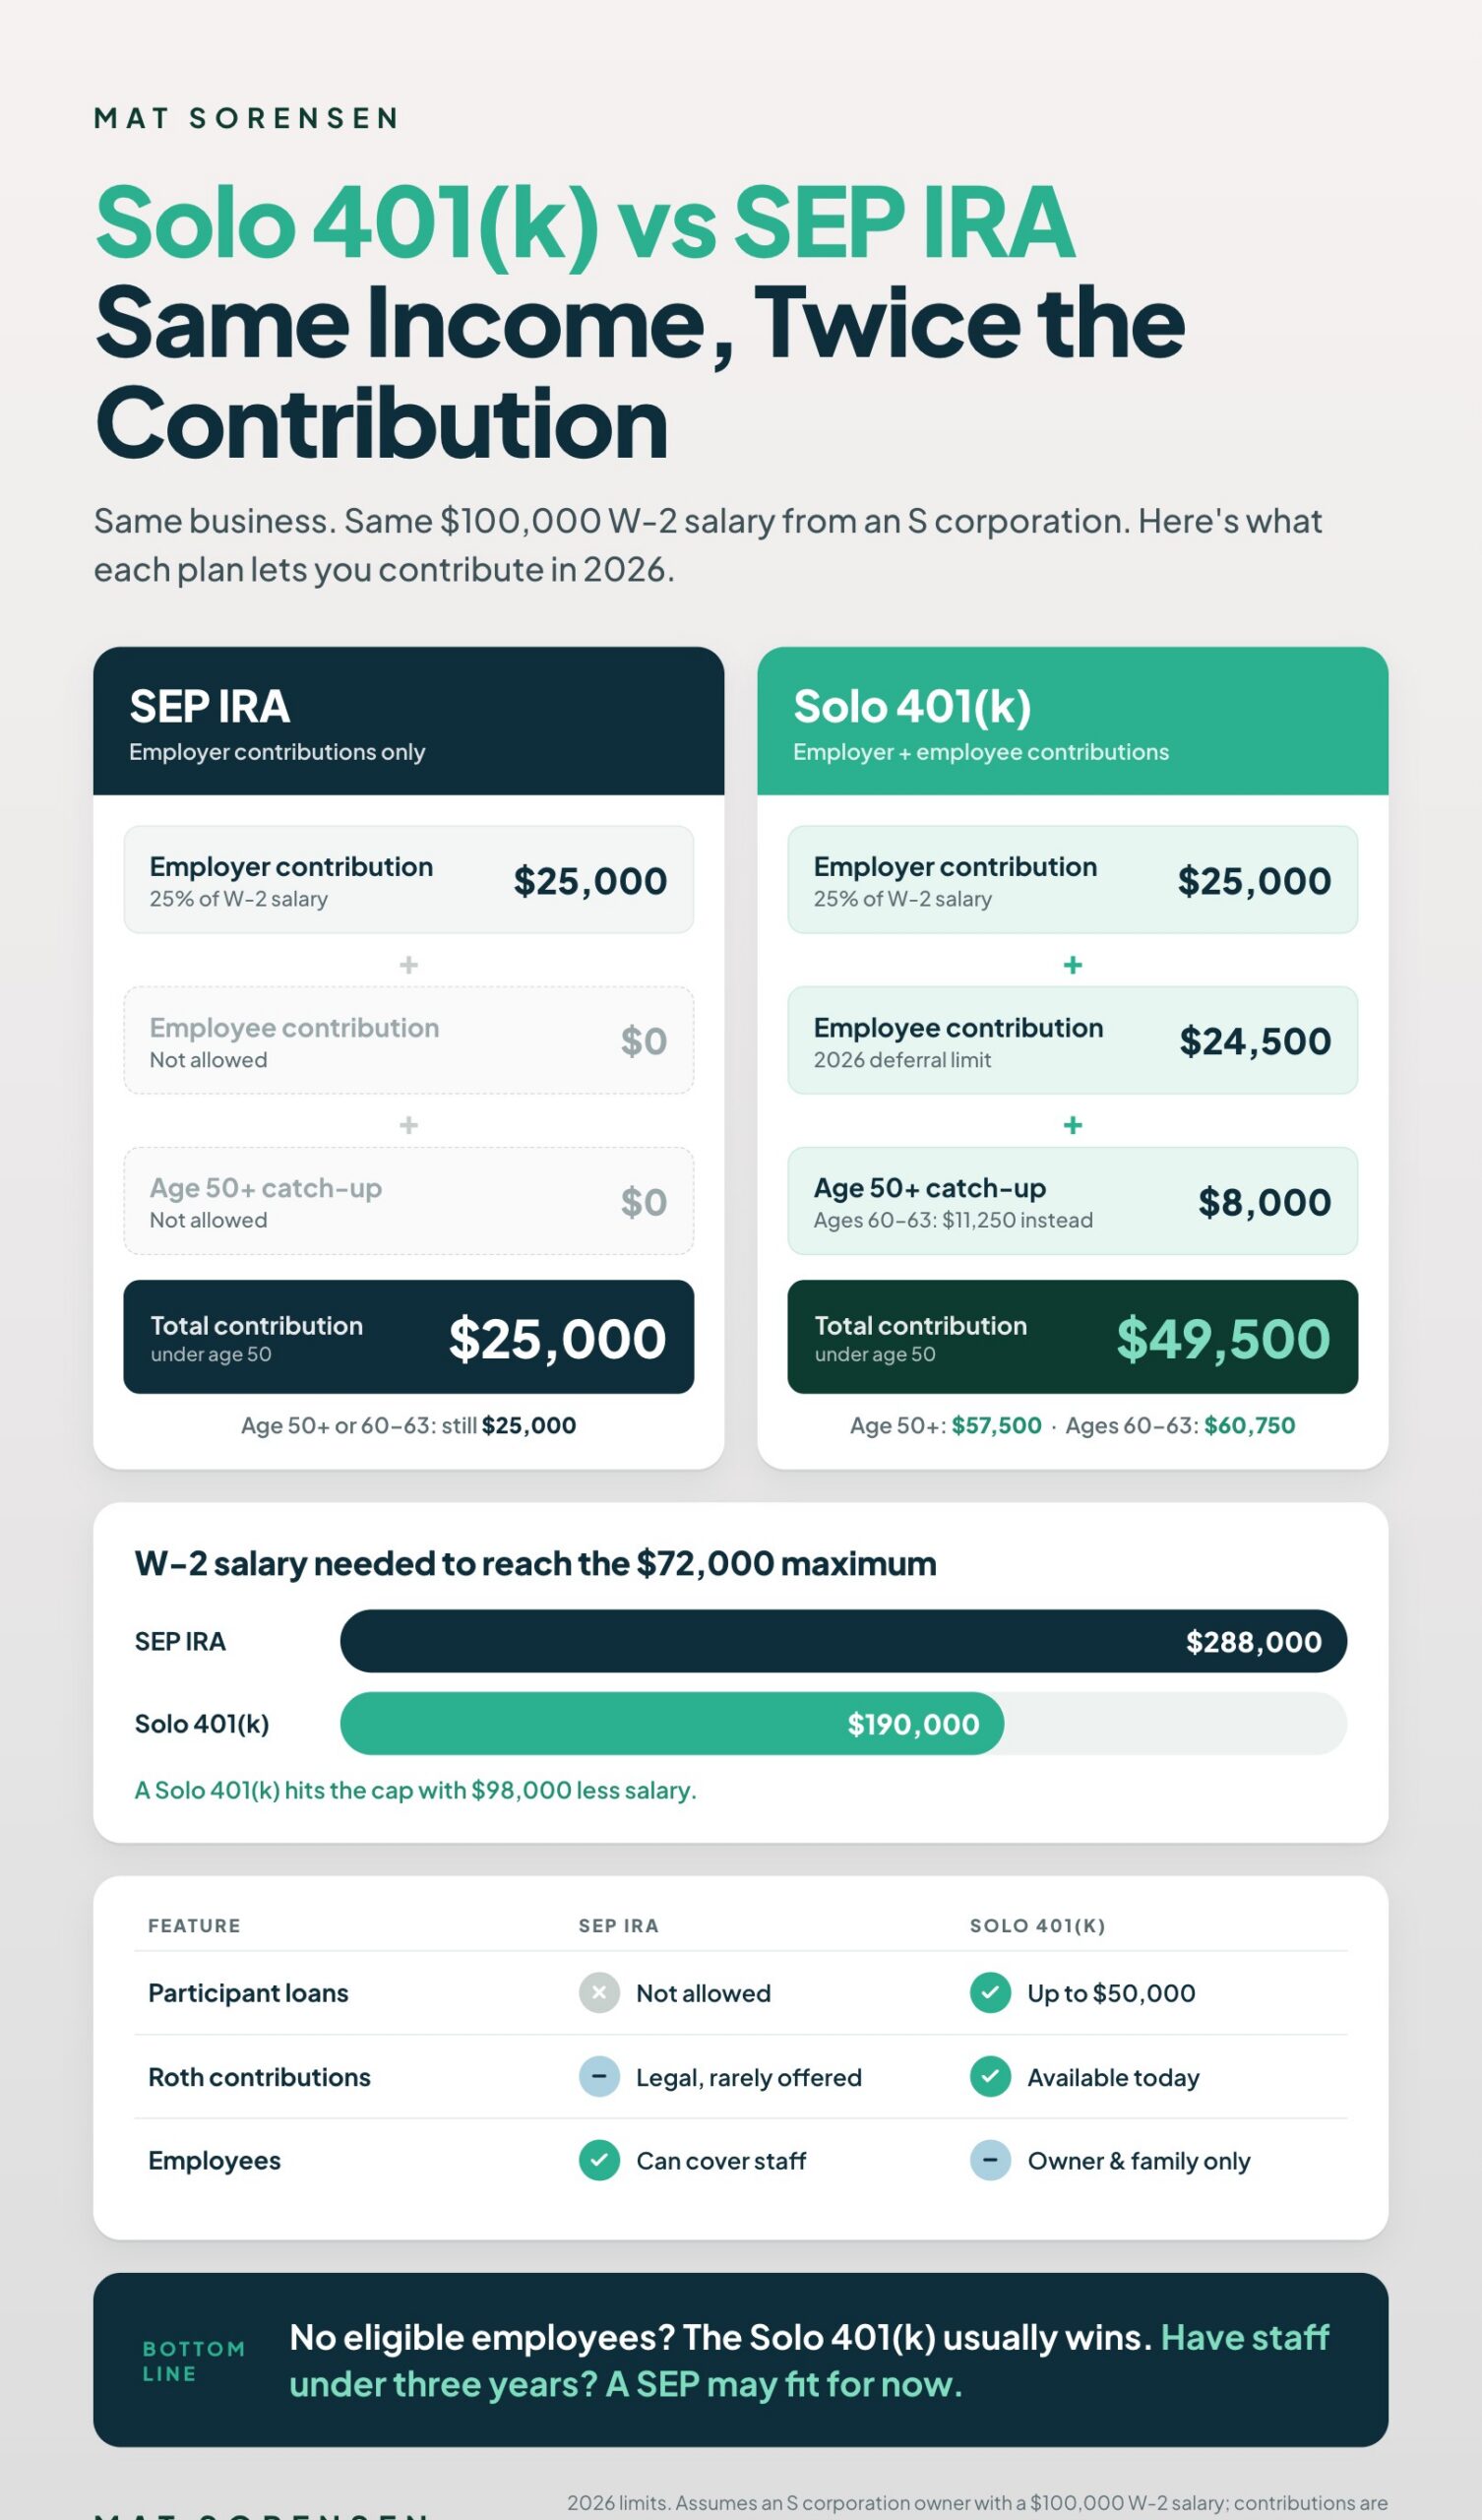
The Solo 401(k) lets you contribute significantly more than a SEP IRA at the same income level—thanks to its dual-contribution structure.
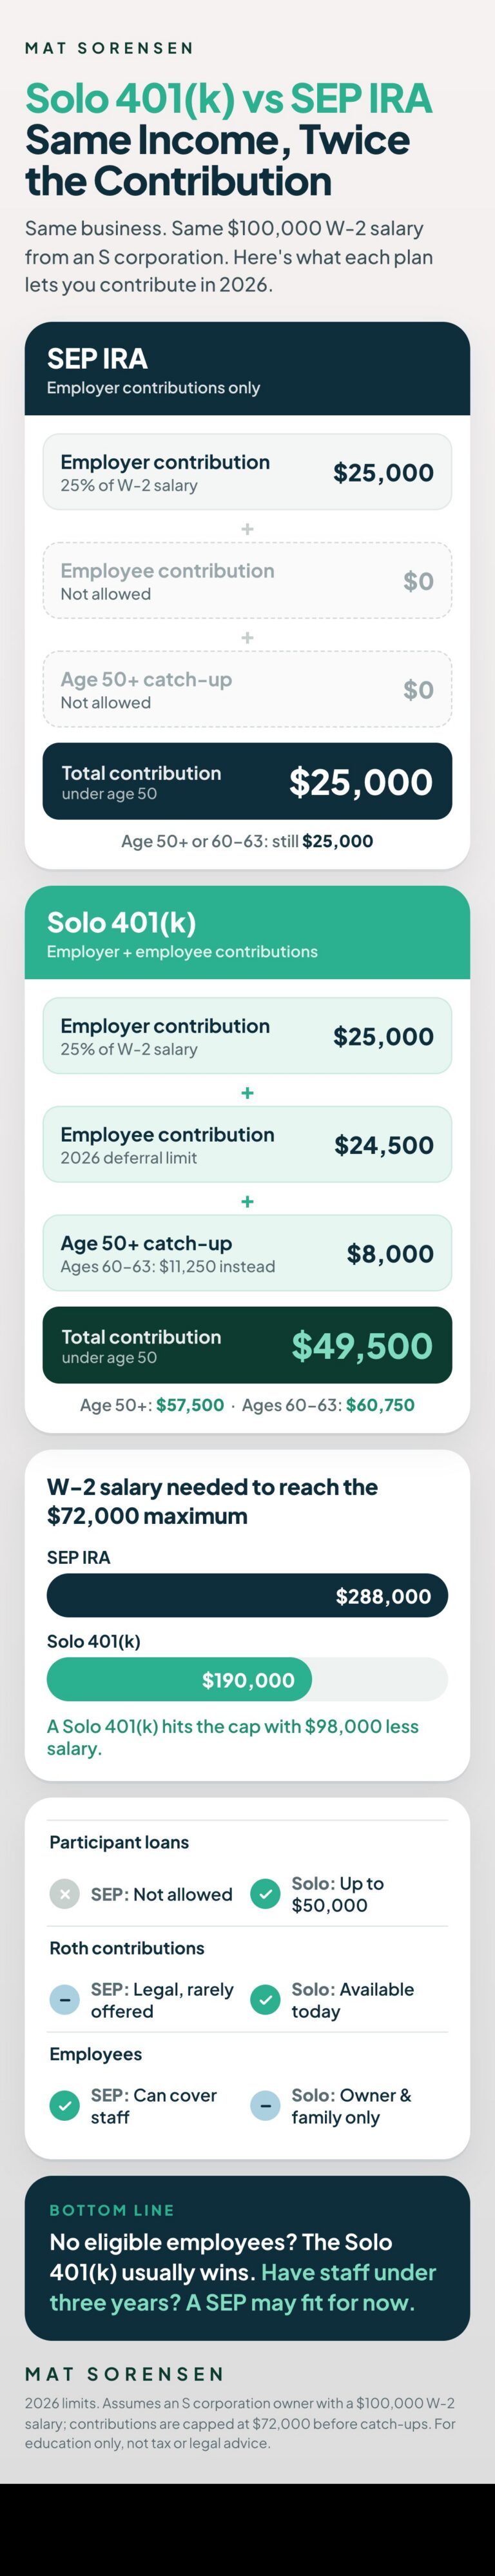
Both plans share a $72,000 annual limit (2026), but the paths to that cap differ sharply:
- SEP IRA: Only employer contributions are allowed—capped at 25% of W-2 wages for an S corporation owner, or roughly 20% of net self-employment earnings for a sole proprietor.
- Solo 401(k): An employer contribution (25% of W-2) plus an employee contribution of up to $24,500 in 2026, with catch-up contributions on top for owners 50 and older.
S corporation owners benefit most. Since contributions are based solely on W-2 wages (not K-1 distributions), minimizing W-2 to save on payroll taxes severely limits SEP IRA contributions—but barely dents Solo 401(k) capacity.
Both the SEP IRA and Solo 401(k) top out at $72,000—but you reach that limit far sooner, and with significantly less income, using a Solo 401(k).
The $50,000 Escape Hatch (Participant Loan)
The Solo 401(k) has a major advantage over the SEP IRA: it can allow participant loans. In practical terms, you may borrow from your own account—up to $50,000—without triggering income tax or an early-withdrawal penalty. SEP IRAs do not offer this flexibility. Borrowing from a SEP IRA is prohibited and can create serious tax consequences.
A Solo 401(k) loan can provide liquidity when you need it most. You can use the proceeds to pay off high-interest debt, cover medical expenses, help fund a child’s education, make a home down payment, start a business, or meet another personal need. No hardship exception or special purpose is required.
The maximum loan is the lesser of $50,000 or 50% of your vested Solo 401(k) balance. For example, if your account balance is $60,000, the maximum available loan is $30,000—not $50,000. The loan must generally be repaid within five years, with payments made at a reasonable interest rate—often prime plus 2%. If prime is 5.25%, for example, the loan rate would be 7.25%. That interest is paid back into your own retirement account.
This structure gives business owners an important safety valve: you can maximize retirement contributions while retaining access to capital if an unexpected need arises. With a SEP IRA, accessing funds before age 59½ generally means a taxable distribution and potentially a 10% early-withdrawal penalty. A properly administered Solo 401(k) loan avoids both.
Additionally, a Solo 401(k) can also be self-directed, giving you the ability to invest beyond the standard menu of mutual funds and index funds. Depending on plan documents and applicable rules, it may hold assets such as rental real estate, private funds, private companies, and cryptocurrency—investments you understand and believe in.
FREE BEGINNER’S GUIDE
Get a step-by-step overview of Solo 401(k) contribution rules, setup, deadlines, loans, and self-directed investing.
The Roth Option
The third major advantage of a Solo 401(k) is Roth capability. If your plan document permits it, you can make Roth Solo 401(k) contributions today, pay tax on the money now, and potentially withdraw the contributions and decades of investment growth tax-free in retirement.
A SEP IRA is a different story. In legislation known as SECURE 2.0, Congress made Roth SEP contributions legal, and the IRS now recognizes that SEP contributions may be made to Roth SEP IRAs. But availability remains limited in practice because the IRS has yet to release updated model form documents for Roth SEP IRAs. Many custodians, including Directed IRA, are waiting for those model documents before establishing customers’ Roth SEP IRAs.
Roth contributions do not produce an upfront tax deduction. You pay tax on the income before contributing it to the Roth Solo 401(k). In exchange, qualified distributions in retirement, generally after age 59½, can be entirely tax-free.
That trade-off can be compelling for investors who expect their tax rate to be higher later, value certainty around future taxes, or are focused on long-term compounding. Rather than taking a deduction today and paying taxes when funds come out, you pay tax once on the contribution and allow the account to grow without another tax bill at retirement.
Key takeaway: For Roth-focused savers, this feature alone can make the Solo 401(k) the more practical choice. A Roth SEP may be authorized by law, but a Roth Solo 401(k) is generally the account you can actually establish and use today.
The One Exception: When the SEP Actually Wins
There is one common situation where a SEP IRA may be more practical than a Solo 401(k): you have employees.
A Solo 401(k)—also known as a one-participant 401(k)—is designed for a business owner with no eligible non-owner employees. It can generally cover the owner, the owner’s spouse, and children who work in the business; each may participate under the plan’s eligibility rules and have their own Solo 401(k) account within the same plan. However, once you have an eligible non-owner full-time employee who has worked for you for more than one year, the business is no longer a straightforward fit for a Solo 401(k).
SECURE 2.0 adds another consideration: certain long-term, part-time employees must be allowed to make elective deferrals after working at least 500 hours in two consecutive 12-month periods, subject to the applicable age and plan rules. That means part-time help can create 401(k) eligibility issues sooner than many owners expect.
The Solo 401(k) is meant for the business owner, their spouse, and their family. It is not intended for a company that has other full-time or part-time employees.
A SEP IRA offers more runway. Under the maximum permitted eligibility requirements, employees generally must be included only after they have:
- 1Reached age 21
- 2Worked for the business in at least three of the prior five years
- 3Earned at least the applicable minimum compensation for the year
Importantly, a “year of service” can count even if the employee worked only briefly. A seasonal employee who works one summer can still accumulate one of the three required years.
EXAMPLE: THE SEP WINDOW
Suppose you are a real estate agent who hires a full-time assistant. After two years, a Solo 401(k) is no longer the straightforward solution because you have a non-owner employee. But that employee may not yet be eligible for a SEP IRA under the three-out-of-five-years rule.
That creates a useful planning window: you can establish a SEP IRA, make your annual employer contribution, and delay the point at which you must also fund contributions for the employee. Once the employee satisfies the SEP’s eligibility requirements, however, the business must generally make the same percentage contribution for that employee as it makes for the owner.
The practical takeaway: If you have no eligible employees—only independent contractors paid on Form 1099—a Solo 401(k) is usually the stronger choice. If you have employees and are in the gap between one and three years of service, a SEP IRA can be the better short-term retirement-plan option.
What That $50,000 a Year Actually Becomes
The contribution gap between a SEP IRA and a Solo 401(k) may look like a $24,500 annual difference. Over time, it can become a multimillion-dollar decision.
Assume you contribute $50,000 per year to a Solo 401(k) and earn a hypothetical 10% annual return. That is roughly in line with the S&P 500’s long-term historical average, though actual returns vary and are never guaranteed.
If those contributions go into a Roth Solo 401(k), qualified distributions in retirement can be entirely tax-free. That means the value shown after 10, 20, or 30 years is not merely an account balance—it can be tax-free retirement income.
This is why the account decision matters. A Solo 401(k) does not simply give you more room to contribute this year; it gives more capital time to compound. For an owner able to put away $50,000 annually—even on a $100,000 W-2—the difference between a SEP IRA and a Solo 401(k) can grow from thousands of dollars today to millions of dollars by retirement.
What This All Comes Down To
The SEP IRA was built for an earlier era of self-employment. For most business owners with no eligible employees, the Solo 401(k) is the more powerful modern tool: it lets you contribute more on less income, access liquidity through a participant loan when needed, and use a practical Roth option to build tax-free retirement wealth.
The advantage is not subtle. A Solo 401(k) combines higher contribution capacity, greater flexibility, and Roth planning in one account. Yet many business owners never compare the numbers—they simply open whichever account their bank or broker makes easiest to access. That can mean leaving substantial retirement savings and tax-planning opportunities on the table.
Ready to explore a Solo 401(k) or self-directed IRA? My team at Directed IRA administers thousands of self-directed retirement accounts and can help you evaluate your options. Book a complimentary 15-minute call to get started and discuss which options may be best for you.
FREE 15-MINUTE CALL
Find out whether a Solo 401(k) or SEP IRA fits your income, entity, and employees.