Avoiding State Income Tax on Retirement Plan Distributions

When a retiree begins taking distributions from a traditional IRA, 401(k), or pension plan, those distributions are taxable to the retiree under federal income tax and any applicable state income tax rules. While federal taxation cannot be avoided, state taxation may be avoided depending on your state of residency. In general, there are some states that have zero income tax and therefore don’t tax retirement plan distributions, some states that have special exemptions for retirement plan distributions, and other states that do in fact tax retirement plan distributions. This article breaks down the basics and discusses some of the states where income taxes can be avoided.
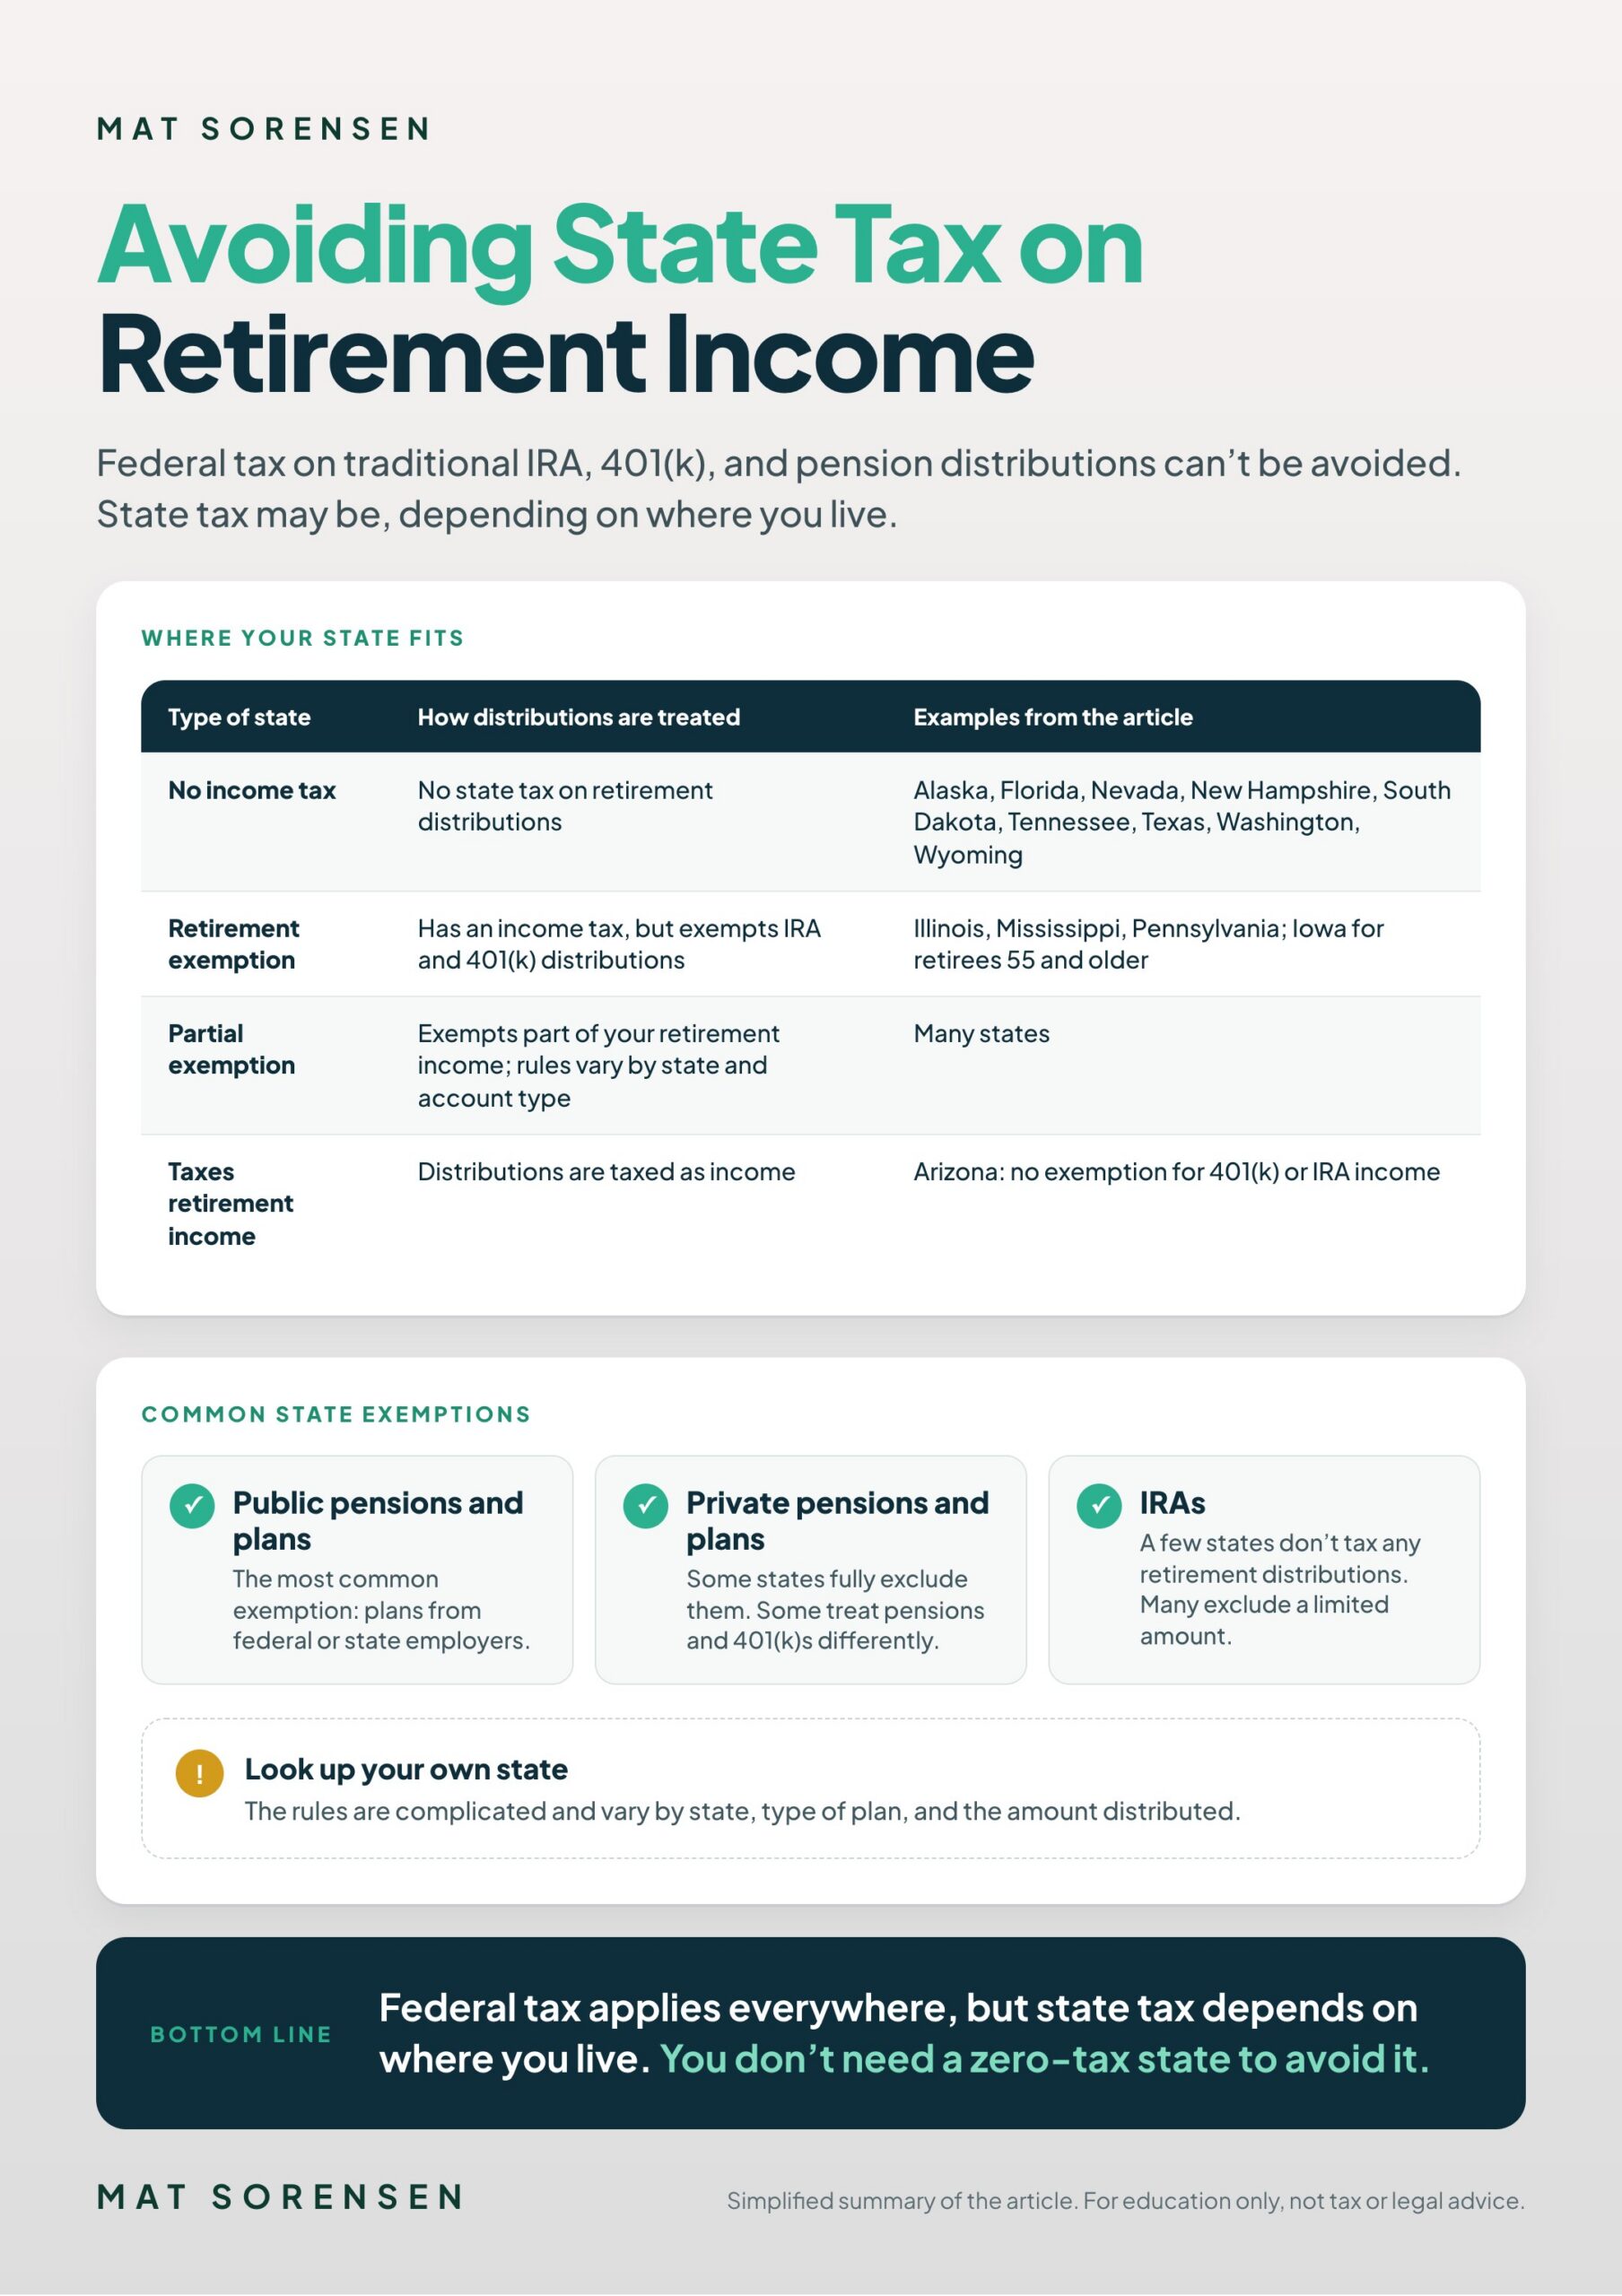
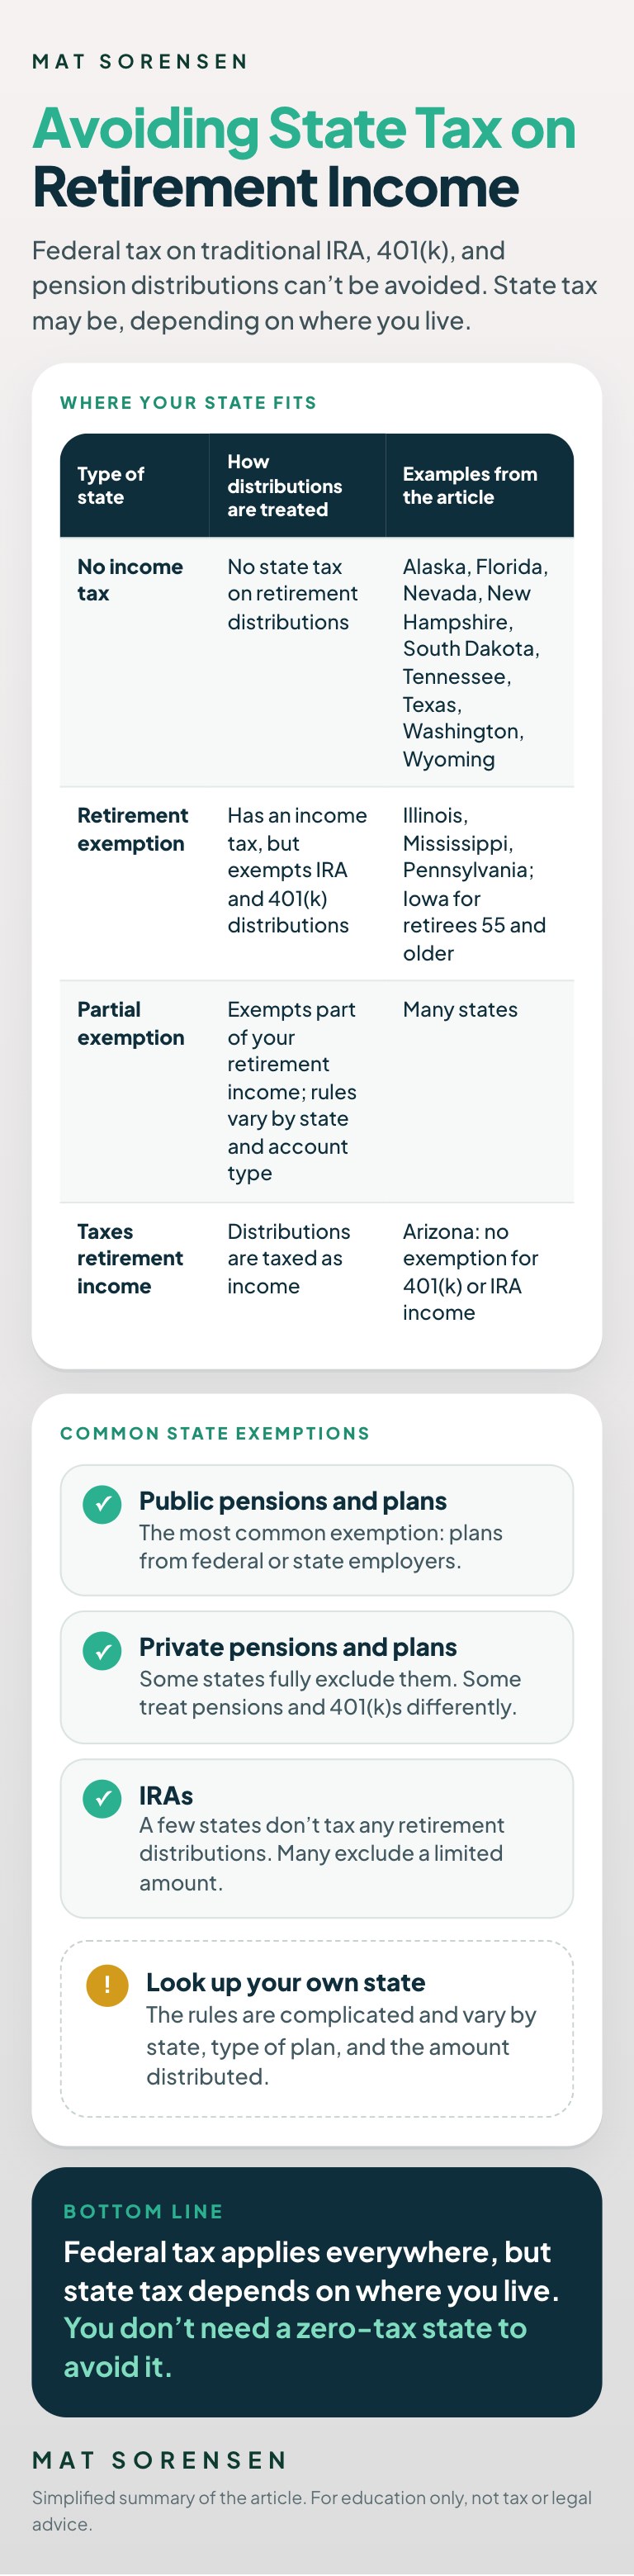
Infographic: how no-income-tax states, retirement exemption states, and taxing states treat IRA, 401(k), and pension distributions, plus common state exemptions

The No State Income Tax States

First, the easiest way to avoid state income tax on retirement plan distributions is to establish residency in a state that has no state income tax. It isn’t just the fun and sun of Florida that helps attract all of those retirees. It’s the tax-free state treatment of all that money stocked away in your retirement account. As of 2026, nine states have no income tax on wages or retirement distributions: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming.

States with Retirement Income Exclusions

Second, some states have an income tax but exempt retirement plan distributions. In 2026, Illinois, Mississippi, and Pennsylvania exempt IRA and 401(k) distributions, and Iowa exempts them for retirees 55 and older. Many other states exempt part of your retirement income, and the rules vary by state and by type of account. Here’s a quick summary of the common exemptions found in the states.

  1. 1For Public Pensions and Retirement Plans. Distributions from federal or state employer plans are exempt from taxation in many states. This is the most common exemption amongst states that have an income tax but who exempt some types of retirement plan distributions from income. Most of the states that have an exemption for retirement plan income provide an exemption for public employee pensions and retirement plans.
  2. 2For Private Pensions and Retirement Plans. Some states offer a full exclusion for private pensions and retirement plans. Some of them differ between pension and contributory plans (e.g. 401(k)) and some of them make no distinction. Pennsylvania, for example, excludes all income distributions. Hawaii excludes certain distributions from state income tax for private retirement plans and for portions from company plans rolled over to a rollover IRA and then distributed from the rollover IRA.
  3. 3For IRAs. There are some states that do not tax any retirement plan distributions, including IRA distributions to retirees. Illinois for example does not tax distributions from retirement plans at all (pensions, IRAs, 401(k)s). There are also numerous states that exclude a certain limit of retirement plan income from taxation.

Know Your State’s Rules

In sum, the state tax rules for retirement plan distributions are complicated and vary significantly. Each state can be understood rather quickly though and everyone planning for retirement should understand how state income taxes may eat into their planned retirement plan distributions.

EXAMPLE

I, for example, looked into Arizona and found that there is no exemption for 401(k) or IRA income in the state of Arizona. While we do have a low state income tax rate, Arizona state income tax includes income from private retirement plans (pensions and 401(k)s) and IRAs and has a modest deduction for distributions from public retirement plans.

Each state is unique to the type of plan, and the amounts being distributed but don’t just think you need to be in a state with zero income tax to avoid taxes on retirement plan distributions. For example, you could be in Illinois, Tennessee, or New Hampshire and could realize state income tax-free distributions of your IRA or 401(k).  The National Conference of State Legislators has an updated 2015 chart that is very useful and can be used to look up your state’s tax treatment of retirement plan distributions for retirees.

SELF-DIRECTED IRA

Invest your IRA in real estate, private companies, notes, precious metals, and more.

Open a Self-Directed IRA

When Does Raising Money in an LLC, Joint Venture or Partnership Violate Securities Laws?

We’ve all heard the buzz words of crowdfunding, PPMs, and IPOs, but there are less complicated ways to raise money and start a business and one of the most reliable and most used methods is that of partnerships or joint ventures.

If you’re raising money from others in an LLC, partnership, or joint venture, you must take specific precautions in structuring your documents so that the investment of money from any member, partner, or joint venturer does not constitute a violation of federal or state securities laws. Failure to comply with the securities laws can result in civil and criminal penalties. Many real estate investments, real estate developments, and emerging companies rely on numerous strategies to raising capital that are outside of publicly traded stock and that do not require registration with a state securities division or the federal Securities and Exchange Commission. This article addresses those strategies and outlines some of the key issues to consider when raising funds through an LLC, partnership, or joint venture arrangement. This article addresses the legal considerations that should be analyzed when bringing in “cash partners” or “investors” into your LLC, partnership, or joint venture.

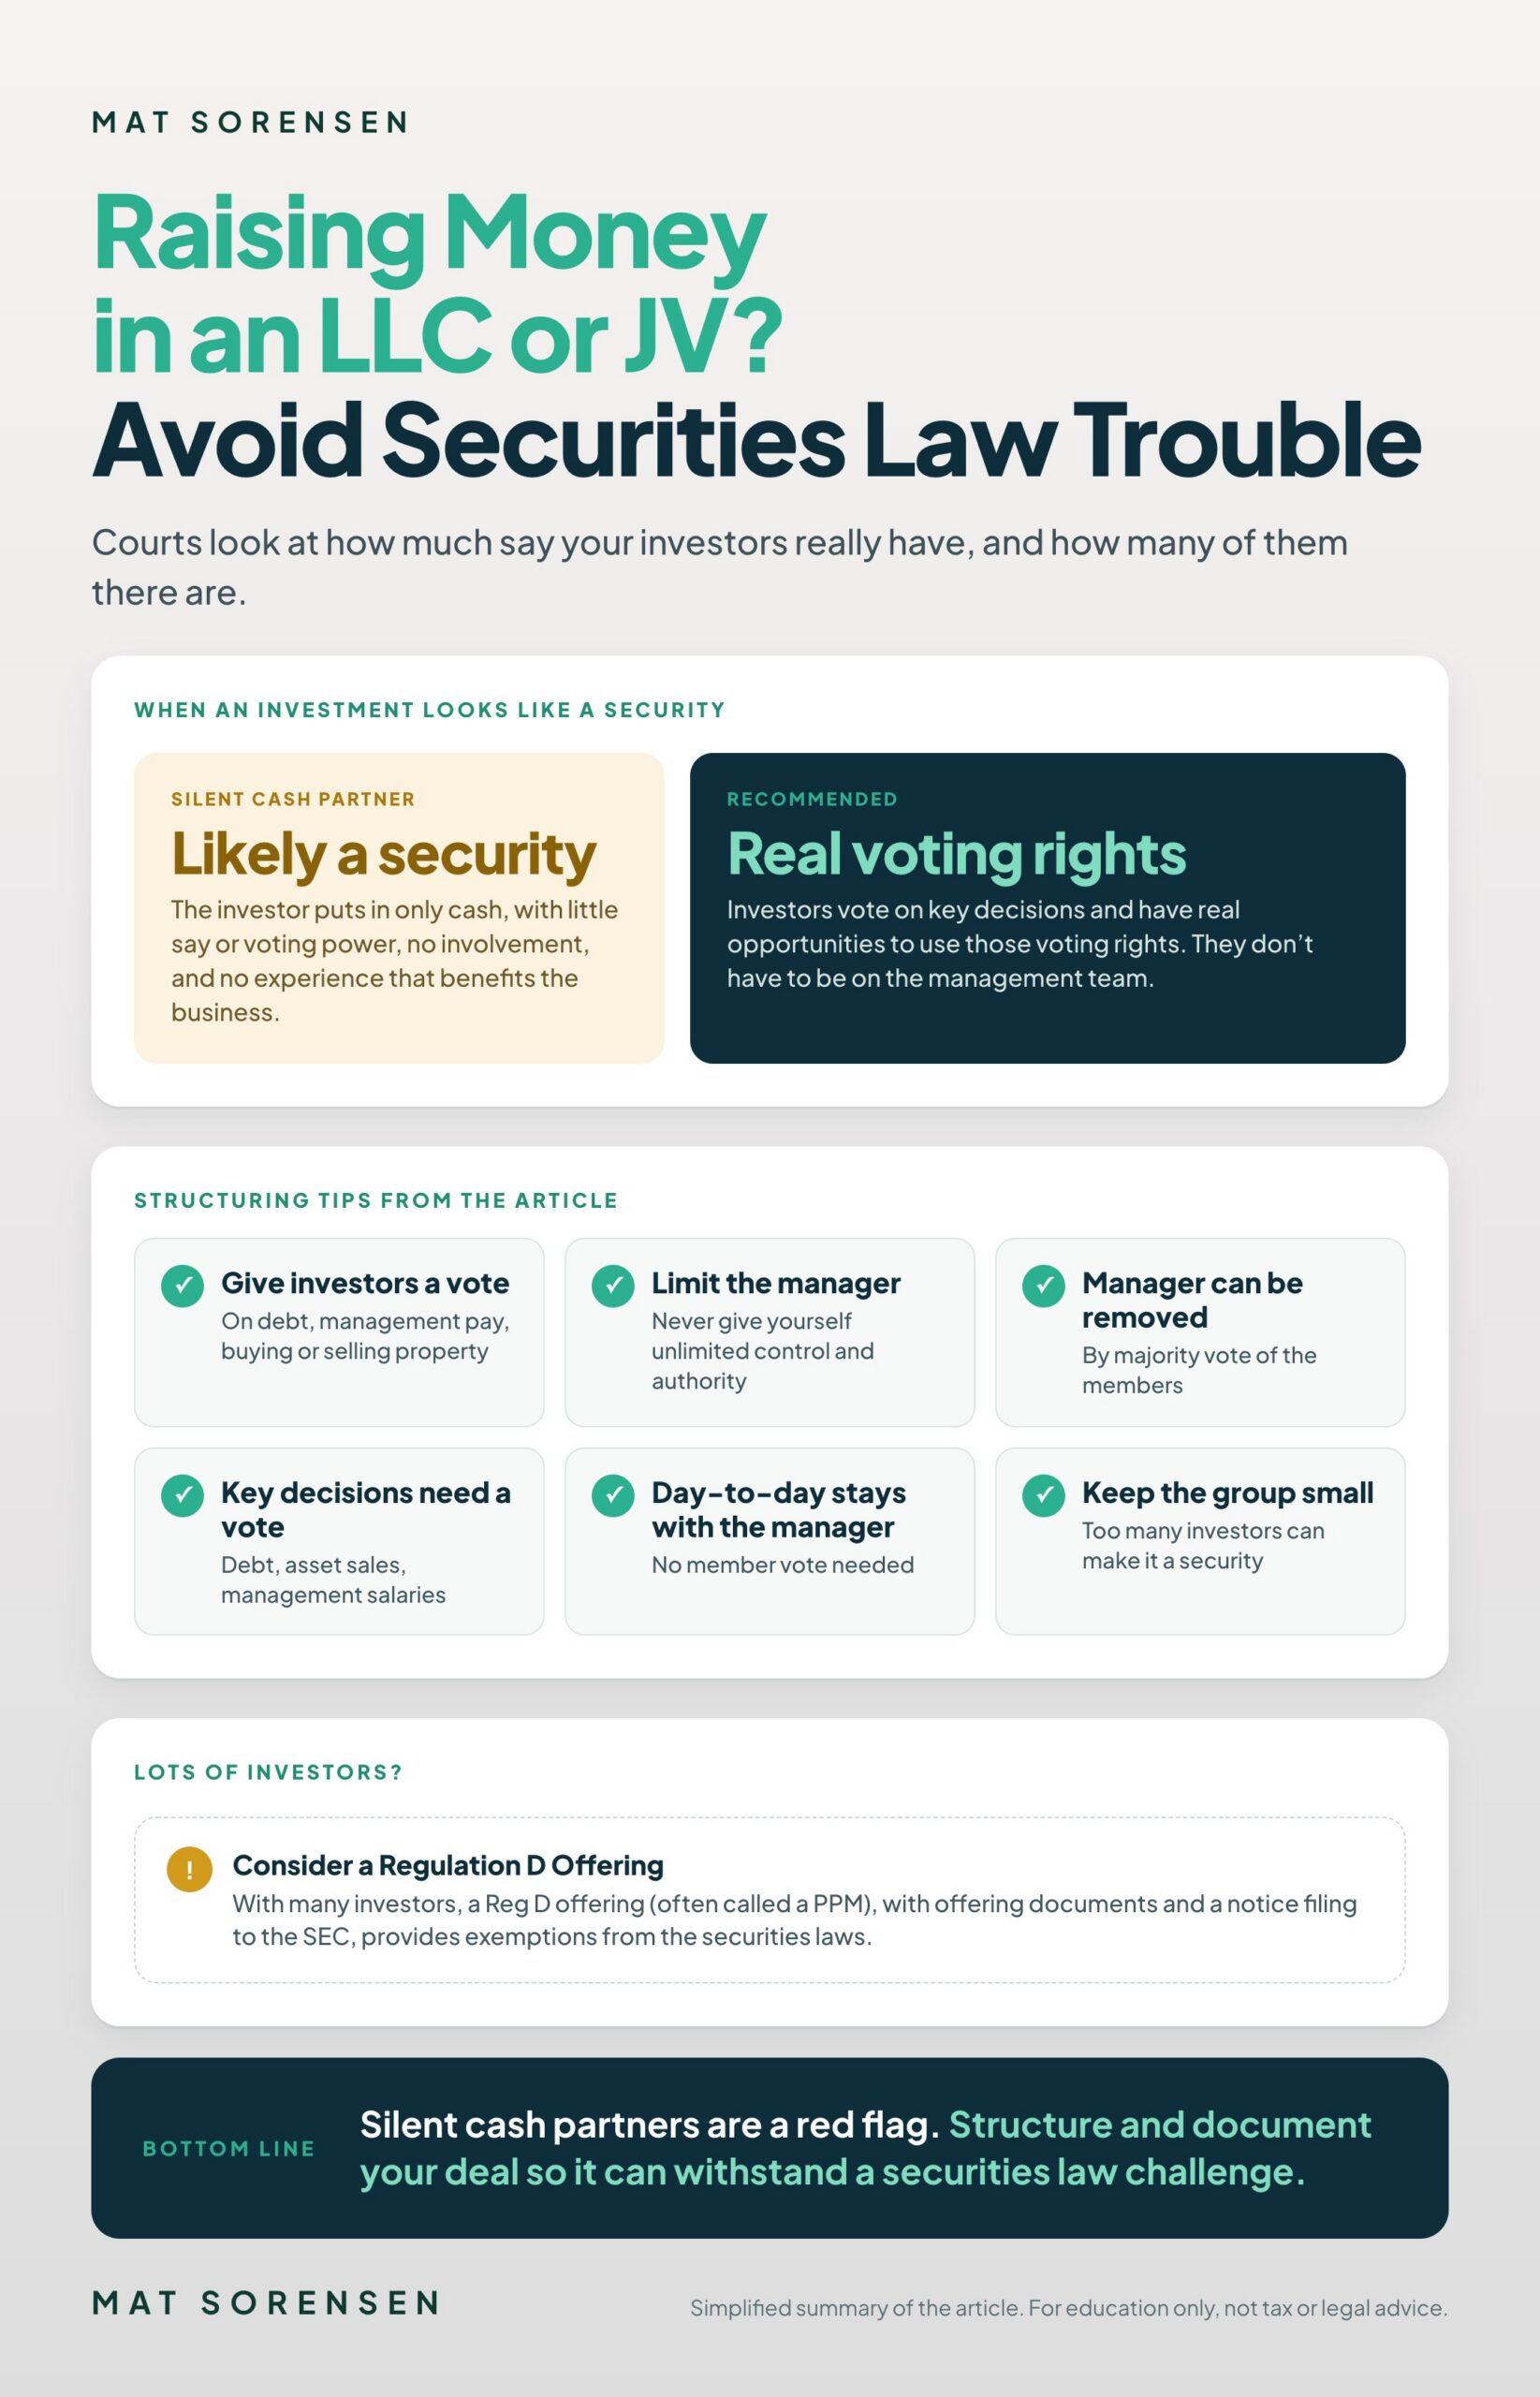
Infographic: when an LLC, joint venture, or partnership investment looks like a security, and structuring tips to avoid securities law violations

Is the LLC Member, Partner or Joint Venturer Contributing More Than Just Money?

The courts have widely held that an investment in an LLC, joint venture, or partnership is a security when the investor is investing solely cash and has no involvement, vote, or say in the investment. In these instances where the investor just puts in cash (sometimes called “silent cash partner” arrangements), the investment will likely be deemed a security. In a famous securities law case called Williamson, the Fifth Circuit Court of Appeals held that a joint venture contract investment is a security if the investor has little say or voting power, no involvement in the business or investment, and no experience that would provide any benefit to the business or investment. Williamson, 645 F.2d 424. As a result, to avoid triggering these factors and having your investment or business deemed a security we strongly recommend that all investors in Joint Venture agreements, LLCs, or partnerships have voting rights and that they participate in the key decision-making functions of the investment or business. Investors do not have to be part of the management team but they do need to have voting rights and need to have real opportunities to use those voting rights. For example, they could have voting rights on incurring additional debt, on management compensation, and/or on buying or selling property.

Don’t Give Yourself Unlimited Control as Manager

In most LLCs with cash partners, the person organizing the investment and running the operations is often the manager of the LLC, partnership, or joint venture and has the ability to bind the company or partnership. When making this selection as the manager, it is key that you do not give yourself unlimited control and authority. If you do give yourself unlimited control as manager, your investors may be deemed to have purchased a security since their voting rights will have been extinguished by placing too much control and power in the manager/management. What is recommended is that the members have the ability to remove the manager by majority vote and that the manager may only make key decisions (e.g. incurring debt, selling an asset, setting management salaries, etc.) upon the agreement and majority vote of the investors. While key decisions and issues should be left to the members, day to day decisions can be handled by the manager without a vote of the members/investors.

Don’t Combine Too Many People Into One LLC, JV or Partnership

The Courts have consistently held that even if an investor is given voting rights and has an opportunity to vote on company matters that the investor’s interest can be deemed a security if there are too many other investors involved in the LLC, JV, or Partnership. Holden, 978 F.2d 1120. As a general rule of advice, you should only structure investments and partnerships that include 5 or less cash investors as the securities laws and the involvement of more individuals than this could potentially cause the investment to be deemed a security. When there are more than 10 investors it is critical for clients to consider structuring the investment as a Regulation D Offering and that they complete offering documents and memorandums and make a notice filings to the SEC. Many people refer to this type of investment structure as a PPM.  When there are a lot of investors involved, a Regulation D Offering provides the person organizing the investment with exemptions from the securities laws and can allow someone to raise an unlimited amount of money from an un-limited amount of investors.

In sum, there are many factors and issues to consider when raising money from others in an LLC, JV, or partnership and it is crucial that you properly structure and document these investments so that they can withstand these challenges of securities law violations. For help in structuring your investments please contact the law firm at 602-761-9798.

Contingency Clauses in Real Estate Purchase Contracts

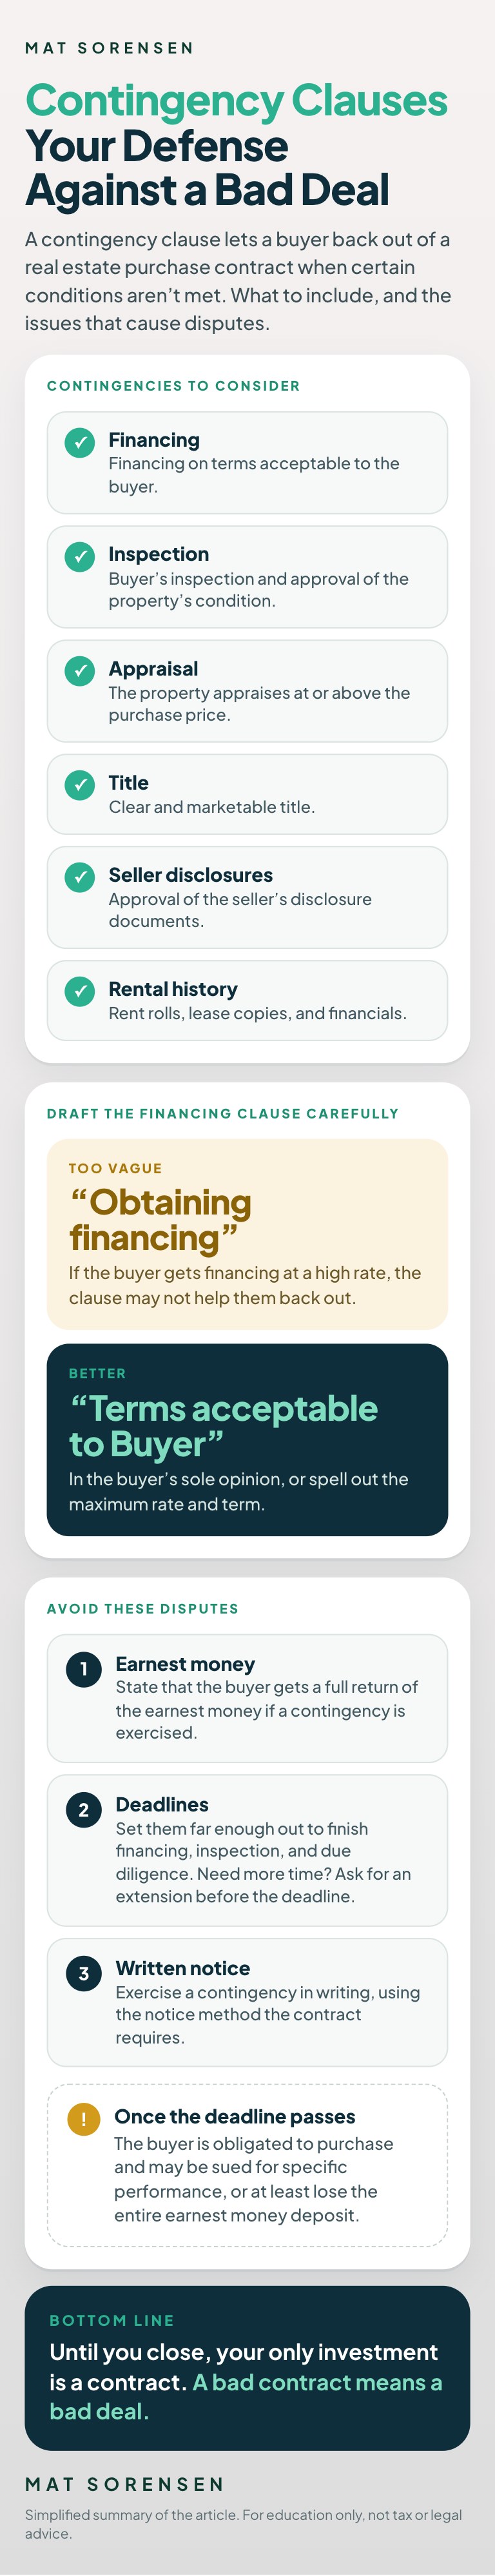
Contingency clauses are some of the most important components of a real estate purchase contract, and can provide significant protections to buyers of real estate. A contingency clause typically states that a buyer’s offer to buy property is contingent upon certain things. For example, the contingency clause may state, “The buyer’s obligation to purchase the real property is contingent upon the property appraising for a price at or above the contract purchase price.” Under this contingency, the buyer is relieved from the obligation to buy the property if the buyer obtains an appraisal that falls below the purchase price. Because contingency clauses provide the buyer a way to back-out of a contract they can be excellent tools for real estate investors who make numerous offers on properties.

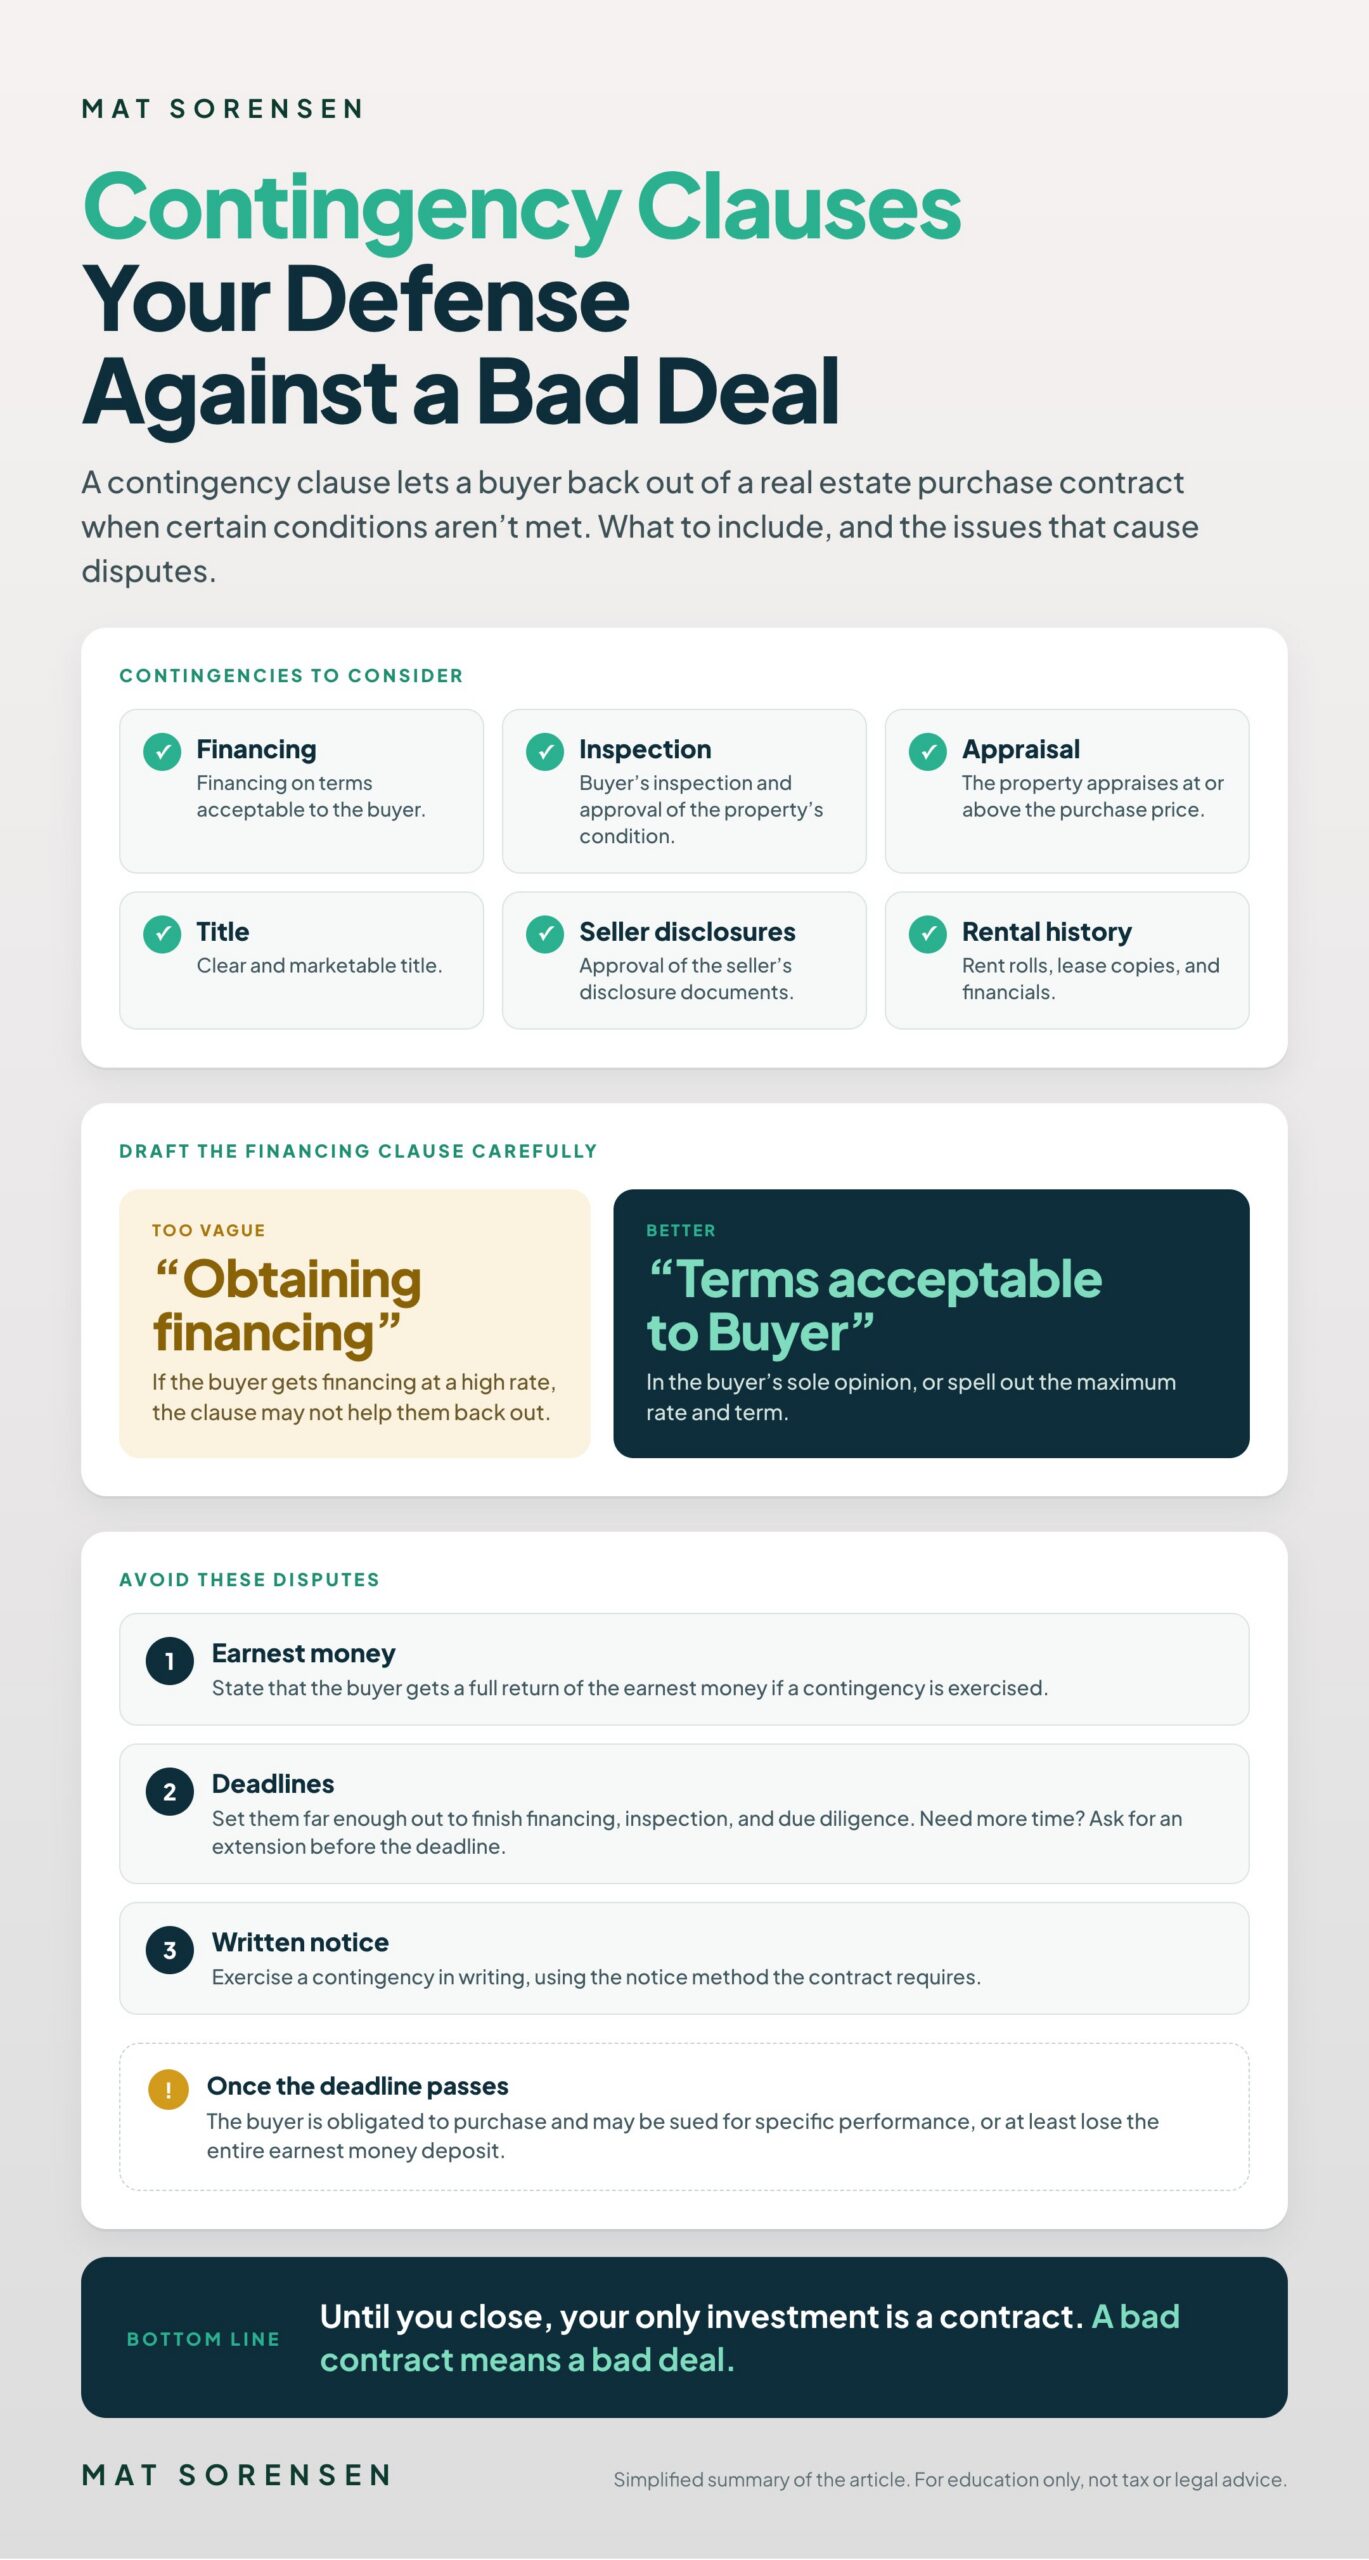
Infographic: contingency clauses to consider in a real estate purchase contract and the issues that cause disputes

Contingency Clause Examples

Here are some contingency clauses to consider in your real estate purchase contract.

1. Financing Contingency

A financing contingency clause states something like, “Buyer’s obligation to purchase the property is contingent upon Buyer obtaining financing to purchase the property on terms acceptable to Buyer in Buyer’s sole opinion.” Some financing contingency clauses are not well drafted and will provide clauses that say simply, “Buyer’s obligation to purchase the property is contingent upon the Buyer obtaining financing.” A clause such as this can cause problems as the Buyer may obtain financing under a high rate and thus may decide not to purchase the property. However, because the contingency only specified whether financing is obtained or not (and not whether the terms are acceptable to buyer), the clause can be unhelpful to a buyer deciding not to purchase the property. Some financing clauses are more specific and, for example, will say that the financing to be obtained must be at a rate of at most 7% on a 30 year term and that if the buyer does not obtain financing at a rate of 7% or lower then the buyer may exercise the contingency and back out of the contract.

2. Inspection Contingency

An inspection contingency clause states something like, “Buyer’s obligation to purchase is contingent upon Buyer’s inspection and approval of the condition of the property.” Another variation states that the Buyer may hire a home inspector to inspect the property and that the Seller must fix any issues found by the inspector and if the Seller does not fix the items specified by the inspector then the Buyer may cancel the contract. Inspection clauses are very important as they ensure that the Buyer is obtaining a valuable asset and not a money pit full of defects and repair issues.

Other important contingency clauses are clear and marketable title clauses, approval of seller disclosure documents, and rental history due diligence information (e.g., rent rolls, lease copies, financials, etc.).

Contingency Clause Issues

When using contingency clauses buyers should pay attention to a few key terms. I’ve personally seen many disputes arise as a result of one of the following issues.

1. What Happens to the Earnest Money

One important consideration that is often vague in real estate purchase contracts is what happens to the buyer’s earnest money when the buyer exercises a contingency. Does the buyer receive a full return of the earnest money? Does the seller keep the earnest money? If the contract is silent and if you as the buyer exercise a contingency, don’t count on the seller agreeing to a release of the earnest money as they are often upset that you are not going to purchase the property. Make sure the contract clearly states something like the following,

“If Buyer exercises any contingency, Buyer shall receive a full return of any earnest money deposit or payment to Seller.”

2. Contingency Deadlines

Another important contingency clause issue is the date of the contingency clause deadline. Most contingency clauses have expiration dates that occur well before closing. Those dates should typically be somewhere from 2 weeks to 2 months from the date of the contract, depending on the purchase and seller disclosure items and the type of property being purchased.

EXAMPLE

For example, single family homes will typically have a shorter window as financing and inspection can occur more quickly than would occur under a contract to purchase an apartment building.

Whatever the deadline is, make sure that the deadline is set far enough out so that you can complete your contingency tasks. You need to make sure you have enough time to obtain adequate financing commitments, to properly inspect the property, and that you have enough time to review the seller’s disclosure documents. Setting a two week deadline is sometimes done but two weeks is usually not enough time to complete financing commitments, inspection, and due diligence activities that are necessary to determine whether you are going to commit to purchasing the property.

If contingency deadlines are approaching and you need more time, then ask the seller for an extension before the deadline arrives. If the Seller refuses an extension, then exercise the contingency you need more time to satisfy.

3. Exercise Your Contingency in Writing

If you do exercise a contingency and decide to back-out of the purchase of the property, make sure you do it in writing. Don’t rely on telephone calls or even e-mails (unless the contract permits e-mails as notice). Additionally, make sure that the reason for the contingency and that the date of the contingency are put in writing and are sent to the seller in a method where the date can be tracked in accordance to the notice provisions of the contract. For example, if the contract requires a contingency to be noticed by fax or hand delivery, don’t rely on an e-mail to the seller or the seller’s agent as such communication will not invoke the contingency.

Once the deadline to exercise a contingency has passed, the buyer is obligated to purchase the real property and may be sued for specific performance (meaning they can be forced to buy) or at the least the buyer will lose their entire earnest money deposit.

Contingency clauses are the best defense mechanism to a bad deal and should always be used by real estate buyers. Keep in mind that until you close on the property, the only investment you have is a contract and if you have a bad contract, then you have a bad deal.

IRAs and the UBIT/UDFI Tax Exception for REITs

An IRA may invest into a real estate investment trust. Real estate investment trusts (“REIT”) are trusts whereby the company undertakes certain real estate activities (e.g. own or lend on real estate) and returns profits to its owners. An IRA may invest and be an owner in a REIT. As many self directed IRA investors know,  a form of unrelated business income tax (“UBIT” tax) known as unrelated debt financed income tax (“UDFI” tax) can arise from real estate leveraged by debt.

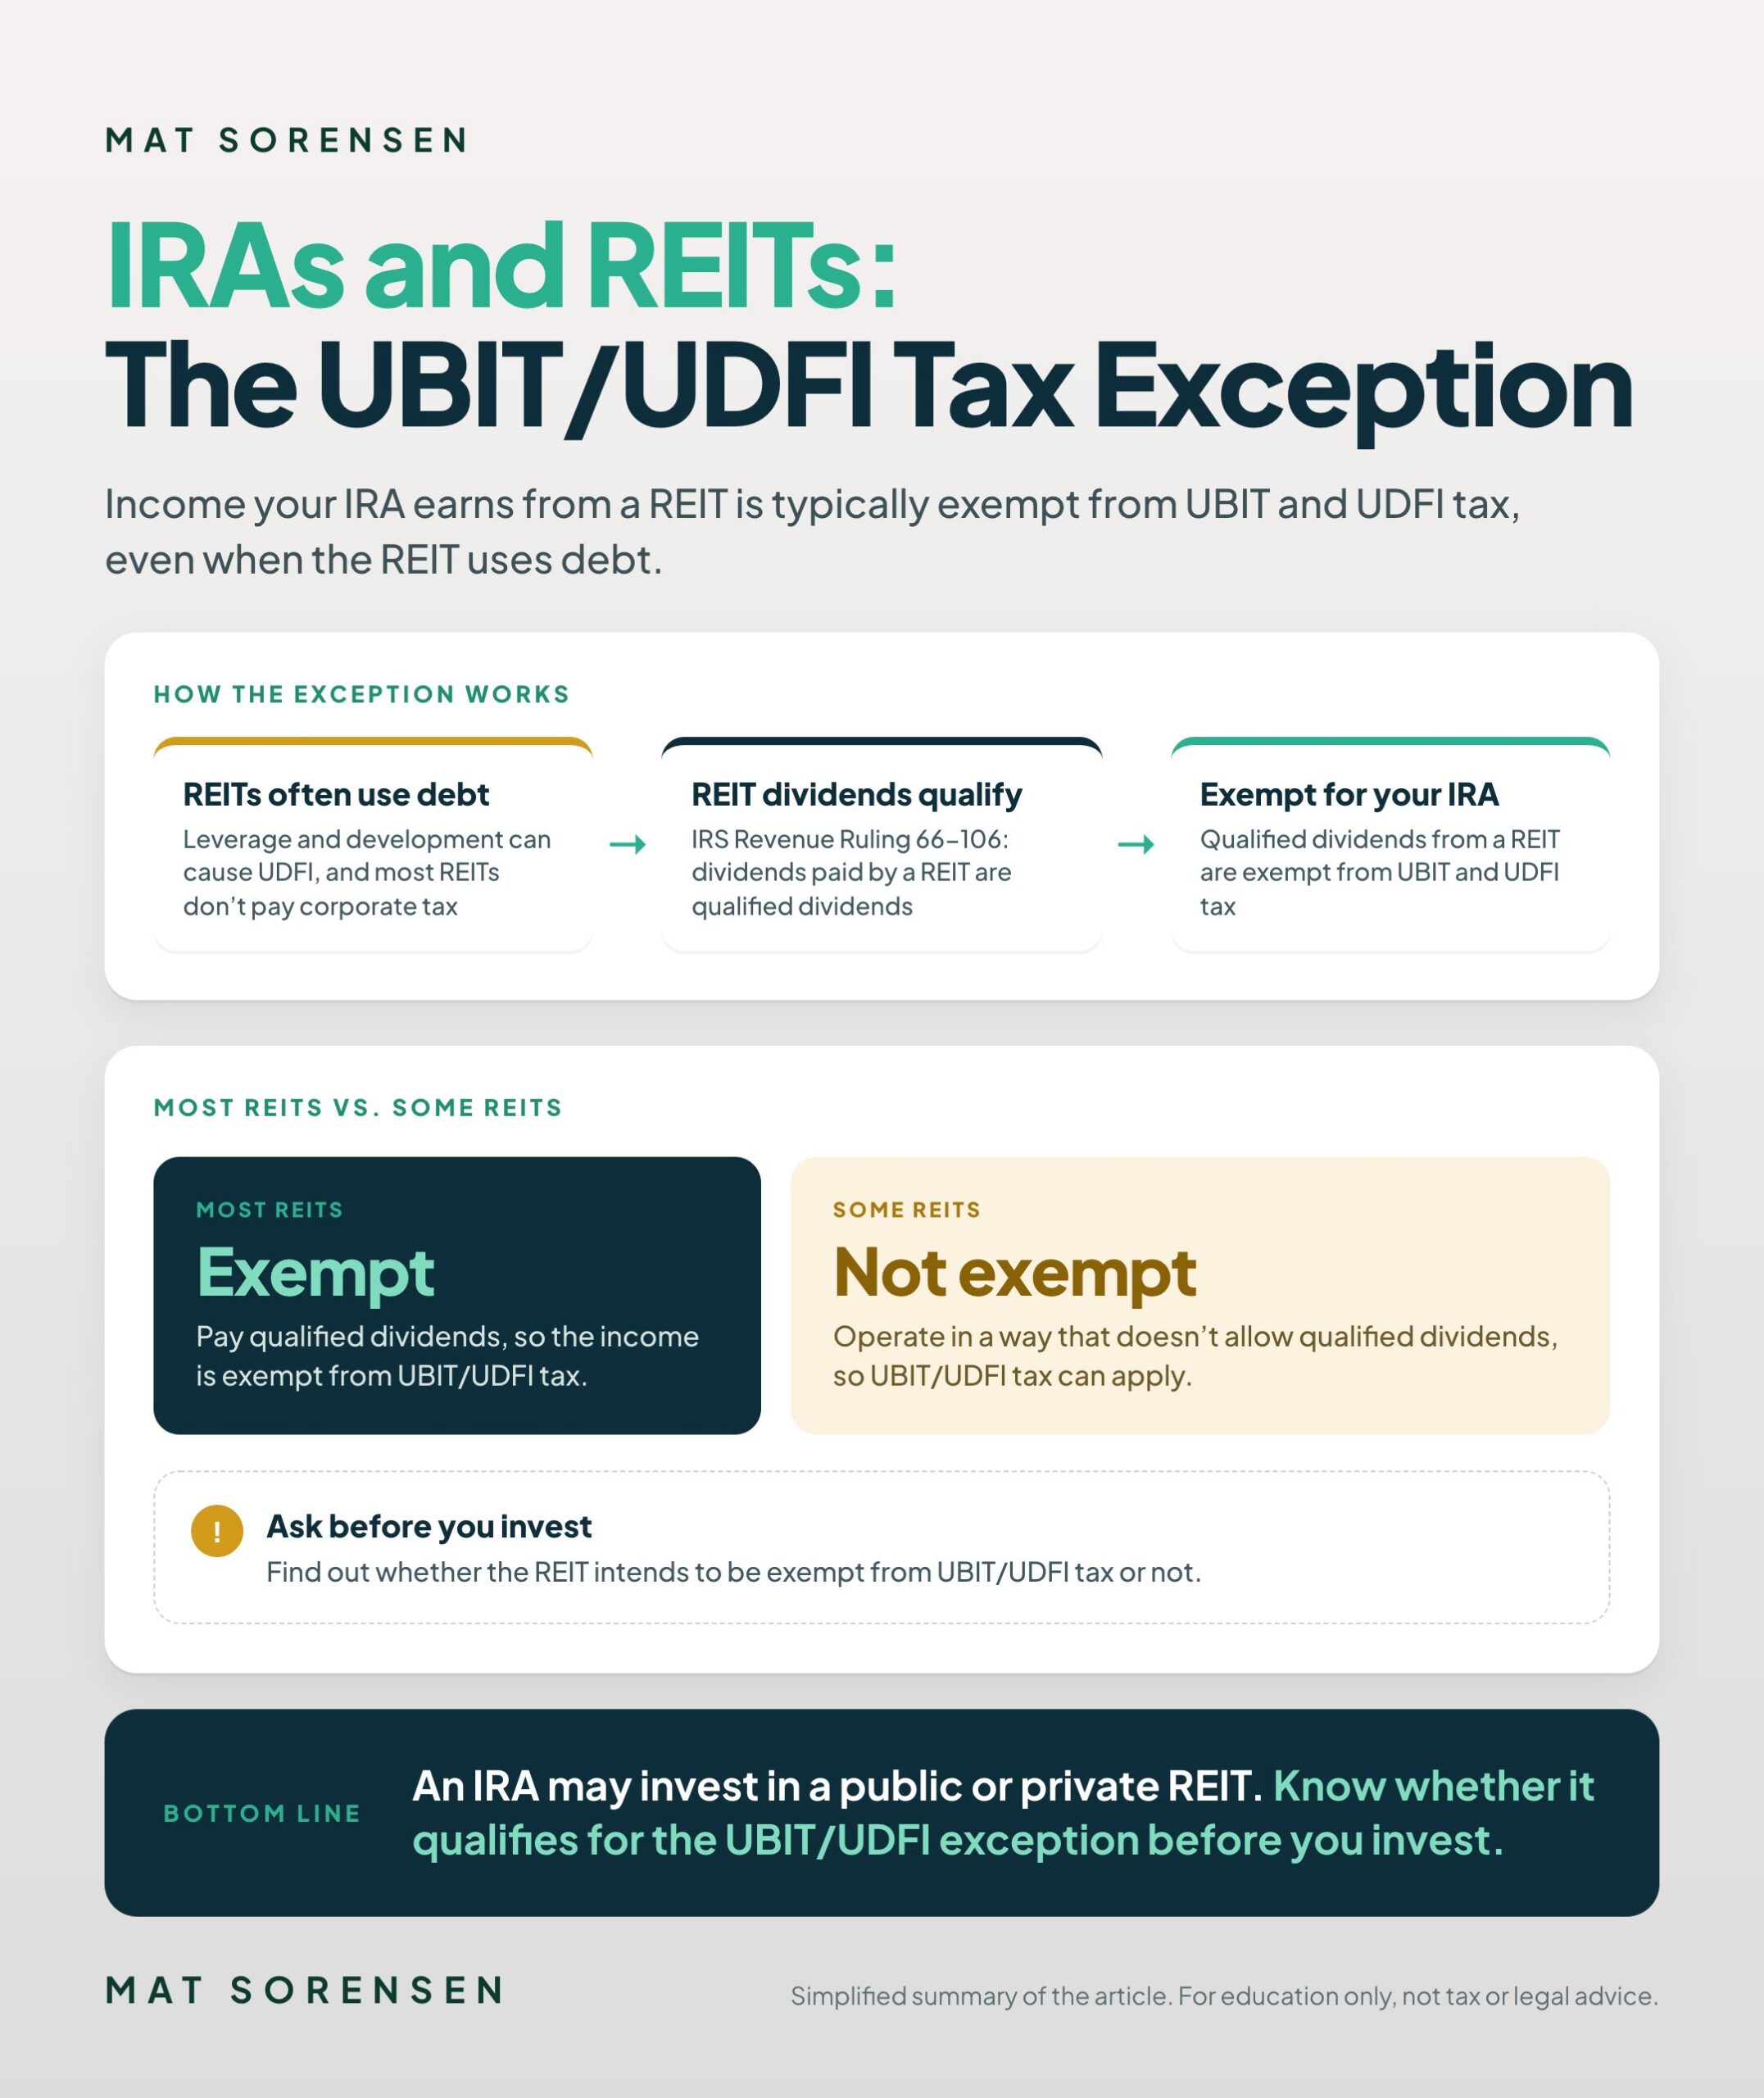
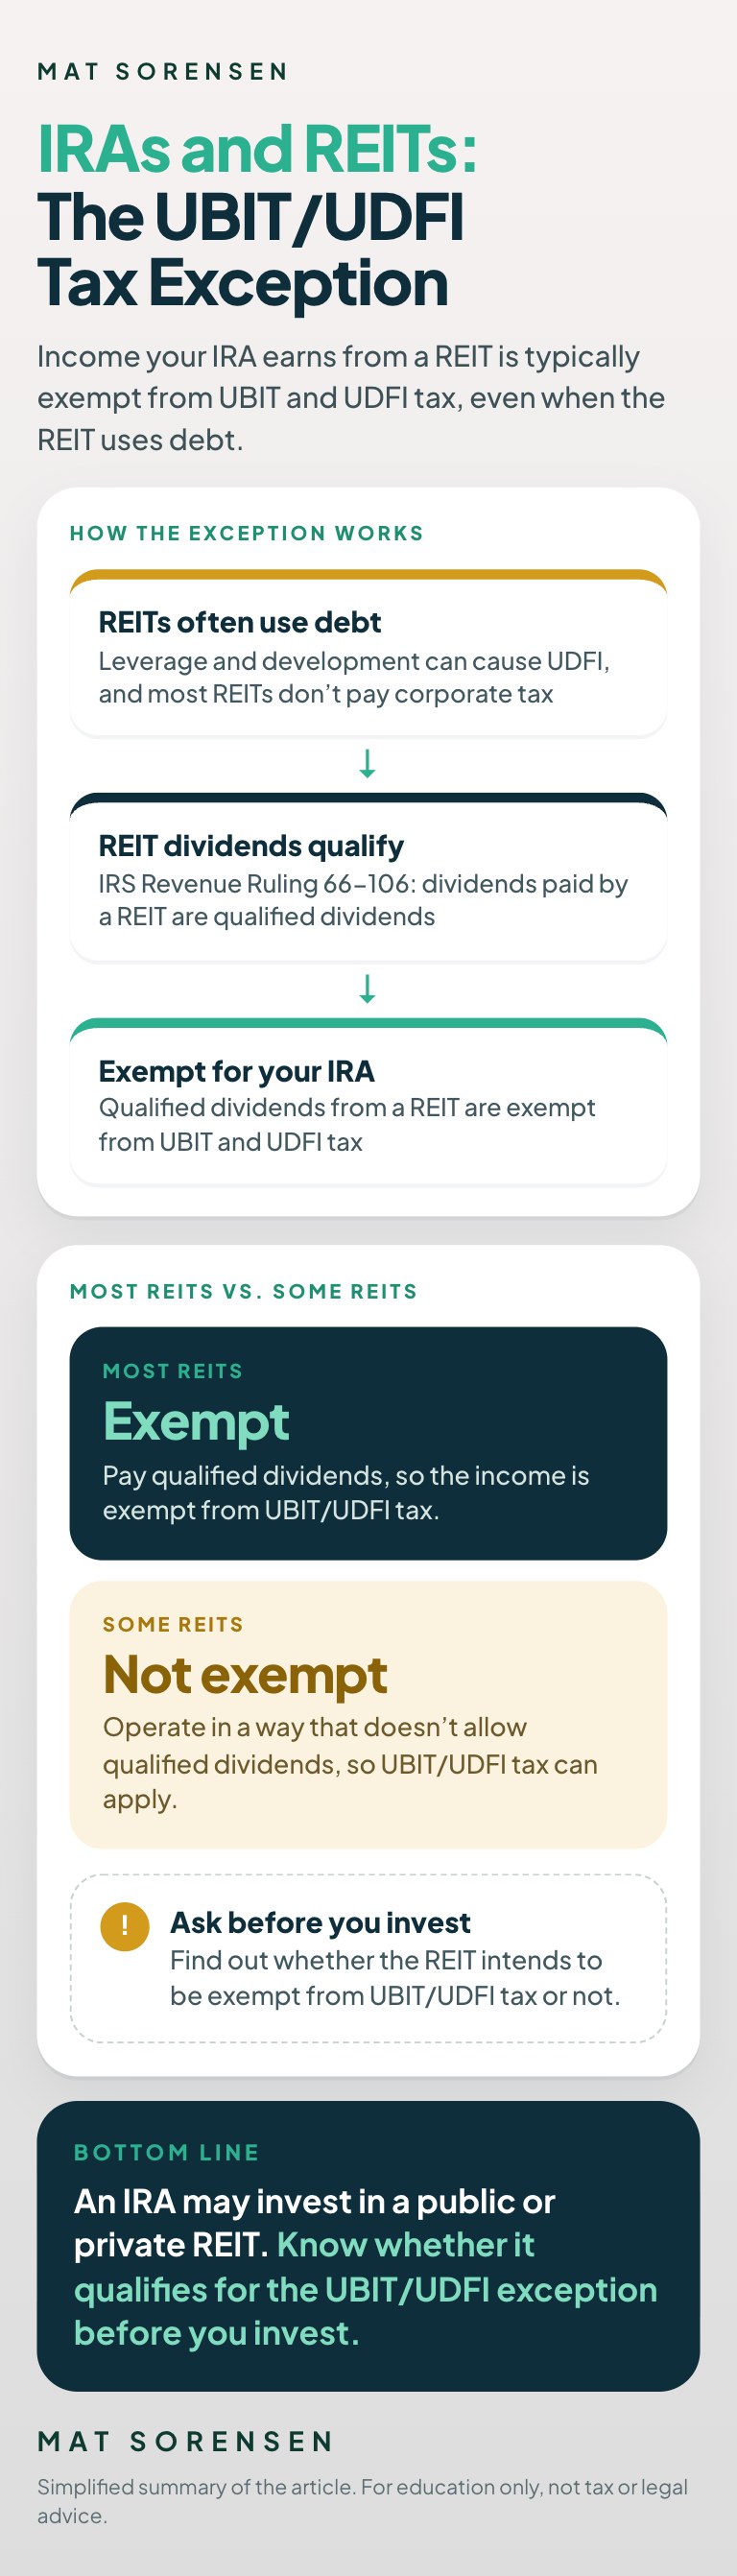
Infographic: why REIT dividends paid to an IRA are usually exempt from UBIT and UDFI tax, and when they may not be

Why REIT Income Is Usually Exempt

Many REITs engage in real estate development activities and/or use debt to leverage their cash purchasing power and as a result may cause a form of UBIT tax known as UDFI tax to IRA owners. Most REITS will not pay corporate taxes and as a result will not be considered exempt from UBIT tax as a result of having paid corporate tax. However, income from REITs is still typically exempt from UBIT and UDFI tax because the definition of a “qualified dividend” in a REIT has been defined to include dividends paid by a REIT to its owners. IRS Revenue Ruling 66-106. Qualified dividends from a REIT are exempt from UBIT and UDFI tax.

REITs can be publicly traded or private trusts but are not easy to establish. They require at least 100 owners and must distribute at least 90% of their taxable earnings to their owners each year.

When the REIT Exception May Not Apply

Despite the general application of exception to UBIT/UDFI tax for REITs, a REIT may be operated in a manner that will not allow for qualified dividends to be paid and therefore income from the REIT would not be exempt from UBIT/UDFI tax.

KEY TAKEAWAY

If you’re investing into a REIT with an IRA, make sure you know whether the REIT intends to be exempt from UBIT/UDFI tax or not. As discussed, most will be exempt from UBIT/UDFI tax but some REITs may choose to operate in ways that will not qualify for the exception.

Because UBIT/UDFI tax is about 39% at $10,000 of annual income this is something every IRA should understand before investing into a REIT.

SELF-DIRECTED IRA

Invest your IRA in real estate, private companies, notes, precious metals, and more.

Open a Self-Directed IRA