Do Good with Your IRA and Pay Zero Tax on Your Required Minimum Distributions

Required Minimum Distributions (RMD) from IRAs can be a burden for taxpayers, by raising your annual income levels and possibly boosting you into a higher tax bracket. Using the Qualified Charitable Distribution (QCD) Rule, there is a way for IRAs to do good. This rule allows IRA owners to exclude their RMDs from their annual income if given to a qualified charitable organization. Essentially, owners can deduct their RMDs on their tax returns if they give the money to a charity.

UPDATE (NOV 2026)

A QCD is excluded from your income; it is not taken as an itemized deduction. QCDs are still available from age 70½, but required minimum distributions now start at age 73 (rising to 75 in 2033) under the SECURE 2.0 Act. (Source: CRS; IRS)

KEY BENEFIT

A key benefit to the QCD is you pay zero tax on the distribution. That’s right, it’s a tax free distribution to a charity. You win, the charity wins, and the IRS loses.

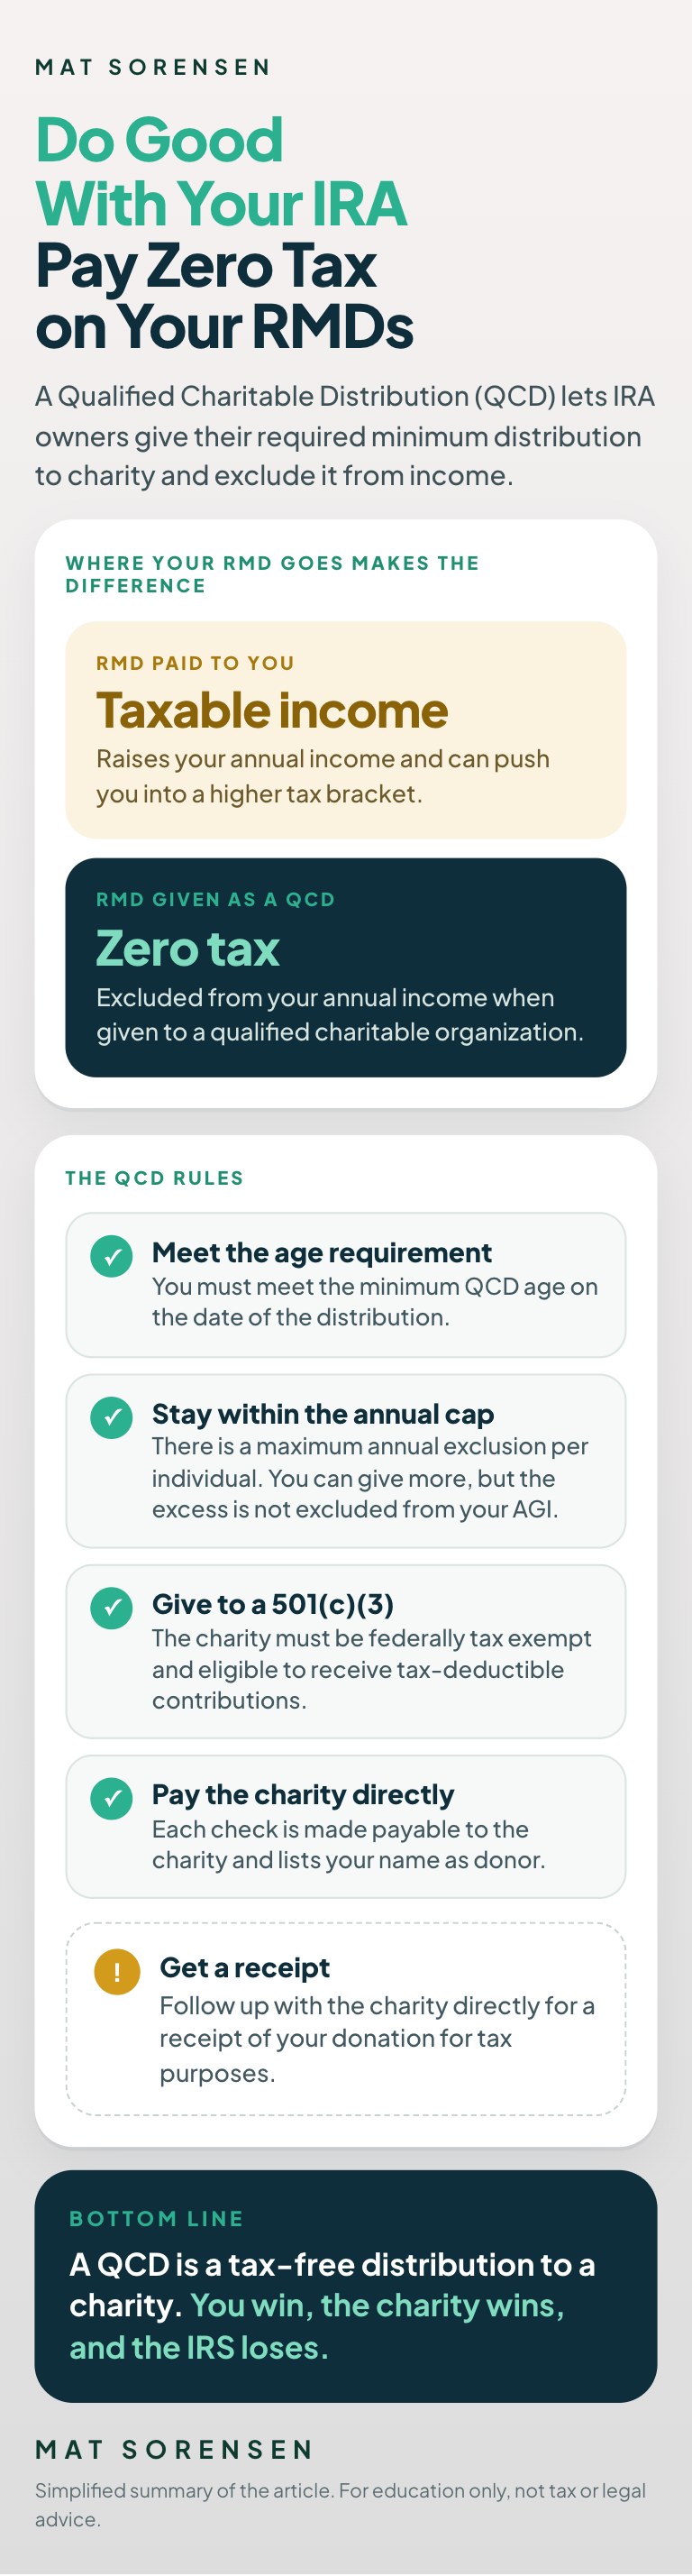
Infographic: how a qualified charitable distribution lets IRA owners give their RMD to charity tax free, and the QCD rules

The QCD Rules

Some of the rules and regulations are as follows:

  • ✓You MUST be age 70½ or older on the date of the distribution.
  • ✓The maximum annual exclusion per individual is $111,000 (2026).
  • ✓The charity must qualify as a 501(c)(3) organization and be eligible to receive tax-deductible contributions.
  • ✓Each check will be made payable to the qualified charity and list your name as donor. Note: You should follow up with the charity directly for a receipt of your donation.

To break it down further, the charitable organization must qualify as a 501(c)(3) organization, which means it is federally tax exempt as a non-profit organization. Of course the owner of the IRA can give a larger sum than $111,000 (2026) to the charity of their choosing, though any excess distributions will not be excluded from their Adjusted Gross Income (AGI).

DON’T FORGET

It is also very important to obtain a receipt from the selected charity for tax purposes.

FREE SELF-DIRECTED IRA GUIDE

Learn how to invest your IRA in real estate, private companies, notes, precious metals, and more.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

Mat Sorensen

Mat has been at the forefront of the self-directed IRA industry since 2006. He is the CEO of Directed IRA & Directed Trust Company where they handle all types of self-directed accounts (IRAs, Roth IRAs, HSAs, Coverdell ESA, Solo Ks, and Custodial Accounts) which are typically invested into real estate, private company/private equity, IRA/LLCs, notes, precious metals, and cryptocurrency. Mat is also a partner at KKOS Lawyers and serves clients nationwide from its Phoenix, AZ office.

He is published regularly on retirement, tax, and business topics, and is a VIP Contributor at Entrepreneur.com. Mat is the best-selling author of the most widely used book in the self-directed IRA industry, The Self-Directed IRA Handbook: An Authoritative Guide for Self-Directed Retirement Plan Investors and Their Advisors.

Correcting Your IRA’s RMD Failures and Avoiding the Penalty

If you failed to take required minimum distributions (RMD’s) from your IRA, then you are subject to a 25% penalty (10% if corrected within two years). The penalty is 25% on the amount you should have distributed from your IRA to yourself. It’s a steep penalty for simply failing to pay yourself from your own IRA and it’s something every IRA owner with RMD needs to understand. For my prior article explaining RMD rules for IRAs, please click here.

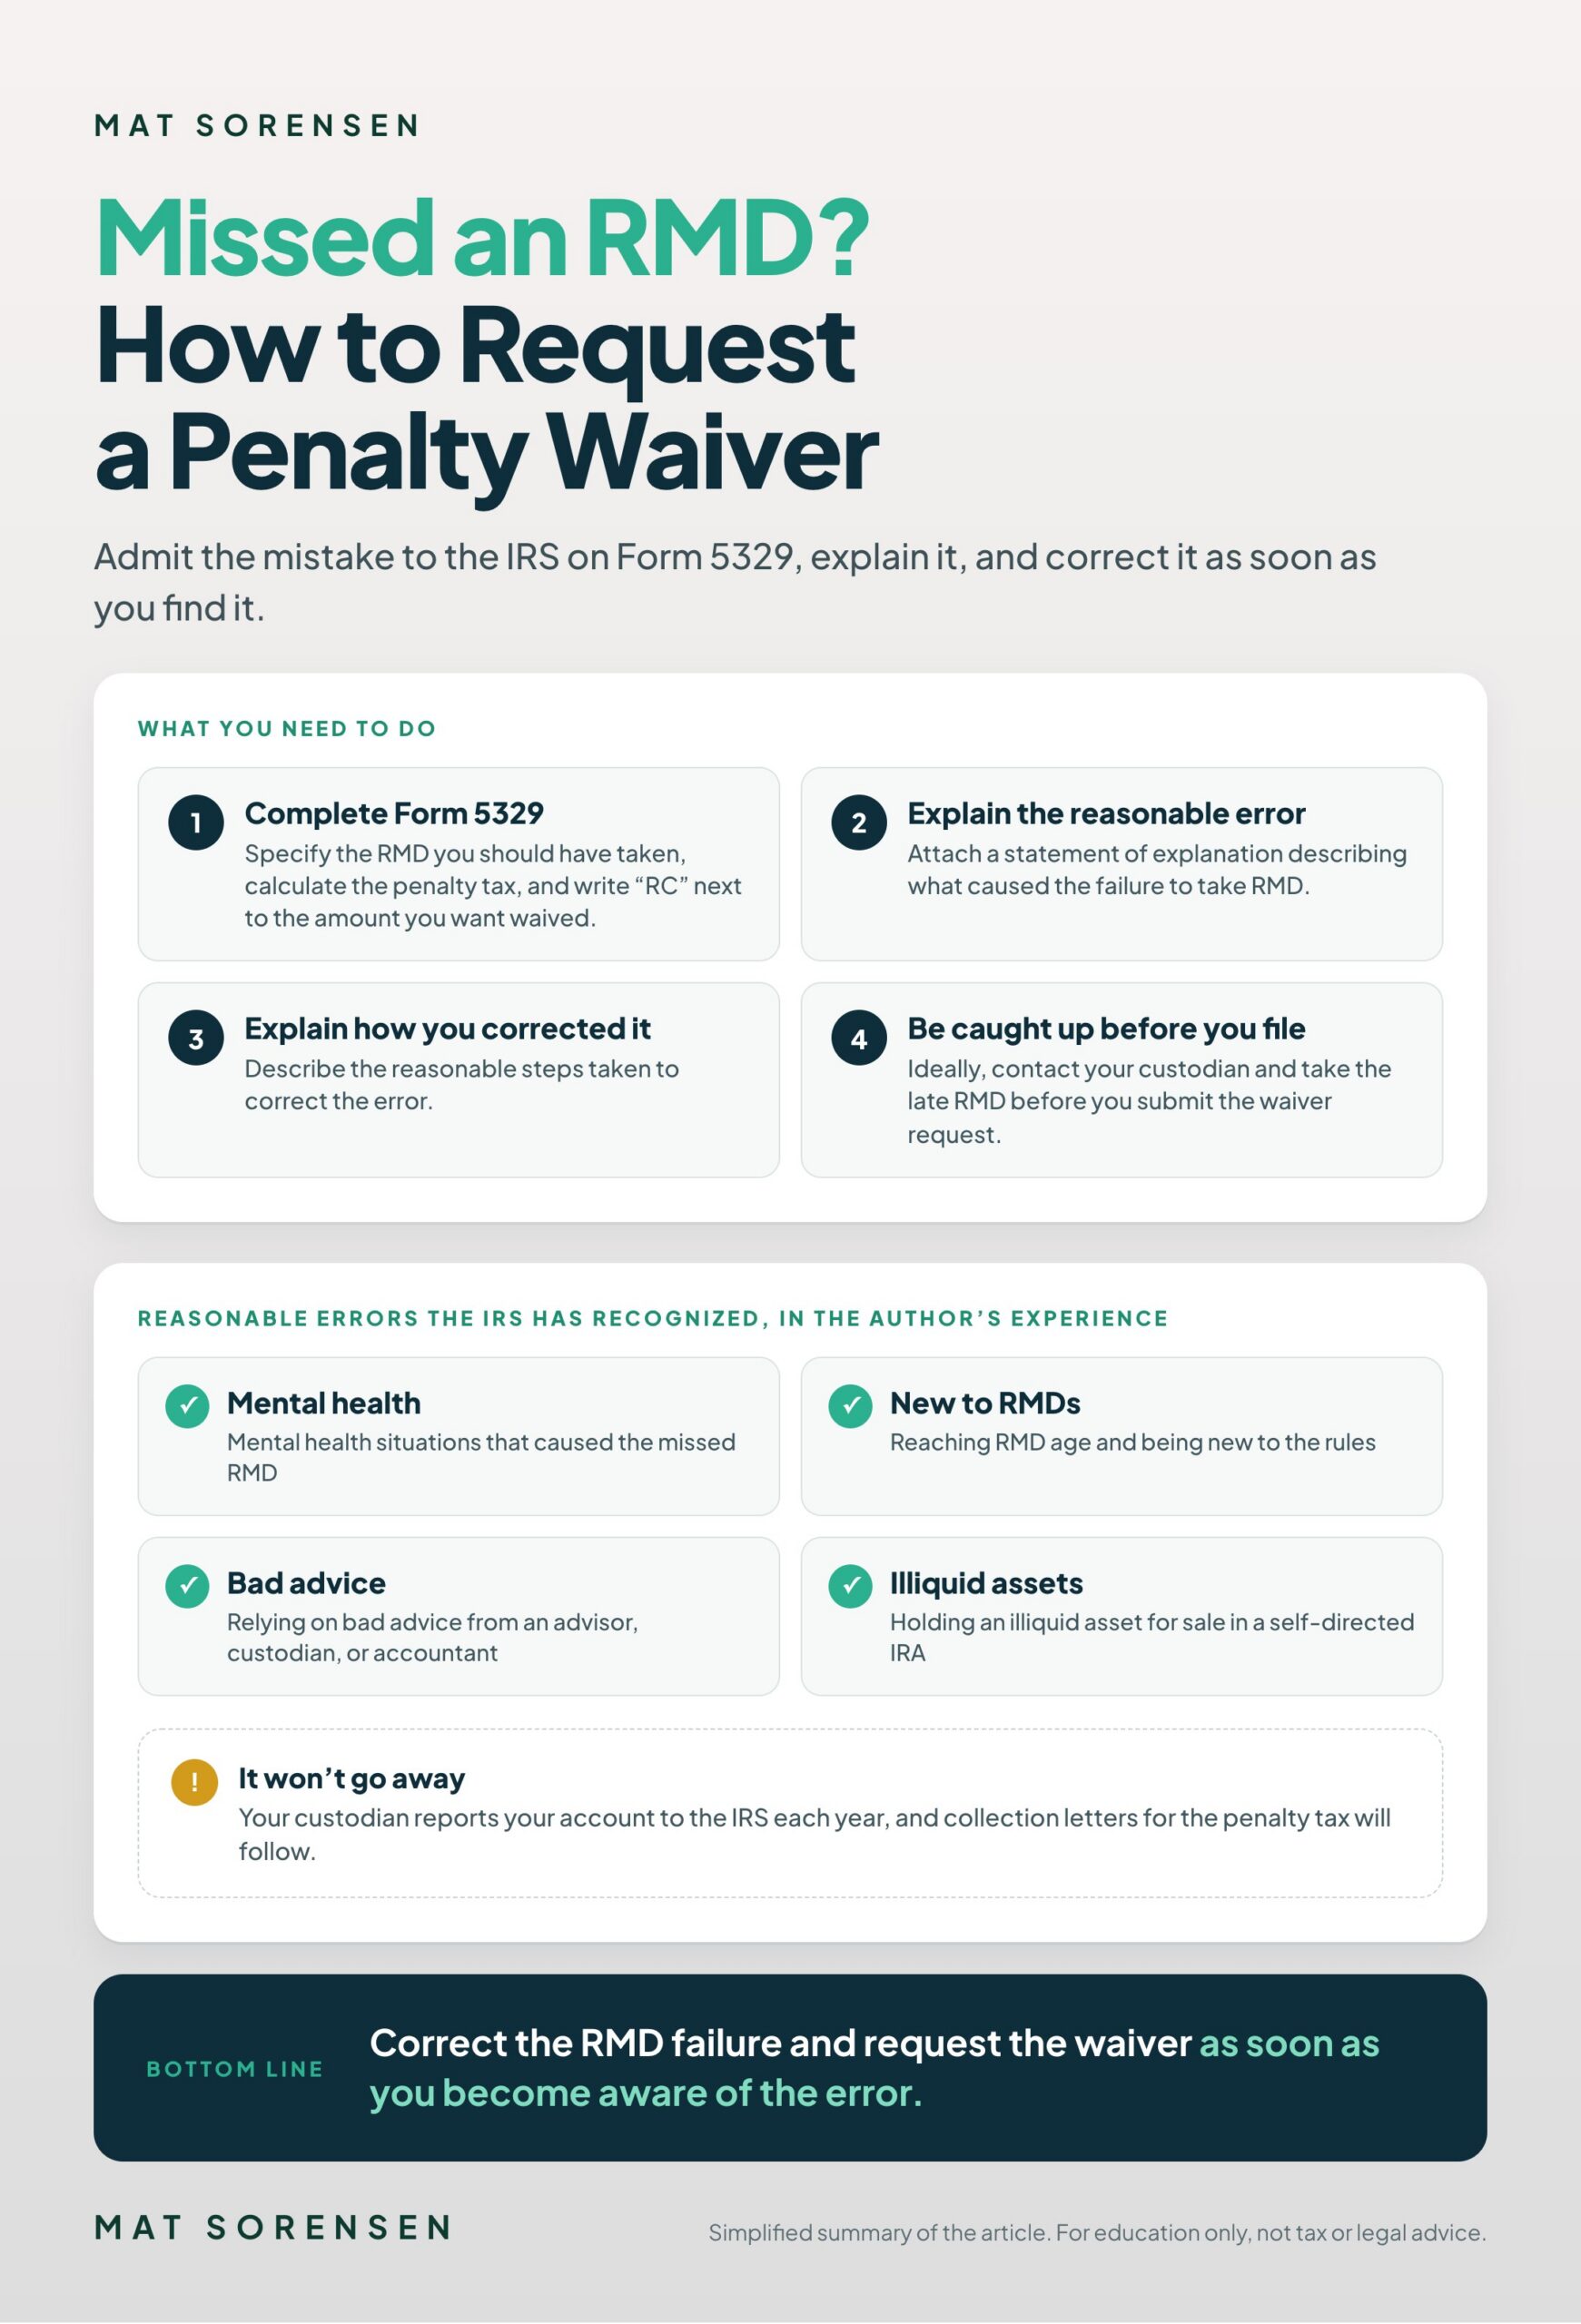
Infographic: the steps to request an IRS waiver of the missed RMD penalty on Form 5329, and examples of reasonable errors

Waiver of the Penalty Tax

UPDATE (NOV 2026)

The penalty for a missed RMD is now 25% of the amount not taken, or 10% if you correct it within two years. It was 50% when this article was written. (Source: IRS)

If you’ve failed to take RMD for your IRA, you have a chance at obtaining a waiver from the penalty but you must admit the mistake to the IRS by filing IRS form 5329. In the instructions to form 5329, the IRS outlines the waiver process to avoid the 50% penalty tax.

What You Need to Do

  1. 1Complete Section IX of Form 5329. You need to specify what you should have taken as RMD  and then you calculate the penalty tax due. You then write the letters “RC” next to the amount you want waived on line 52.
  2. 2Statement of Explanation. Attach a Statement of Explanation outlining two items.
    1. First, explain what was the “reasonable error” that caused a failure to take RMD. The IRS does not provide a definition or acceptable examples of “reasonable error”. See IRC 4974(d)(1). From my own experience and from examples I’ve heard from colleagues, the IRS does recognize reasonable errors and oversights in most situations where there is reason for the error. This would include situations such mental health, to turning 73 and being new to RMD, to relying on bad advice from an advisor, custodian or accountant, to holding an illiquid asset for sale in a self directed IRA.
    2. Second, explain the reasonable steps taken to correct the error. Ideally, by the time you’re filing the exemption request you would’ve already contacted your IRA custodian and would’ve taken the late RMD so that by the time you submit the RMD penalty tax waiver, you would be caught up and would have already remedied the error.  This makes for an easy and clean explanation of what steps you’re going to take as your explanation will be that you already corrected the RMD failure once you realized the error.

WATCH OUT

Keep in mind that RMD failures won’t go away as your IRA custodian will be updating your account each year with the IRS. Eventually, you’ll start getting collection letters from the IRS requesting the penalty tax. Consequently, IRA owners are well advised to correct the RMD failure and request the waiver as soon as they become aware of the error or oversight.

FREE SELF-DIRECTED IRA GUIDE

Learn how to invest your IRA in real estate, private companies, notes, precious metals, and more.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist