All retirement account owners must be familiar with the required minimum distribution (“RMD”) rules applicable to their accounts. These rules require you, in most instances, to take partial distributions from your retirement account when you reach age 73. And, surprise, the rules for Traditional IRAs, Roth IRAs, and 401(k)s differ. In fact, even 401(k)s where you are a 5% or greater owner have different rules than 401(k)s where you aren’t an owner. Thanks, Congress.
UPDATE (NOV 2026)
Required minimum distributions now start at age 73 (rising to 75 in 2033) under the SECURE 2.0 Act, and the penalty for a missed RMD is now 25% of the amount not taken (10% if corrected within two years). This article was first written when RMDs started at 70½ and the penalty was 50%. (Source: IRS)
So what rules apply to Solo 401(k) owners? Well, generally speaking, you must begin taking distributions from your Solo K when you reach age 73. Despite what you may think or presume, there are three quirks to be aware of when it comes to RMD and Solo 401(k):

Still Working Exception Does Not Work on Solo Ks
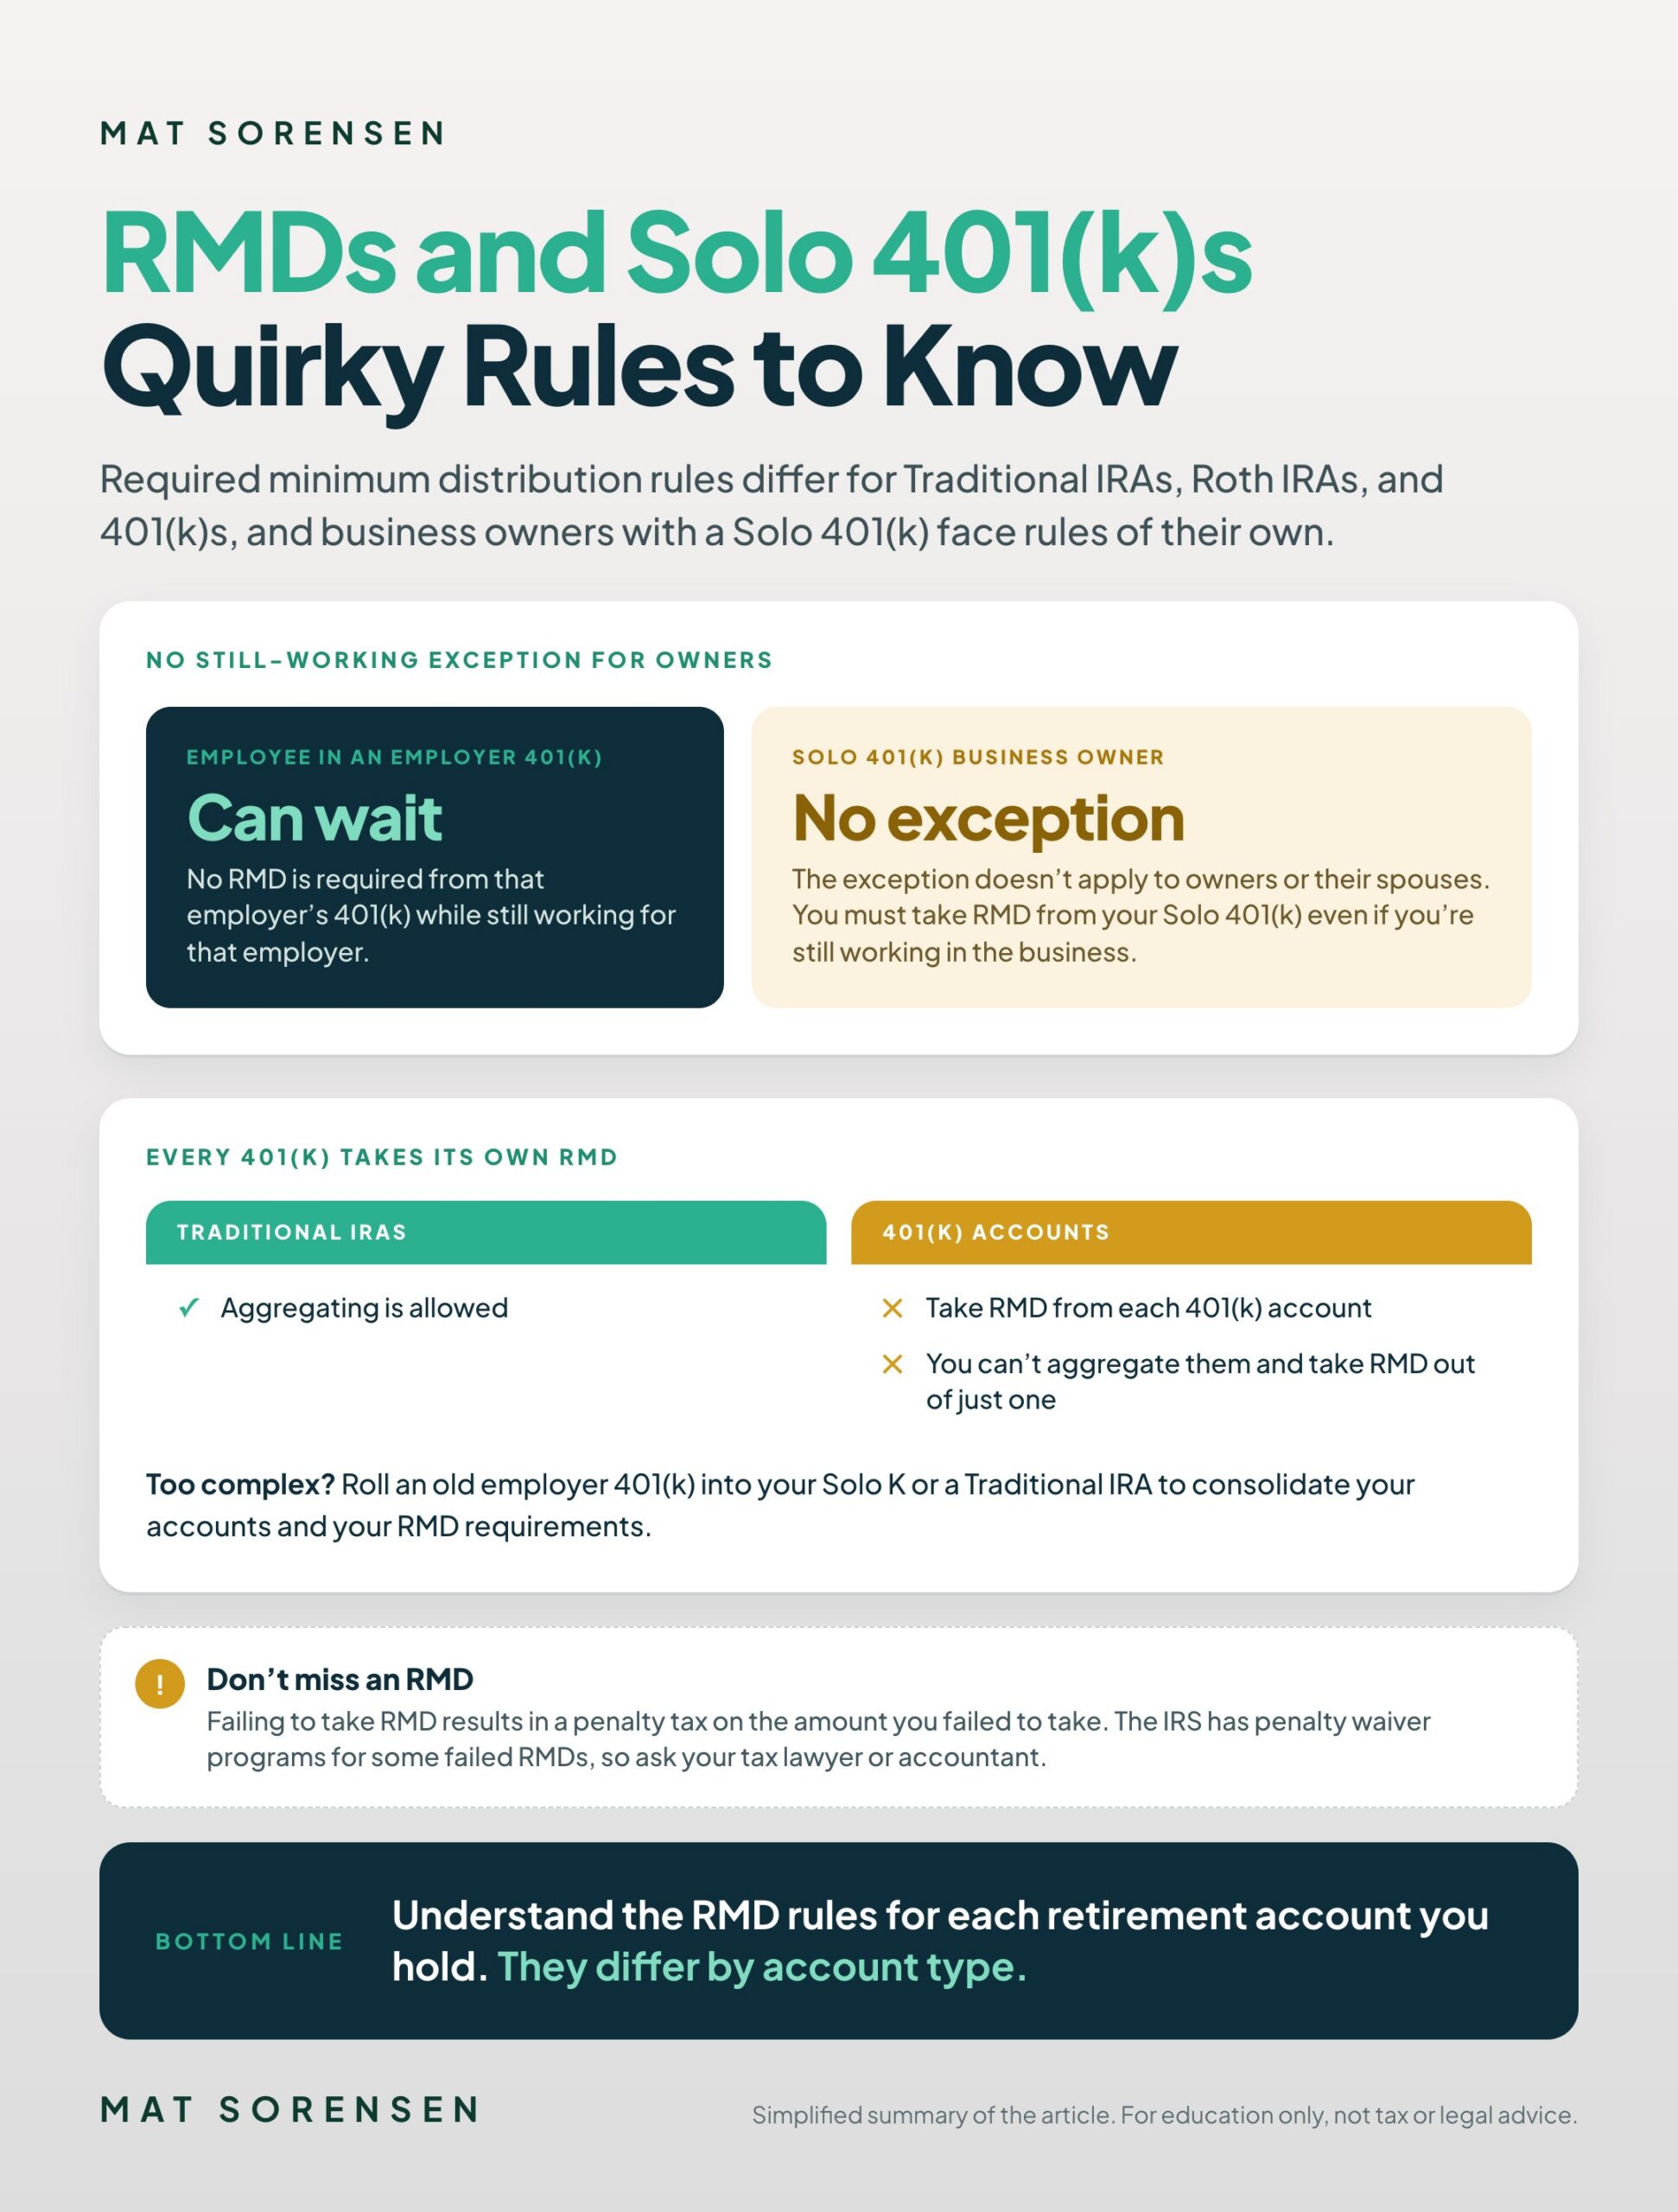
There is a general RMD 401(k) rule which states that even after age 73, you are not required to take distributions from an employer 401(k) when you are still working for that employer. However, this exception does not apply to account holders or their spouses who own 5% or more of the company. In other words, business owners who use a Solo 401(k) will be forced to take RMD from their Solo 401(k) after age 73 even if they are still working in the business.
Roth 401(k) Funds are Subject to RMD
UPDATE (NOV 2026)
Since 2024, Roth 401(k) and Roth 403(b) accounts no longer require RMDs during the owner’s lifetime (SECURE 2.0 Act). The section below describes the rules before that change. (Source: IRS)
RMD applies to Roth 401(k)s. I know what you’re thinking, “Wait, but why would RMDs apply to Roth 401(k)s when Roth IRAs are exempt?” Because Congress said so. I know, it doesn’t make much sense, Roth 401(k) distributions at retirement will be tax-free, like Roth IRA distributions, and the IRS will not receive any revenue from the distribution so why treat Roth 401(k)s differently? There’s not a good answer, but you should write your Congressperson or Senator and ask.
Every 401(k) Must Have RMD Taken, No Aggregating
Every 401(k) account you have must take RMD.
EXAMPLE
So, for example, if you have a Solo 401(k) and a 401(k) account with an old employer then you need to take RMD from each 401(k) account. You cannot aggregate those accounts together and take RMD out of one to satisfy both RMD requirements.
This aggregating is allowed in Traditional IRAs but unfortunately does not work with different 401(k) plan accounts. If taking RMDs from multiple accounts is getting too complex, you can roll the old employer 401(k) to the Solo K or to a Traditional IRA (or Roth IRA if Roth 401(k) funds) to consolidate your accounts and your RMD requirements.
Make sure to take RMD when you are required to do so. Failure to take RMD results in a 25% penalty tax (10% if corrected within two years) on the amount you failed to take. As a result, it’s critical that you understand the RMD rules for each retirement account you hold. If you have made a mistake though, the IRS does have penalty waiver programs whereby you can correct some failed RMDs and request a waiver of the penalty due. This doesn’t work in every instance, but if you’ve failed to take RMD ask your tax lawyer or accountant on whether a penalty waiver could apply in your instance.
FREE SOLO 401(K) GUIDE
Self-employed? Learn how a self-directed Solo 401(k) works and how much you can contribute.
Get the Free Solo 401(k) Guide
Prefer to talk it through? Book a call with a Directed IRA specialist